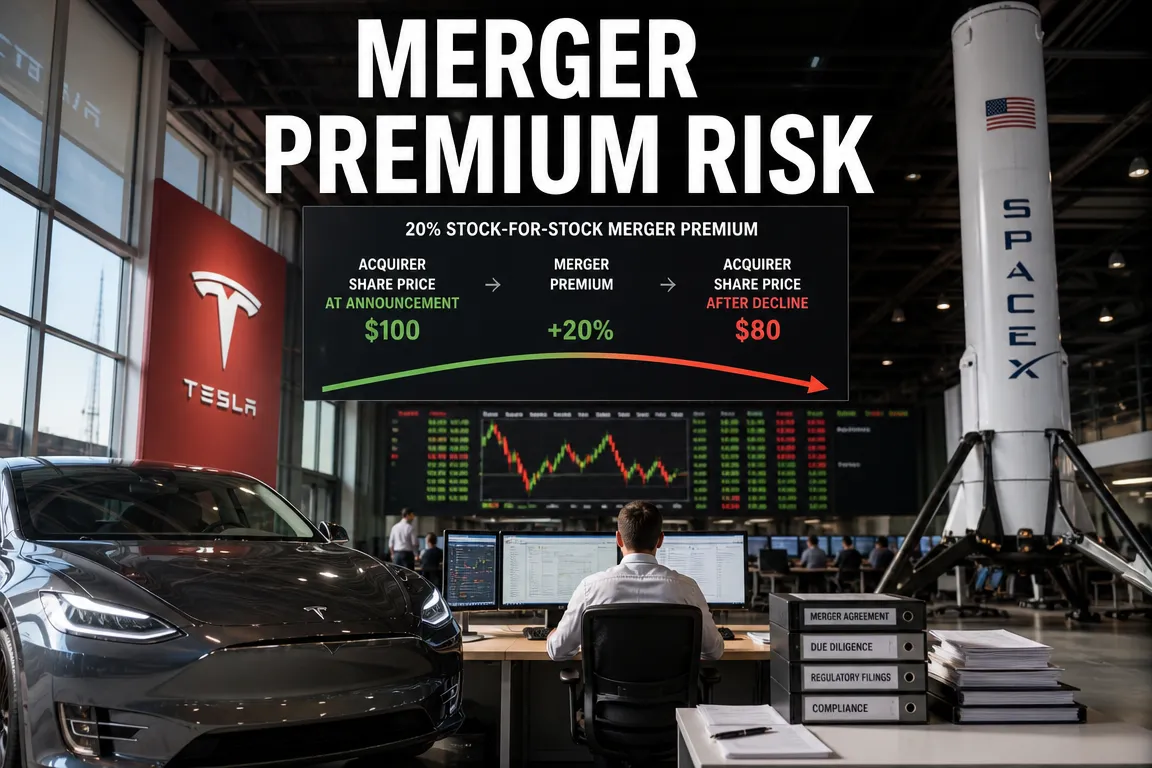
● Tesla-SpaceX Merger Shock
Why a 20% Premium in a Rumored Tesla-SpaceX Stock Merger Could Turn Into a Loss
The central issue is not the headline merger premium assigned to Tesla.
The key question is whether the value of the SpaceX shares received by Tesla shareholders can be sustained through closing.
Based on the stated assumptions, applying a 20% premium to Tesla’s closing price of $403.82 produces an initial offer value of approximately $484.58. If SpaceX shares decline 20%, however, the exchange value falls to approximately $387.66.
The transaction could therefore appear to offer a 20% premium while ultimately delivering about 4% less than Tesla’s current share price.
Several claims regarding a SpaceX listing, a Tesla-SpaceX merger process, and a semiconductor acquisition cannot be treated as confirmed without official disclosures.
This report separates verifiable facts from assumptions and focuses on the risks that a stock-for-stock merger could create for Tesla shareholders.
1. Key Fact-Checking Considerations
The primary concern is the assumption that SpaceX is already publicly listed and actively traded.
SpaceX’s listing status and market price should be verified through exchange filings, U.S. Securities and Exchange Commission documents, and official company statements.
Private-market transactions and employee tender-offer prices are not equivalent to real-time prices for publicly traded shares.
Accordingly, treating the cited SpaceX price of $146.37 as an official public-market closing price requires further verification.
Claims that Tesla and SpaceX have formed special committees and are negotiating merger terms also cannot be considered confirmed without official filings.
An investment bank’s scenario analysis is materially different from a transaction formally approved by corporate boards.
Even if merger discussions exist, shareholder consideration cannot be determined until the exchange ratio, reference price, price-protection provisions, shareholder approvals, and regulatory reviews are disclosed.
The stated terms of a Marvell-Lumentum transaction should also be checked against official company filings.
If the exchange ratio, transaction value, acquisition premium, or expected closing date is inaccurate, conclusions drawn from applying that example to Tesla and SpaceX may change.
The claim that the Federal Reserve has a 78% probability of raising rates by 0.25 percentage points in a specified month should be verified against interest-rate futures data and the relevant publication date.
Whether the probability refers to a rate increase, decrease, or hold would materially alter the interpretation of U.S. equities and technology-sector valuations.
2. Market Developments: Rotation From Technology to Cyclical Stocks
The source attributed declines in the Nasdaq and S&P 500, alongside a gain in the Dow, to capital rotating away from technology and large-cap growth stocks.
The relevant question is whether this represents a sustained sector rotation rather than a single-session move.
Companies making substantial AI data-center investments are increasingly assessed on borrowing costs, cash flow, and potential equity dilution, not only revenue growth.
In a high-rate environment, bond issuance raises interest expenses.
Equity issuance can dilute existing ownership and per-share value.
Investors are therefore shifting their focus from the scale of AI investment to the timing and magnitude of cash returns.
3. Oracle’s AI Infrastructure Financing Signal
The source stated that Oracle planned to raise $20 billion through $10 billion of equity and $10 billion of debt, followed by an approximately 8.85% decline in its share price.
The financing structure and amount require confirmation through official filings, but the market’s increased sensitivity to AI capital expenditures is notable.
AI data centers require GPUs, networking equipment, power, cooling systems, servers, optical components, land, and long-term electricity contracts.
Larger investment programs can increase future revenue potential while also raising depreciation and financing expenses.
If demand develops more slowly than expected, costs may be recognized before associated revenue materializes.
AI infrastructure competition among Microsoft, Alphabet, Meta, and Oracle supports semiconductor demand.
However, simultaneous increases in debt and equity issuance may create near-term pressure on share prices.
Investors should assess free cash flow, leverage, interest coverage, and data-center utilization in addition to capital expenditure.
4. Why SpaceX May Be Interested in Mobile Telecommunications
The source stated that SpaceX was considering acquiring EchoStar’s Boost Mobile or accessing a mobile network through a commercial arrangement.
Without official statements from the parties, this should be treated as a potential negotiation rather than a confirmed transaction.
Mobile telecommunications could allow SpaceX to extend Starlink satellite connectivity directly to conventional smartphone users.
Satellite-to-device services are developing from text messaging and emergency communications toward voice and data services.
Acquiring an operator or mobile virtual network operator with an existing subscriber base could reduce the time required for customer acquisition and service commercialization.
Key constraints include spectrum rights, telecommunications regulation, agreements with incumbent carriers, and terrestrial-network investment requirements.
Acquiring a carrier would not immediately create a fully integrated satellite and terrestrial service.
Expansion into mobile telecommunications could therefore generate both growth opportunities and additional capital expenditure risk.
5. Why Higher Tesla Sales in Europe Require Further Analysis
According to the source, Tesla’s October sales increased year over year by 248% in Sweden, 131% in Norway, 271% in Spain, 186% in Portugal, and 94% in Italy.
It also stated that Tesla recorded its highest October sales in Norway and achieved an approximately 9.8% market share.
These figures should be verified against national vehicle-registration data and the applicable reporting periods.
Factors supporting Tesla sales in Europe include fuel costs, electric-vehicle tax incentives, charging infrastructure, and Model Y demand.
High sales growth does not necessarily indicate stronger market leadership.
A low prior-year comparison base can significantly inflate growth rates.
Absolute sales should be evaluated alongside total electric-vehicle market growth, brand share, average selling prices, and discounting.
6. Why Tesla May Be Stronger in Norway Than in Denmark
The source stated that Tesla sales increased in Denmark while market share remained limited, with Chinese brands including BYD, Leapmotor, XPeng, and MG gaining stronger positions.
It described a similar competitive structure in Italy and stated that Chinese electric-vehicle brands reached a monthly record share in Norway.
European electric-vehicle markets differ by purchasing power, subsidies, taxation, charging infrastructure, and brand preferences.
Norway’s high income levels and mature electric-vehicle market may favor efficiency and charging convenience over entry-level pricing.
In more price-sensitive markets, Chinese manufacturers may benefit from broader model portfolios and aggressive pricing.
Tesla’s concentration in the Model 3 and Model Y provides manufacturing and software efficiencies but limits product variety.
The company has fewer options for buyers seeking small, lower-priced, or higher-capacity vehicles.
Additional offerings from BYD and European manufacturers could pressure Tesla’s electric-vehicle market share.
7. Supply Constraints as an Alternative Explanation for Tesla’s Performance
The source stated that Tesla’s order backlog had reached its highest level in four years and that battery availability was limiting production growth.
It also attributed to management the view that demand was materially exceeding production.
A larger order backlog does not necessarily reflect stronger final demand.
Production transitions, logistics delays, battery shortages, and certification delays can also increase backlogs.
Average delivery times, cancellation rates, inventory days, and price reductions should be assessed alongside order volumes.
The reported figures were 464,391 vehicles produced and 486,532 delivered, with deliveries exceeding production by approximately 22,000 vehicles.
This suggests that previously accumulated finished-vehicle inventory may have declined.
Lower inventory supports cash flow, but delivery growth may slow if subsequent production does not increase sufficiently.
Tesla’s valuation should therefore be assessed using production capacity, battery supply, average vehicle selling prices, and automotive margins rather than sales growth alone.
8. The Main Lesson From Stock-Financed Semiconductor Acquisitions
The source presented a scenario in which Marvell acquires Lumentum using shares rather than cash.
The cited terms included 4.5 Marvell shares for each Lumentum share and a premium of approximately 23.9% to an initial reference price.
The transaction’s existence and detailed terms require confirmation through official filings by both companies.
The central issue is that the acquisition price is defined by a fixed number of shares rather than a fixed dollar amount.
If the acquirer’s share price declines, the consideration received by target shareholders also falls.
The basic stock-exchange formula is:
Value received by target shareholders = Acquirer’s share price x Exchange ratio.
If the exchange ratio is 4.5 shares, a 10% decline in the acquirer’s share price generally reduces the consideration value by approximately 10%.
After the agreement is announced, the target’s shares may become more sensitive to the acquirer’s share price than to the target’s operating performance.
9. How a Premium Can Disappear After an Acquisition Announcement
When a company finances an acquisition with its own shares, investors often sell the acquirer’s stock.
Potential reasons include dilution, concerns about overpayment, integration risk, and higher leverage.
A decline in the acquirer’s share price automatically reduces the premium offered to target shareholders.
A premium exceeding 20% at announcement can fall below zero if the acquirer’s shares decline sharply.
Transactions requiring more than one year to close are exposed to regulatory reviews, shareholder votes, market volatility, and deteriorating business conditions.
The merger spread, which reflects closing risk and the probability of transaction failure, can continue to fluctuate throughout this period.
10. If Tesla Shareholders Receive SpaceX Shares
The central assumption is that SpaceX acquires Tesla and pays the consideration in SpaceX shares rather than cash.
Tesla shareholders would receive SpaceX shares based on an agreed exchange ratio.
The final value would therefore depend on more than Tesla’s share price.
The formula is:
Final exchange value per Tesla share = SpaceX share price x Number of SpaceX shares allocated per Tesla share.
Following closing, Tesla shareholders would shift from exposure primarily to automotive and energy operations to a broader combination of launch services, satellite communications, telecommunications infrastructure, and AI-related capital expenditure.
The characteristics of the post-merger company are therefore as important as the initial transaction premium.
11. Scenario Analysis Based on a Tesla Share Price of $403.82
Applying a 20% merger premium to the cited Tesla closing price of $403.82 produces an initial offer value of approximately $484.58.
Scenario 1: SpaceX’s share price remains unchanged
The theoretical value received by Tesla shareholders would be approximately $484.58.
The premium to Tesla’s current price would remain approximately 20%.
Scenario 2: SpaceX’s share price declines 10%
The exchange value would fall to approximately $436.12.
The effective premium to Tesla’s current price would decline to approximately 8%.
Scenario 3: SpaceX’s share price declines 20%
The exchange value would fall to approximately $387.66.
Despite the initial 20% premium, the final value would be approximately 4% below Tesla’s closing price.
Scenario 4: SpaceX’s share price increases 10%
The exchange value would rise to approximately $533.04.
The premium to Tesla’s current price would expand to approximately 32%.
A stock-for-stock merger is therefore closer to a variable-value offer than a fixed cash proposal.
12. Why Investment Banks May Favor a Stock-Exchange Structure
An all-cash merger between large companies requires substantial funding.
If the acquirer lacks sufficient cash, it may need to issue significant debt or obtain bank financing.
At elevated interest rates, this increases financing expenses and potential credit-rating pressure.
A stock-for-stock transaction allows the acquirer to conserve cash while pursuing a large transaction.
Target shareholders also retain exposure to potential appreciation in the combined company.
However, existing shareholders face dilution, while target shareholders assume exposure to a company they may not have chosen to own.
A sharp decline in the acquirer’s shares after announcement can eliminate the transaction premium.
13. Critical Issues That May Be Overlooked
First, the exchange-ratio structure is more important than the headline premium.
Investors should determine whether the transaction fixes the dollar value received or the number of shares exchanged.
Second, price-protection provisions can determine shareholder outcomes.
A collar may adjust the exchange ratio if SpaceX’s share price moves outside a specified range.
If the exchange ratio is fully fixed, Tesla shareholders would bear most of the downside from a decline in SpaceX’s share price.
Third, the liquidity of SpaceX shares is critical.
If the shares are not publicly listed, Tesla shareholders may be unable to sell them at their preferred time.
Lockups, transfer restrictions, and private-market discounts can cause realizable value to differ from the stated valuation.
Fourth, pre-closing and post-closing risks are different.
Before closing, the principal risks are approval delays and transaction failure.
After closing, valuation may reflect launch failures, Starlink capital requirements, telecommunications regulation, and volatility in space-business cash flows.
Fifth, potential conflicts of interest between Tesla and SpaceX require scrutiny.
If the companies share controlling shareholders or senior executives, independent boards, special committees, and external valuations would be central to transaction fairness.
An exchange ratio viewed as unfavorable to Tesla minority shareholders could result in litigation and shareholder opposition.
14. Checklist for Any Formal Merger Announcement
First, the number of SpaceX shares allocated per Tesla share.
Second, the closing price or average price used as the reference value.
Third, price-protection mechanisms that adjust the exchange ratio if SpaceX’s share price declines.
Fourth, whether consideration includes a combination of cash and shares.
Fifth, the expected closing date and closing conditions.
Sixth, required approvals from U.S. and international regulators.
Seventh, voting rights for Tesla and SpaceX shareholders.
Eighth, whether the Tesla brand and public listing would remain in place.
Ninth, appraisal rights and termination fees.
Tenth, liquidity restrictions if SpaceX remains private or completes an IPO.
15. Investor Interpretation
Trading Tesla shares solely on merger speculation would involve substantial volatility.
Without official disclosures, a Tesla-SpaceX merger should remain a scenario analysis rather than a confirmed investment thesis.
Even after formal terms are announced, investors should not assess the transaction based only on the initial premium.
SpaceX’s market price or private valuation, the exchange ratio, closing probability, and the combined company’s financial structure would all require evaluation.
Tesla shareholders may need to assess not only vehicle sales, FSD, robotaxis, and energy storage, but also space-industry and satellite-communications risks.
The transaction would represent a change in the underlying nature of the investment, not merely an exchange of securities.
< Summary >
Applying a 20% premium to Tesla’s closing price of $403.82 produces a theoretical merger value of approximately $484.58.
If SpaceX’s share price declines 20%, the exchange value falls to approximately $387.66, below Tesla’s current share price.
In a stock-for-stock merger, the exchange ratio, price-protection provisions, and the acquirer’s share price are more important than the headline premium.
Claims regarding a SpaceX listing, merger negotiations, and semiconductor acquisition terms require confirmation through official filings.
Tesla’s European sales may be recovering in selected markets, but Chinese competition and Tesla’s limited model portfolio remain material variables.
AI infrastructure investment supports growth opportunities, while increased debt and equity issuance may pressure technology and AI semiconductor valuations.
[Related Articles…]
*Source: [ 오늘의 테슬라 뉴스 ]
– 월가가 꼽은 1순위 방식, 반도체에서 먼저 흔들렸다 — 스페이스X 주식으로 받으면 $404 테슬라 주주는?
● AI-Driven-Shift
Using AI Is Not Enough: The “Synchronized Workflow” for the AI Agent Era
The performance gap between AI users increasingly depends not on prompting skills, but on the degree of synchronization between AI and organizational workflows.
The central issue extends beyond whether AI will replace jobs.
It concerns why employees repeatedly provide AI with the same context, how AI agents can become experienced collaborators, and how individual automation can scale into enterprise-wide AI transformation.
In particular, organizational records, decision criteria, security permissions, and feedback data are likely to become critical sources of corporate competitiveness.
1. AI Is More Likely to Replace Legacy Workflows Than Entire Occupations
The conventional question is whether artificial intelligence will replace human employment.
A more relevant question is which stages of current workflows will be redesigned around AI.
Before the internet, researchers often had to visit overseas libraries and copy physical documents to obtain academic papers.
The internet enabled researchers to search for and download papers directly.
Generative AI can now locate relevant materials, summarize key findings, compare information, and prepare initial drafts.
While the internet reduced the cost of accessing information, AI is reducing the cost of reading, organizing, and preparing information for decisions.
- Before the internet, obtaining information required substantial time and cost.
- During the internet era, search and downloading improved productivity.
- Generative AI automates summarization, analysis, and document preparation.
- AI agents connect multiple tools and execute complete workflow stages.
Future labor-market changes therefore cannot be explained solely by headcount reductions.
Rather than eliminating entire occupations at once, AI is more likely to restructure individual tasks such as research, organization, reporting, review, approval, and distribution.
2. The Transition from Generative AI to Agentic AI
Generative AI primarily produces answers or content in response to user instructions.
Reasoning AI strengthens the ability to divide complex problems into multiple stages, compare constraints, and derive conclusions.
Agentic AI advances further by receiving an objective, determining the required sequence of actions, using external tools, evaluating results, and making revisions.
| Stage of AI Development | Core Function | Business Role |
|---|---|---|
| Generative AI | Text, image, and code generation | Drafting and ideation support |
| Reasoning AI | Step-by-step analysis of complex problems | Comparison, decision support, and planning |
| Agentic AI | Tool use and task execution | Repetitive-task and workflow automation |
| Innovation AI | Support for new hypotheses and discoveries | Research, development, and new-business discovery |
| Organizational AI | Enterprise-level workflow coordination | Operating-system and decision-making support |
Viewing agentic AI as a conventional chatbot understates its potential impact.
A chatbot provides answers within a conversational interface, whereas an AI agent can connect email, calendars, documents, databases, and customer relationship management systems to execute operational tasks.
In sales, for example, an agentic workflow could research customers, prepare meeting materials, propose schedules, and record consultation results in a CRM system.
The extension of this model from individuals to teams and enterprises constitutes AI transformation, or AX.
3. Using AI and Synchronizing with AI Are Different
Frequent AI use does not necessarily indicate advanced AI capability.
Many employees repeatedly open new conversations and re-enter company information, business objectives, customer characteristics, document formats, and operating restrictions.
This is equivalent to retraining a newly hired employee every day.
AI synchronization is not limited to having AI imitate a user’s writing style.
It is the process of connecting individual and organizational records, objectives, decision criteria, operating rules, and feedback to systems that AI can use.
Effective AI capability = AI intelligence × level of individual and organizational synchronization
This is a conceptual model rather than a fixed scientific formula.
Even a high-performance model will produce generic outputs if it lacks company-specific context and operational criteria.
Conversely, a smaller model can perform well in specialized tasks when it has access to sufficient context and reliable decision standards.
4. Organizations Must “Sync” to Avoid “Sink”
Organizations that retain legacy workflows without adapting to AI may enter a “Sink” position.
A “Sync” strategy aligns AI with individual and organizational working methods.
The objective is not to transfer all human judgment to AI.
AI should handle repetitive tasks and information processing, while people retain responsibility for setting objectives, validating results, and making accountable decisions.
The remaining core human function is “Think”: determining what should be done and assessing the implications of the results.
- Sink: Maintaining legacy workflows and responding passively to AI-driven change.
- Sync: Connecting individual and team records, objectives, and standards to AI.
- Think: Validating AI outputs and designing better questions and strategic direction.
5. Four “Sync Codes” for AI Integration
AI synchronization cannot be achieved through a single effective prompt.
It requires four components: records, direction, operating structure, and feedback cycles.
5-1. Story: Making Organizational Memory Available to AI
Story refers to the operational records accumulated by individuals and organizations.
These include past project materials, meeting minutes, customer requests, success and failure cases, reports, and the rationale behind decisions.
Storing documents alone is insufficient.
Document classification and access structures must allow AI to retrieve relevant records and verify their sources.
- Standardize document titles and creation dates.
- Clearly distinguish final versions from drafts.
- Record the rationale and responsible party for important decisions.
- Apply separate access controls to customer and personal information.
- Periodically remove outdated or inaccurate materials.
In the AI era, the quality and reliability of organizational memory will be more important than document volume.
5-2. Why: Defining Objectives and Direction
An instruction such as “prepare a report” may produce a credible-looking document.
However, its practical value will remain limited if AI does not know the intended audience, the decision the report is expected to support, or the primary evaluation criteria.
Instructions should therefore include not only the task, but also its purpose and success conditions.
- Explain why the task is being performed.
- Identify the intended user and operating context.
- Specify the metrics that must be included.
- Define acceptable error thresholds and prohibited actions.
- Provide examples of high-quality outputs.
AI is not an executive that assumes responsibility for objectives. It is a system that optimizes the objectives it receives.
An incorrectly defined objective can therefore be pursued with considerable efficiency.
5-3. Native: Designing Human-AI Operating Structures
An AI-native workflow is not created by adding a single AI function to an existing process.
It requires redesigning responsibilities, review procedures, and approval controls around the relative strengths of people and AI.
AI is effective in large-scale information processing, drafting, repetitive classification, and pattern detection.
People retain advantages in contextual interpretation, stakeholder coordination, ethical judgment, and final accountability.
| Workflow Stage | AI Role | Human Role |
|---|---|---|
| Research | Search, collection, classification, and summarization | Validation of source reliability and relevance |
| Planning | Generation of alternatives and scenarios | Objective setting and prioritization |
| Document Preparation | Drafting and formatting | Review of logic, language, and factual accuracy |
| Execution | Repetitive tasks and system entry | Exception handling and final approval |
| Performance Assessment | Data analysis and pattern detection | Causal interpretation and accountable judgment |
For high-impact activities, organizations should clearly distinguish between actions AI may execute automatically and actions that require human approval.
5-4. Cycle: Building a Continuous Feedback System
No prompt or workflow remains effective indefinitely.
As markets, customer requirements, internal policies, and regulations change, AI operating criteria must also be updated.
Organizations need a recurring process that distinguishes effective from ineffective outputs, identifies the causes of errors, and incorporates findings into operating rules.
- AI produces a draft or executes a task.
- A person evaluates accuracy, completeness, and risk.
- Corrections and evaluation rationales are recorded.
- Recurring feedback is incorporated into rules and templates.
- Performance is measured again after the workflow is revised.
Feedback retained only in individual chat histories does not become an organizational asset.
High-quality examples and error cases must be incorporated into shared team standards.
6. How AI Changes the Productivity Equation
Productivity is generally defined as output relative to inputs.
Productivity = Output ÷ Labor hours, cost, and resources
If AI enables more output during the same working hours, productivity improves through output expansion.
If the same output can be produced in less time, productivity improves through input reduction.
- An employee may produce three reports instead of one in the same period.
- A three-hour research task may be reduced to one hour.
- Saved time may be reallocated to customer engagement, strategy, or training.
- Omissions and formatting errors in repetitive tasks may decline.
Higher output volume does not automatically translate into higher productivity.
If AI increases the number of unnecessary documents and meeting materials, enterprise-wide information-processing costs may rise.
Productivity should therefore be measured through outcomes such as revenue, cost savings, processing time, customer satisfaction, and error rates rather than document volume.
7. Practical AI Synchronization Methods for Employees
7-1. Document Repeated Instructions
Consolidate information that is repeatedly provided to AI into a standard reference document.
This may include company and team responsibilities, major customer segments, writing standards, preferred terminology, and prohibited expressions.
7-2. Provide Examples of High-Quality Outputs
AI identifies intended formats more accurately when given specific examples rather than abstract instructions.
Previously approved reports or emails can be anonymized and used as reference materials.
7-3. Standardize Task-Request Templates
Create templates that specify the objective, input materials, output format, evaluation criteria, and operating restrictions.
Business objective:Intended user:Reference materials:Required content:Excluded content:Output format:Validation criteria:Items requiring final human approval:
7-4. Require Sources and Supporting Evidence
Material facts and figures should include sources and reference dates.
AI should separately identify unsourced information, potentially outdated information, and inferred conclusions.
7-5. Begin with Low-Risk Automation
High-risk functions such as human resources, finance, and contracts should not be fully automated at the initial stage.
Implementation should begin with limited-impact, easily verified tasks such as meeting summaries, email drafts, and document classification.
8. The Most Important Issue Often Overlooked in AI Coverage
In the AI era, sustainable competitive advantage is more likely to arise from proprietary contextual data than from the underlying model.
If most companies can access similar AI models, the model alone will provide limited long-term differentiation.
By contrast, customer knowledge, operating standards, failure records, and decision-making practices accumulated over time are difficult for competitors to replicate.
Competitive advantage may therefore favor companies that connect organizational knowledge securely and accurately, rather than those that purchase the most expensive AI systems.
8-1. Context Management Becomes More Important Than Prompting
Early generative AI adoption emphasized prompt-writing skills.
In the agentic AI era, performance increasingly depends on which documents and datasets AI can access, which rules receive priority, and how historical feedback is retrieved.
Continuously maintained business context is therefore becoming more important than individual prompt techniques.
8-2. AI Synchronization Is Also a Security and Access-Control Issue
As AI connects to more operational records, the risks of data leakage and unauthorized execution increase.
Synchronization does not mean connecting every data source to AI.
Data access and execution permissions should be assigned according to role and responsibility.
- Do not enter customer personal data or confidential information into external AI systems without authorization.
- Require human approval before AI sends emails or executes payments.
- Maintain audit logs identifying who used specific data.
- Immediately revise permissions when employees leave or transfer departments.
- Assign clear accountability for problems caused by AI-generated outputs or actions.
8-3. The AI Divide Will Extend Beyond Users and Non-Users
An initial performance gap may emerge between people who use AI and those who do not.
A larger gap may subsequently develop between those who use AI for isolated searches or document preparation and those who integrate it into operating systems.
At the individual level, users who systematically manage their data, standards, and feedback are likely to outperform one-time users.
8-4. AI Return on Investment Depends More on Workflow Redesign Than Technology
A common reason AI investments fail to generate returns is that companies add AI functions without changing existing workflows.
Actual return on investment should include implementation costs, review time, error-correction expenses, and security-management costs.
If employees must rewrite AI-generated drafts from the beginning, the automation benefit remains limited.
Material cost savings generally require eliminating unnecessary process stages or simplifying approval structures.
9. Implications for the Economic Outlook and Corporate Competitiveness
The adoption of AI agents may affect corporate cost structures and labor markets, extending beyond the technology sector.
Lower processing costs for repetitive administrative work may allow companies to serve more customers and manage larger workloads with the same workforce.
However, productivity disparities may widen between large companies with established AI infrastructure and smaller companies with limited implementation capacity.
Economic assessments should therefore consider not only AI investment levels, but also actual adoption rates and measurable productivity gains.
- Investment in AI software and cloud infrastructure may increase.
- Demand may rise for data management, cybersecurity, and AI audit services.
- Roles focused on workflow design and validation may gain value relative to routine administrative positions.
- Profitability and labor-cost structures may diverge according to enterprise AI capabilities.
- AI may accelerate digital transformation in government and public administration.
The timing and scale of macroeconomic productivity gains will vary by industry.
Technology deployment and organizational restructuring require time and capital, while poorly designed automation may increase errors and administrative burdens.
10. The Final Human Responsibility Is to Think
As AI assumes a greater role in research, summarization, and execution, human responsibilities will change rather than disappear.
People must still decide what to automate, which outputs to trust, and who remains accountable.
The most important capabilities will be the ability to explain business objectives, validate outputs, and improve operating systems rather than familiarity with a large number of AI tools.
- The ability to define problems accurately.
- The expertise to distinguish effective outputs from ineffective ones.
- The ability to identify AI errors and bias.
- The ability to structure and document organizational workflows.
- The judgment required to assume responsibility for final outcomes.
The disappearance of legacy workflows does not necessarily imply the disappearance of work itself.
Employees and organizations that adopt new operating models can use AI as an experienced collaborator. Those that retain existing practices may continue retraining the equivalent of a new AI employee every day.
< Summary >
- The central competitive capability in the AI era is not basic usage, but synchronization between AI and individual or organizational operating standards.
- Effective AI performance increases when both model capability and synchronization levels improve.
- Synchronization can be developed through Story, Why, Native, and Cycle: records, direction, operating structure, and continuous improvement.
- AI agents extend beyond content generation by using external tools and executing workflow stages.
- Proprietary organizational records and decision criteria may provide more sustainable differentiation than the AI model itself.
- Productivity should be evaluated through time savings, cost reductions, error rates, revenue, and other measurable outcomes rather than output volume.
- As AI capabilities expand, people will focus increasingly on problem definition, validation, and accountable judgment.
[Related Articles…]
*Source: [ 경제 읽어주는 남자(김광석TV) ]
– AI 그냥 쓰면 뒤처진다…살아남는 사람은 ‘동기화’부터 다르다 | 김광석의 북리뷰 | ‘에이전트 워크플로우’ [2편]