● Nvidia, Scandal, Risk, AI, Fallout
The Larger Issue Beyond the Jensen Huang Scandal: Fact-Checking Nvidia’s Leadership Risk and the AI Ecosystem
The central issue is not the allegation concerning Jensen Huang’s private life.
The key structural risks involve Nvidia’s concentration of decision-making around Huang, AI data center financing, U.S. export controls, enforcement against indirect exports to China, and potential effects on the HBM market.
However, claims that Huang admitted to an affair, had links to an alleged spy, faced a board investigation, or became subject to a U.S. congressional inquiry have not been supported by official statements and corroborating reports from multiple major news organizations.
These claims should therefore be treated as market scenarios based on unverified allegations, not as established facts.
1. Primary Conclusion
The allegations concerning Jensen Huang cannot be verified from the source material provided.
The source claims that Huang issued a statement admitting to an affair, that the other individual was suspected of links to Chinese intelligence, and that Nvidia’s board initiated an investigation.
However, it provides no original statement, Nvidia filing, board announcement, U.S. government document, or law enforcement disclosure.
Allegations involving an individual’s private life and possible espionage links can cause severe reputational damage and should not be presented as facts based solely on unverified videos or online posts.
Claims attributing declines in Nvidia shares, Nasdaq futures, and the KOSPI to this issue also require precise trading dates and supporting market data.
Equity markets reflect multiple variables, including interest rates, earnings expectations, options expirations, geopolitical risk, and semiconductor industry conditions.
2. Major Claims Requiring Verification
- Claim that Jensen Huang publicly admitted to an affair: Verification requires an original statement from Nvidia or corroboration by credible news organizations.
- Claim that the other individual was suspected of being a Chinese spy: This cannot be established without an indictment, sanctions action, or investigation announced by a government agency.
- Claim that Nvidia’s board initiated an investigation: A board statement or securities filing would be required.
- Claim that President Donald Trump defended Huang: An official video, transcript, or White House record would be required.
- Claim that three U.S. House committees are investigating Nvidia’s security controls: The relevant committee names, official letters, or hearing materials should be identified.
- Claim that a Singapore-based company indirectly supplied advanced Nvidia GPUs to China: Confirmation would require findings from the U.S. Department of Commerce or law enforcement authorities.
If these claims cannot be independently verified, the broader narrative may represent a combination of speculation rather than factual reporting.
3. Key-Person Risk Independent of the Allegations
The most economically relevant issue raised by the source is Nvidia’s dependence on a central leadership figure.
Jensen Huang is not only Nvidia’s chief executive but also the public figure most closely associated with its technology roadmap, customer relationships, developer ecosystem, government engagement, and major investment decisions.
Nvidia is more than a GPU vendor.
Its competitive position includes the CUDA software ecosystem, networking equipment, AI server platforms, cloud partnerships, and data center investments.
In this structure, any disruption involving the chief executive’s judgment, credibility, or availability could have a greater impact than at a conventionally managed company.
Nvidia is also known for a relatively flat management structure in which numerous senior executives report directly to Huang.
This can accelerate decision-making but may increase exposure to leadership disruption if a clear succession plan is not visible to external stakeholders.
However, the assumption that Nvidia would immediately destabilize without Huang may be overstated.
Nvidia has a board, executive management team, technical leadership, and operating divisions. As a listed company, it is not legally or operationally dependent on one individual alone.
4. Is Nvidia the Central Bank of the AI Ecosystem?
The source describes Nvidia as a central bank for the AI industry because it provides capital and support to customers.
The analogy has limited descriptive value but is not economically precise.
A central bank issues currency and provides liquidity of last resort to the financial system.
Nvidia is a private company that supports AI infrastructure expansion through GPU supply, strategic equity investments, cloud partnerships, and purchase agreements.
It is therefore more accurately described as a core AI infrastructure platform and strategic capital provider.
The claim that Nvidia provided $300 billion to customers over the past three years also requires a detailed source and methodology.
Its significance depends on whether the figure combines direct investments, purchase commitments, GPU supply contracts, and customers’ own capital expenditures.
5. Why CoreWeave and Neocloud Providers Represent Potential Vulnerabilities
Neocloud companies acquire large volumes of Nvidia GPUs and lease specialized AI computing capacity to enterprise customers.
CoreWeave and Lambda are frequently cited examples.
These companies can grow rapidly when AI demand is strong, but GPU purchases and data center construction require substantial capital.
Some operators finance expansion through GPU-backed loans or long-term customer contracts, increasing their sensitivity to interest rates and capital market conditions.
If demand develops more slowly than expected or major customers reduce contractual commitments, cash flow and leverage could deteriorate simultaneously.
GPU price declines or new product launches could also reduce the collateral value and rental rates of existing equipment.
Investors should prioritize the following indicators:
- Debt levels and interest expenses at neocloud providers
- Cancellation provisions in long-term contracts
- Revenue concentration among major customers
- GPU utilization rates and hourly rental prices
- Residual values of older GPUs
- Capacity for additional financing from Nvidia and major financial institutions
6. Why Higher CDS Spreads Should Not Be Treated as Default Probabilities
The source cites an increase in Nvidia’s credit default swap spreads and presents it as an indicator of potential insolvency.
A CDS spread is better understood as the cost of insuring against a debt default.
A higher spread may indicate rising market concern about credit risk, but it is not equivalent to an actual probability of bankruptcy.
In less liquid CDS markets, limited trading activity can produce significant price movements.
Bond maturities, assumed recovery rates, trading volumes, and broader risk sentiment must also be considered.
Nvidia’s credit profile should be assessed using cash and equivalents, operating cash flow, corporate bond yields, and credit ratings in addition to CDS pricing.
7. Scenario Analysis for Expanded U.S. Export Controls
Regardless of the allegations, tighter U.S. export controls on advanced technology supplied to China remain a material semiconductor industry risk.
U.S. authorities are concerned that advanced AI chips and semiconductor manufacturing equipment could support China’s military and intelligence capabilities.
Stricter rules could limit the performance and volume of products Nvidia is permitted to sell into the Chinese market.
However, the source appears to conflate lower-specification products designed for China with the H200.
Advanced data center GPUs such as the H200 must be distinguished from products specifically configured to comply with China-related restrictions.
Incorrect product classifications or export licensing assumptions can materially distort revenue estimates.
If the United States intensifies enforcement against indirect exports through Southeast Asia, data center operators in Singapore, Malaysia, and the Middle East may face enhanced end-user verification requirements.
This could extend contract review periods and require customers to provide additional documentation concerning installation locations and ultimate users.
8. Effects of GPU Restrictions on HBM and Korean Semiconductor Companies
AI GPUs use high-bandwidth memory to process large volumes of data at high speed.
A decline in GPU shipments could therefore affect the HBM market, including SK hynix, Samsung Electronics, and Micron.
However, lower GPU shipments to selected regions would not necessarily reduce global HBM demand by the same proportion.
Volumes initially intended for China could be redirected to data centers in the United States, the Middle East, Europe, or Japan.
Next-generation AI accelerators are also designed to incorporate greater HBM capacity per unit.
Even if GPU shipment growth moderates, higher memory content per accelerator could support aggregate HBM demand.
For Korean semiconductor investors, the principal indicators are HBM supply agreements, customer qualification, production yields, average selling prices, and capital expenditure plans rather than short-term share-price movements.
9. Why Nvidia’s Share Price May Be Particularly Sensitive
Nvidia’s share price reflects more than the earnings outlook of a conventional semiconductor company.
It incorporates expectations for AI data center investment, hyperscaler capital expenditure, product supply schedules, and gross margins.
When substantial growth expectations are already embedded in the valuation, even limited uncertainty can generate significant volatility.
If chief executive risk emerges, investors may price in governance discounts and regulatory costs before any measurable effect appears in earnings.
Conversely, the shares could recover rapidly if an official investigation finds that the allegations are unfounded or operationally immaterial.
Investment decisions based solely on unverified rumors carry significant risk.
10. Transmission Channels to the KOSPI and Korean Markets
The source links a KOSPI decline to the controversy, but a single-factor explanation is insufficient.
Korean markets are simultaneously influenced by exchange rates, foreign investor flows, U.S. interest rates, China’s economy, and domestic corporate earnings.
If uncertainty surrounding Nvidia develops into an operational risk, it could affect Korean equities through the following channels:
- Downward revisions to Nvidia GPU shipment forecasts
- Adjustments to HBM and server-memory orders
- Lower earnings expectations for semiconductor equipment and materials companies
- Reduced foreign investor exposure to AI semiconductor shares
- Lower earnings forecasts for major KOSPI companies
If AI data center investment continues but shifts geographically, the actual earnings impact on Korean memory producers may remain limited.
11. Key Issues Often Overlooked in Other Coverage
First, the primary risk is not Jensen Huang personally but the financing structure surrounding Nvidia-centered AI infrastructure.
If AI data centers have expanded rapidly through debt and long-term contracts, declining GPU rental rates could amplify financial risk.
Second, export controls may initially reduce transaction velocity rather than final sales volumes.
Stricter end-user reviews and licensing procedures could delay revenue recognition even without contract cancellations.
Third, Nvidia’s most important asset is not the GPU alone but its trust-based ecosystem.
Developers, cloud providers, governments, and investors must maintain confidence in Nvidia’s technology roadmap for large-scale investment to continue.
Fourth, aggregate AI accelerator production is more important to HBM suppliers than China-specific revenue.
Even if regional restrictions tighten, memory demand may shift to other markets if global data center investment remains intact.
Fifth, the spread of rumors can itself provide political justification for stronger regulation.
Even if the allegations are ultimately disproven, policymakers could use the controversy to intensify supply-chain security reviews and enforcement against indirect exports.
12. Monitoring Checklist
- Official statements or securities filings from Nvidia and its board
- Changes to export licensing policies by the U.S. Department of Commerce’s Bureau of Industry and Security
- Official congressional investigation letters and hearing schedules
- Sanctions or enforcement lists concerning indirect exports through Singapore and other third countries
- Changes in Nvidia’s China revenue and regional data center sales
- Debt levels and cash flow at CoreWeave and other neocloud providers
- AI capital expenditure guidance from major technology companies
- HBM shipment forecasts from SK hynix, Samsung Electronics, and Micron
- Nvidia’s succession planning and board independence
13. Final Assessment in the Global Economic Outlook
A literal interpretation of the source would suggest that a personal scandal could destabilize the global AI industry.
A more credible global economic outlook requires separating the factual status of the allegations from their potential business consequences.
Without official confirmation, the matter may remain a reputational risk rather than an operational one.
It could become a structural risk if it results in revoked export licenses, a formal board investigation, leadership disruption, or financing stress among neocloud providers.
The appropriate basis for assessment is official documentation, cash flow, GPU shipment data, and policy changes rather than unverified claims.
The AI industry’s critical constraints extend beyond capital and GPU availability.
Power supply, data center sites, advanced packaging, HBM capacity, networking infrastructure, and regulatory approvals are interdependent.
Disruption in one area may cause short-term volatility, but it would not necessarily lead to the collapse of the broader ecosystem.
< Summary >
Claims that Jensen Huang admitted to an affair or had links to an alleged spy cannot be treated as established facts without official supporting evidence.
However, Nvidia’s key-person exposure, neocloud leverage, enforcement against indirect exports to China, and AI semiconductor regulation are material risks that warrant monitoring.
Stricter GPU controls could affect HBM suppliers and Korean semiconductor companies, although demand may shift to other regions if global data center investment remains resilient.
Investment decisions should be based on Nvidia’s official filings, U.S. government documents, GPU shipment volumes, neocloud cash flow, and HBM supply agreements rather than market rumors.
[Related Articles…]
- Nvidia AI Chips and Data Center Investment Outlook
- HBM Market and Korean Memory Semiconductor Growth Strategy
*Source: [ 내일은 투자왕 – 김단테 ]
– 젠슨황 스캔들 더 큰 문제인 이유
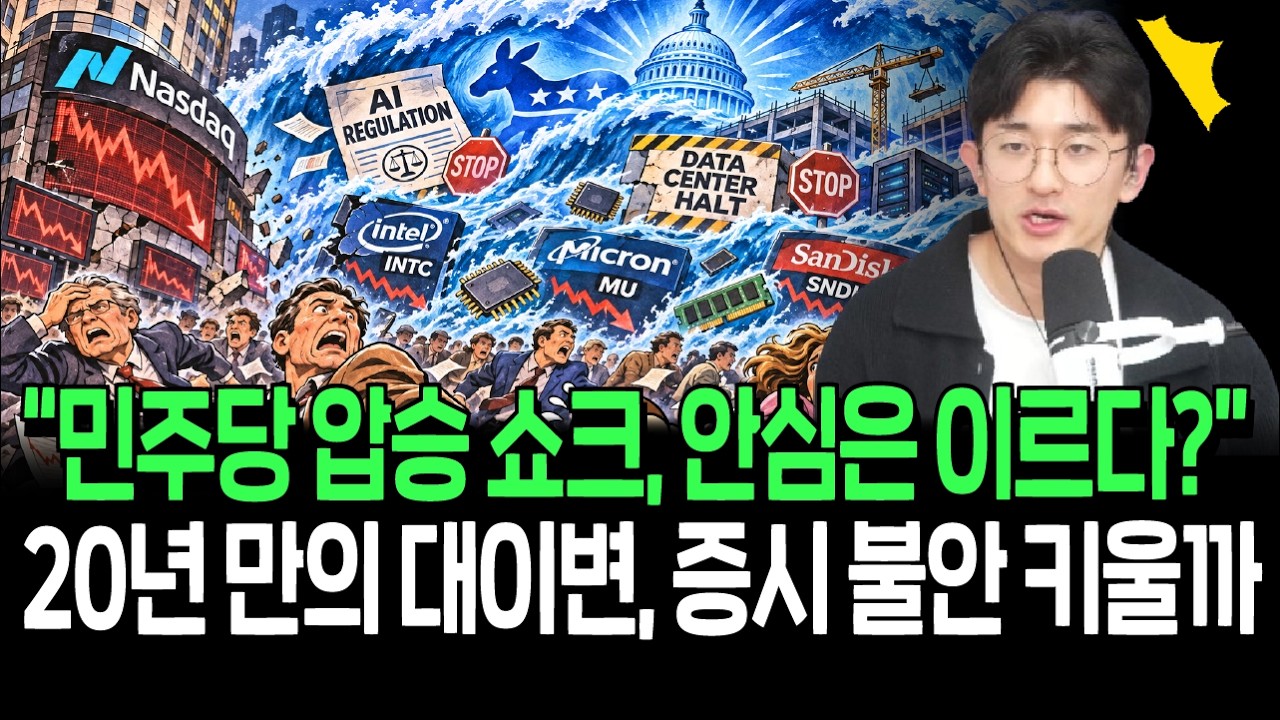
● AI Data Center Panic, Nasdaq Shock, Chip Rout
Wall Street Panic After a Democratic Sweep: Why AI Data Center Regulation Could Disrupt the Nasdaq and Semiconductor Markets
The key issue behind the market shock is not simply a Democratic election victory.
The central concern is that changes in state and local political leadership could affect AI data center approvals, semiconductor demand, power-grid investment, data center financing, and Big Tech capital expenditure.
This report examines the original source’s explanation for the Nasdaq selloff, regulatory risks facing AI data centers, potential divergence between semiconductor stocks and Big Tech, early warning signals in credit markets, and key developments to monitor.
However, some index movements, election results, IPO schedules, political statements, and allegations involving individuals have not been independently verified through official sources or multiple credible reports.
The following should therefore be viewed as a market scenario and risk assessment rather than a confirmed breaking-news report.
1. Immediate Drivers of the Market Shock
The original source states that the Nasdaq 100 fell 6.4% in one session, while the semiconductor index declined 12.3%.
On a weekly basis, the Nasdaq reportedly fell 5% and the semiconductor index 13%, extending their respective losing streaks to four and five weeks.
It also claims that the year-to-date return of a semiconductor-related ETF declined from more than 100% at its peak to approximately 36%.
Investors who entered at the beginning of the year may remain profitable, while those who purchased during the later stages of the rally could face substantial losses.
The selloff may reflect more than profit-taking. Under the source’s scenario, stronger-than-expected Democratic results in congressional and gubernatorial elections prompted markets to price in tighter AI data center regulation.
The reported index movements and election outcomes require confirmation through exchanges, election authorities, and state government records.
2. Why Gubernatorial Authority Matters More Than the Democratic Victory Itself
Investors often focus on congressional control, but governors and local governments can have a more direct influence on AI data center development.
Projects require approvals related to land use, construction, environmental reviews, electricity supply, grid interconnection, water consumption, and tax incentives.
Even if the federal government promotes AI investment, project schedules can be delayed by state agencies, counties, municipalities, public utility commissions, and power companies.
The original source claims that Democratic governors were elected in eight of the ten largest US data center development regions.
It also estimates that key politically competitive regions represent approximately 41% of planned US data center computing capacity.
If accurate, the market may be responding to a potential slowdown in AI data center expansion rather than to a simple change in political control.
However, approval authority is not concentrated solely in governors. Estimating project cancellations based only on election results would overlook the roles of state legislatures, local governments, utility commissions, power companies, and environmental regulators.
3. Why Texas Is Considered the Most Sensitive Region
Texas is presented as the most significant case in the original source.
Its available land, relatively low electricity costs, business-friendly regulation, and substantial generation capacity have attracted AI data centers and advanced manufacturing investment.
The source estimates that Texas accounts for approximately 30% of US data center computing capacity planned through 2028.
A political shift or temporary suspension of new data center approvals in such a region could materially affect market expectations.
However, strong campaign statements do not necessarily translate directly into policy.
Data centers can pressure local electricity and water systems, but they also generate construction activity, tax revenue, employment, and infrastructure investment.
The eventual outcome may involve conditional approvals requiring developers to fund grid upgrades, secure dedicated generation, limit water use, or compensate local communities rather than a comprehensive moratorium.
4. Why Local Communities May Support Data Center Regulation
The strategic importance of AI does not eliminate concerns about local living costs.
Large data centers require substantial electricity and water consumption and may require additional generation and transmission infrastructure.
Residents may oppose projects if households are expected to bear part of the infrastructure cost through higher utility rates.
Other concerns include noise, emissions from backup generators, increased traffic, rising land prices, and water scarcity.
The original source states that most local referendums related to data centers favored tighter regulation.
Although the figures require verification, political opposition to data centers could increasingly reflect local affordability and infrastructure concerns rather than partisan conflict alone.
5. Impact of Data Center Delays on Semiconductor Stocks
AI semiconductor demand assumes that data centers will be completed on schedule and that servers will be installed as planned.
Delays in power interconnection or construction approvals could leave insufficient operating capacity for GPUs, memory, servers, and networking equipment already in production.
Even without order cancellations, deferred deliveries could increase inventory and working-capital requirements across the supply chain.
As a result, relatively modest construction delays could affect earnings estimates throughout the AI infrastructure sector.
-
GPUs and AI accelerators: Delayed facility openings could postpone deliveries and revenue recognition.
-
HBM and memory: Slower demand growth could reduce expectations for pricing and margins.
-
Semiconductor equipment: Customers may defer equipment orders if capacity expansion plans become more conservative.
-
Server manufacturers: Delayed customer acceptance after substantial upfront investment could increase inventory and financing costs.
-
Optical and networking equipment: Orders could become more volatile as data center cluster construction slows.
-
Power and cooling equipment: Long-term demand may remain intact, but short-term project delays could affect revenue timing.
The correction could therefore represent a broader valuation reassessment across the AI infrastructure supply chain rather than a deterioration in the competitive position of any single company.
6. Why the Impact Could Be Positive for Big Tech
Some large cloud companies could outperform even as AI infrastructure suppliers decline.
A slower pace of data center construction could reduce capital expenditure pressure for Microsoft, Alphabet, Amazon, and Meta.
Investors are increasingly evaluating not only AI capabilities but also the timing and scale of returns on infrastructure spending.
Reduced pressure to expand capacity aggressively could support free cash flow at large technology companies.
Data center operators and equipment suppliers, however, would be more directly exposed to lower investment volumes.
The market could therefore become increasingly divided between cash-rich technology platforms and highly leveraged infrastructure companies.
7. Has Corporate AI Cost Reduction Already Begun?
The original source states that some companies are reducing employee usage allowances for generative AI services.
This would indicate a transition from broad adoption toward a more disciplined assessment of productivity gains and operating costs.
If companies shift from external AI services toward internal models and proprietary tools, usage-fee growth at providers such as OpenAI and Anthropic could slow.
Cloud companies may also review new data center agreements or favor internally developed facilities over third-party operators.
These developments would not necessarily indicate declining AI demand. They would suggest that the industry is moving from unrestricted expansion toward return-on-investment and cost-efficiency analysis.
8. Credit Risk May Provide an Earlier Warning Than Equities
One of the most important but less widely discussed risks is the credit exposure of data center companies.
Data center projects require substantial upfront spending on land, buildings, power access, cooling systems, servers, and networking equipment.
Highly leveraged companies must continue servicing debt even when project delays postpone revenue generation.
This creates simultaneous pressure on profitability, liquidity, and cash flow.
The original source claims that credit-risk indicators have risen for companies with significant AI infrastructure exposure, including CoreWeave, Oracle, SoftBank, and Broadcom.
It also refers to a European financial institution attempting to sell approximately $500 million of data center loans.
These claims require verification. However, bank efforts to sell or distribute data center credit exposure could become an early warning signal ahead of equity-market stress.
Investors should monitor corporate bond yields, credit default swap spreads, loan-sale discounts, debt maturities, and interest coverage ratios.
9. Why Microsoft’s Contract Reviews Matter
The original source states that Microsoft is reviewing certain contracts and renewal decisions involving third-party data center operators.
If an operator cannot secure electricity and complete facilities on schedule, cloud service expansion may be disrupted.
Microsoft could respond by terminating agreements or developing facilities directly.
The primary risk is that third-party operators may have borrowed heavily against anticipated long-term contracts with major cloud providers.
Contract reductions or non-renewals could weaken both revenue visibility and debt-servicing capacity.
Future earnings reviews should therefore emphasize contracted backlog, customer concentration, secured power capacity, and expected commissioning dates rather than revenue growth alone.
10. Anthropic’s Valuation and Potential IPO
The original source claims that Anthropic is preparing for an initial public offering and may need to accept a lower valuation due to weaker market conditions.
Any specific IPO schedule or valuation exceeding $1 trillion should be verified through official announcements.
A major AI IPO could have two opposing market effects.
A successful offering would indicate continued investor demand for AI assets and support private-market valuations.
A substantial valuation reduction or weak institutional demand could reset valuation benchmarks across the AI sector.
A large offering could also divert liquidity from existing semiconductor and technology stocks.
11. Bullish Arguments for a Rebound
A more constructive view interprets the selloff as an excessive reaction to political rhetoric.
The United States is unlikely to halt data center and semiconductor investment while competing with China for AI leadership.
Data centers also contribute to economic growth, construction spending, manufacturing employment, and power infrastructure investment.
Both major political parties recognize the strategic importance of AI, increasing the probability of a compromise between regulation and industrial development rather than a comprehensive prohibition.
Elevated volatility, a sharp rise in fear indicators, forced hedge-fund liquidation, and heavy retail demand for inverse products could support a short-term technical rebound.
Historically, periods of extreme market fear have sometimes been followed by stronger six- to twelve-month returns, although outcomes vary.
12. Bearish Arguments for Further Declines
The cautious view is that uncertainty may increase rather than decline after the election.
Markets typically respond positively when election outcomes reduce uncertainty regardless of the winning party.
However, if political control changes in regions responsible for data center approvals, the election could mark the beginning of a new period of policy uncertainty.
Until incoming state governments and legislatures announce specific policies, investors may be unable to quantify the scale of project delays.
Data center development could also become a major political issue in the 2028 US presidential election.
Electricity prices, water shortages, and household costs are highly visible issues for voters and may sustain political pressure.
A short-term oversold rebound is possible, but a durable trend reversal may require greater clarity on regulation and Big Tech capital expenditure.
13. Could the AI Correction Spread to the Broader US Economy?
The correction currently appears concentrated in AI infrastructure and semiconductors, but the principal risk is broader sector contagion.
If AI-related capital expenditure has contributed materially to recent US economic growth and equity-market gains, slower data center investment could affect GDP and corporate earnings expectations.
Reduced wealth among AI-sector employees and shareholders could also weaken high-end consumer and service spending.
Conversely, if earnings outside the AI sector remain resilient and interest rates stabilize, the Dow, dividend stocks, consumer staples, and healthcare could outperform.
Investors should distinguish between an internal market rotation and the beginning of a broader US economic slowdown.
14. Potential Sector Winners and Losers
AI infrastructure and semiconductors: These sectors face the most direct pressure from delayed approvals and reduced capital expenditure expectations.
Large cloud companies: Lower capital expenditure requirements could provide relative support to free cash flow.
Renewable energy and solar: Expectations for Democratic subsidies and environmental policies could support sentiment, but actual budget approval remains critical.
Healthcare and health insurance: Expectations for expanded public healthcare spending may increase, although implementation could take considerable time.
Retail and consumer goods: Reduced tariffs and increased support for lower-income households could benefit Walmart, Costco, dollar stores, and payment companies if implemented.
Dividend and rate-sensitive stocks: Their relative appeal could increase if economic uncertainty lowers market interest rates.
Defense and traditional energy: Policy changes and expectations regarding geopolitical conflicts could increase short-term volatility.
Political theme stocks: Election-driven gains may not be sustainable without supporting earnings.
15. Key Issues Often Overlooked in Market Coverage
First, the primary bottleneck may be grid interconnection rather than semiconductor supply.
Even with sufficient GPUs, data centers cannot operate without substations, transmission capacity, and power-generation access.
Second, the central regulatory question may be cost allocation rather than an outright ban.
Project economics will depend on how much developers must pay for generation and transmission upgrades.
Third, credit markets could deteriorate before equity markets.
For highly leveraged data center companies, rising financing costs and contract cancellations may be more damaging than share-price declines.
Fourth, polarization within the AI industry could intensify.
Cash-rich technology platforms may remain resilient, while infrastructure companies dependent on external financing and long-term contracts face greater pressure.
Fifth, earnings and liquidity remain more important than political affiliation.
Long-term returns cannot be reliably forecast solely from election results.
Policy developments can influence short-term market direction, but long-term valuations are more likely to reflect revenue, cash flow, interest rates, and market liquidity.
16. Market Monitoring Checklist
-
Confirm whether state and local governments formally suspend data center approvals.
-
Monitor whether political statements develop into legislation or executive orders.
-
Determine whether Microsoft and other major cloud companies cancel data center contracts.
-
Review contracted backlog, debt levels, and secured power capacity at CoreWeave and other data center operators.
-
Monitor semiconductor companies for references to order cancellations or deferred deliveries.
-
Assess valuations in AI-sector IPOs and private funding rounds.
-
Track US inflation data and Treasury yields for additional pressure on technology valuations.
-
Determine whether semiconductor weakness spreads to the S&P 500, Dow, and consumer sectors.
-
Monitor corporate credit spreads and secondary-market activity in data center loans.
17. Investor Positioning
Investors may benefit from separating long-term allocation accounts from short-term trading accounts.
Long-duration retirement or education accounts may continue using disciplined, incremental purchases rather than attempting to identify the precise market bottom.
Short-term accounts with limited liquidity may require confirmation that the downtrend has stabilized and earnings expectations have stopped declining.
A stock is not necessarily undervalued solely because it has fallen 50% from its peak.
If project approvals, power access, debt maturities, and major customer contracts deteriorate simultaneously, the appropriate valuation framework may change materially.
Conversely, if political rhetoric does not affect orders or earnings, excessive price declines could create long-term opportunities.
Corporate balance sheets, liquidity, and cash-flow quality should take priority over headline price movements.
This report is provided for informational purposes and does not constitute a recommendation to buy or sell any security.
< Summary >
The original source attributes the Nasdaq and semiconductor selloff to an unexpected Democratic election victory and changes in gubernatorial leadership that increased concerns about AI data center regulation.
The principal risk is that construction delays could postpone revenue recognition for GPUs, memory, servers, optical equipment, and power infrastructure.
Big Tech companies could benefit relatively from lower capital expenditure pressure, while highly leveraged data center operators may face increased credit risk.
An oversold rebound remains possible, but confirmation of regulatory policy, grid interconnection schedules, cloud contracts, and AI-sector financing conditions is required before concluding that the market trend has reversed.
Earnings, cash flow, credit spreads, and market liquidity remain more important than political statements.
[Related Articles…]
*Source: [ 소수몽키 ]
– 미국 민주당 20년 만의 압승에 월가도 패닉? 추가 충격에 대비해야 할까