● Tax Bomb – Pay Without Selling
Capital Gains Tax on Foreign Shares Without a Market Sale: A Petition at 90% of Its Target and Key Tax-Deferral Issues
Corporate mergers and share exchanges can create tax liabilities even when investors have not sold shares for cash.
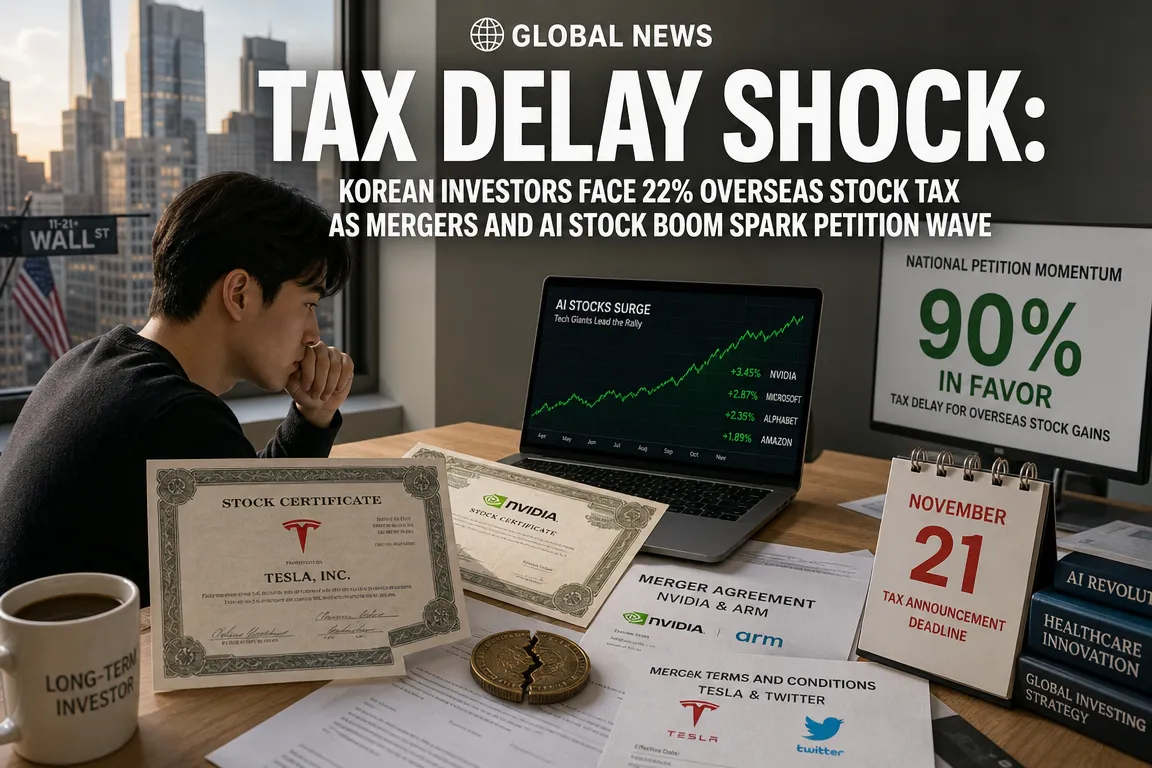
A National Assembly public consent petition seeks to defer capital gains taxation on certain foreign-share restructuring transactions until investors sell the replacement shares.
This report examines the significance of the petition reaching 90% of its consent target, the transactions that can trigger tax liabilities, and the conditions required for an effective tax-deferral framework.
The stated petition deadline is November 21, but the year and official petition URL are unavailable. Its current status and real-time consent count remain unverified.
The references to “five days remaining” and “90% of the target” describe the reported situation at the time, not current figures.
1. Core Request: Deferral Until Sale, Not Tax Exemption
The petition seeks a change in the timing of taxation.
Where a merger or share exchange involving foreign shares triggers capital gains tax, the petition requests deferral until the replacement shares are sold.
- Relevant transactions: Mergers or share exchanges that replace existing holdings with shares in another company.
- Investor concern: A tax liability may arise without sufficient cash proceeds to fund payment.
- Requested measure: A framework deferring taxation on qualifying transactions until the shares are sold.
- Key distinction: Tax exemption eliminates taxation; tax deferral postpones it.
Investors may regard their exposure as continuous because they still hold shares after the transaction.
Tax treatment, however, depends not only on whether an investor placed a sell order, but also on whether the original shares were transferred for consideration or exchanged for another asset.
This distinction underlies the debate over capital gains taxation on foreign shares.
2. Consent Count of 45,015: Progress Toward the 50,000 Target
The reported headline figure was 45,015 consents, approximately 90% of the target.
The accompanying transcript contained an unclear figure, so the calculations below use the explicitly stated headline count.
| Item | Reported Information |
|---|---|
| Petition deadline | November 21; year unspecified |
| Consent count | 45,015 |
| Stated target | 50,000 |
| Target completion | Approximately 90.03% |
| Additional consents required | 4,985 |
| Average daily consents required with five days remaining | 997 |
The statement that approximately 1,000 additional consents per day would achieve the target is consistent with these calculations.
A reported increase of 4,680 consents on the preceding day has not been independently verified against official records.
The official National Assembly petition page, rather than recirculated video figures, should be used to confirm the current consent count and closing time.
3. Does Reaching 50,000 Consents Automatically Change the Law?
Meeting the consent threshold and amending tax legislation are separate stages.
A petition that satisfies the applicable requirements may proceed to review by the relevant National Assembly committee.
This does not constitute automatic acceptance or immediate tax relief.
- Consent threshold: The petition secures the required number of consents within the prescribed period.
- Parliamentary review: The relevant committee examines the petition and the need for policy changes.
- Policy development: Discussions address whether legislation is required and how eligibility and qualifying conditions should be defined.
- Legislation and implementation: Any necessary statutory amendment requires a separate legislative process and an effective date.
Reaching 50,000 consents does not remove an investor’s tax obligations.
The petition seeks formal parliamentary consideration of taxation arising from share exchanges without cash proceeds.
Existing filing and payment obligations remain in force while a petition is pending or after it meets its target.
4. Why Capital Gains Tax Can Arise Without a Market Sale
A conventional foreign-share investment involves purchasing shares and later selling them in the market to realize a gain.
In a merger or share exchange, however, the legal form of the holding can change without an investor submitting a sell order.
For example, shares in Company A may be exchanged for shares in Company B during a merger.
Although the investor still holds shares, the tax question may be whether the Company A shares were transferred in exchange for Company B shares.
Continued investment exposure does not necessarily mean that no taxable disposal has occurred.
However, not all mergers or exchanges involving foreign shares receive the same tax treatment.
The applicable treatment requires transaction-specific analysis under the relevant legislation.
- Determine how the original shares are cancelled or transferred.
- Identify whether the consideration consists solely of shares or includes cash.
- Confirm how the replacement shares are valued and how the transaction date is determined.
- Review the investor’s tax residency and any applicable relief provisions.
- Assess foreign and Korean tax treatment separately.
A foreign company’s description of a transaction as a “tax-free exchange” for local investors does not establish equivalent treatment for Korean tax residents.
5. The Central Investor Issue: Liquidity Rather Than Gains Alone
The principal economic issue is the mismatch between gains measured for tax purposes and cash available to pay the resulting liability.
Assume shares purchased for KRW 10 million are exchanged for replacement shares valued at KRW 20 million in a corporate restructuring.
If the transaction is treated as a taxable disposal, a liability may arise without cash proceeds. The amount would depend on the applicable rules and deductions.
Without other funding, the investor may need to sell some replacement shares to pay the tax.
- Portfolio disruption: A partial sale may become necessary despite a long-term holding strategy.
- Price risk: A decline after the tax valuation date may increase the difficulty of funding payment.
- Trading restrictions: Delays in share delivery or trading availability may constrain liquidity.
- Foreign-exchange exposure: Exchange rates affect both gains measured in Korean won and the cost of obtaining payment funds.
Investment risk therefore extends beyond falling share prices.
Misalignment among restructuring dates, tax recognition and trading availability can create material liquidity risk.
6. Why the Issue Extends Beyond Tesla Shareholders
Tesla is mentioned in the material, but no specific Tesla merger or share-exchange plan is established.
The reference is best understood as outreach to foreign-share investors, including Tesla shareholders.
The issue concerns the tax framework for Korean investors affected by overseas corporate restructurings, rather than the price outlook for a particular stock.
Investors holding U.S. or other foreign shares should review the applicable rules if a similar transaction affects their holdings.
This does not imply that all foreign-share investors currently face such a liability.
Investors in AI and advanced technology should review acquisition disclosures and the form of shareholder consideration alongside growth prospects.
Cash acquisitions, share exchanges and mixed-consideration transactions can produce different liquidity outcomes and tax-review requirements.
7. Policy Design: “Taxation Upon Sale” Is Not Sufficient
The operating rules of a potential framework are as important as the petition’s consent count.
Effective investor protection requires the following design elements.
① How will the tax basis carry over to replacement shares?
Deferral must preserve accurate capital gains calculations when the replacement shares are eventually sold.
Unclear treatment of the original acquisition cost and deferred gain could result in omitted gains or double counting.
A carryover-basis mechanism, or equivalent rules for tracking deferred gains or tax, is therefore essential.
② How will transactions involving both shares and cash be treated?
Share-only exchanges and transactions with partial cash consideration have different liquidity implications.
The framework must specify whether, and to what extent, cash consideration triggers immediate taxation.
③ How will deferred gains be allocated when only part of the holding is sold?
Investors may sell replacement shares in stages rather than all at once.
Calculation rules must accommodate partial sales, additional purchases and successive restructurings.
④ Will tax records transfer between brokerages?
Deferral requires reliable brokerage systems and recordkeeping, not legislation alone.
If acquisition costs, exchange ratios and deferral records cannot be verified after an account transfer, investors may bear a disproportionate compliance burden.
⑤ Will the framework cover past transactions?
Whether relief applies only to transactions after implementation or also to earlier transactions is a separate policy decision.
Neither petition approval nor a legislative amendment should be assumed to generate automatic refunds of previously paid tax.
The issue therefore extends beyond changing the timing of taxation.
It also concerns the ability of domestic financial institutions to track overseas restructuring data accurately and communicate it to investors.
8. Current Checklist for Foreign-Share Investors
- Official petition information: Confirm the title, public consent period, consent count and processing status on the National Assembly petition platform.
- Transaction structure: Review company disclosures for the merger structure and the terms of share and cash consideration.
- Brokerage guidance: Confirm the exchange date, expected delivery date, first trading date and tax-basis treatment.
- Tax review: Consult a brokerage tax-support service or qualified tax adviser about Korean capital gains tax treatment and filing requirements.
- Record retention: Keep purchase records, corporate disclosures, share-exchange records and details of cash received.
- Payment planning: Where taxation is possible, assess trading availability alongside the payment schedule.
The material refers to a petition link in a pinned comment, but the link was not supplied.
Verify the official petition before treating similarly titled posts or older participation notices as current.
< Summary >
- The petition seeks to defer capital gains taxation arising from foreign-share mergers and exchanges until the replacement shares are sold.
- The reported headline count was 45,015 consents, leaving 4,985 to reach the 50,000 target.
- The year of the November 21 deadline and the petition’s current status remain unverified.
- Meeting the consent threshold does not immediately amend tax law or suspend payment obligations.
- The central issue is taxation without cash proceeds. An effective framework requires rules covering tax basis, partial disposals, cash consideration and effective dates.
[Related Articles…]
*Source: [ 오늘의 테슬라 뉴스 ]
– 청원 마감 5일, 지금 90% 5만 명 넘을까?
● Druckenmiller Dumps Chips – Bets Big on AI Cash Machines
Druckenmiller Cuts Semiconductor Exposure and Raises Unity Holdings by 436%? What Matters in AI Investing
The central issue is not semiconductor divestment, but which companies can generate sustainable cash flow from AI.
Unity’s AI advertising, Seagate’s data storage, and Natera’s precision diagnostics illustrate three areas of potential investment opportunity.
However, the reported 436% increase in Unity holdings, 32% allocation to Natera, and Fox acquisition of Roku warrant different levels of scrutiny.
The following analysis separates reported portfolio changes, company-specific investment rationales, and risks that require verification.
1. What Reportedly Changed in Druckenmiller’s Portfolio?
The source describes reduced semiconductor exposure and increased allocations to diagnostics, data storage, cloud computing, and advertising companies in Stanley Druckenmiller’s portfolio.
This could indicate a broader focus on companies that convert AI infrastructure into revenue and cash flow, rather than infrastructure growth alone.
Trading disclosures, however, do not establish an investor’s precise intentions.
| Company | Reported Change | Investment Rationale to Assess |
|---|---|---|
| Natera (NTRA) | Largest holding; approximately 32% allocation | Expansion of precision diagnostics, including cancer monitoring |
| Seagate (STX) | Second-largest holding; approximately 180% increase cited | Data center storage demand and HDD supply dynamics |
| Amazon (AMZN) | Third-largest holding | Diversified earnings from AWS, e-commerce, and advertising |
| Fox (FOX·FOXA) | Fourth-largest holding | Live sports, news, and streaming operations |
| Insmed (INSM) | Fifth-largest holding | Valuation changes driven by drug development and commercialization |
| Unity (U) | Sixth-largest holding; approximately 436% increase cited | Improved mobile advertising performance through AI |
| AppLovin (APP) | A smaller position than Unity cited | Advertising optimization and monetization capabilities |
The reported 436% increase in Unity holdings requires a precise definition.
If the share count increased by 436% from the previous quarter, the resulting holding would be 5.36 times its previous size.
If the figure instead refers to market value or portfolio weight, it may also reflect share-price appreciation or reductions in other positions.
Changes in share count, market value, and portfolio weight should not be treated interchangeably.
2. Form 13F Limitations: Neither a Current Portfolio nor a Complete Asset Record
The scope and timing of Form 13F disclosures matter more than individual holdings when assessing prominent investors’ portfolios.
- Reporting lag: Filings are generally due within 45 days after quarter-end and disclose holdings as of that quarter-end.
- Incomplete asset coverage: Cash, many foreign assets, short positions, and various derivatives are not comprehensively represented.
- No transaction timing: Filings do not disclose when positions were purchased or sold during the quarter, or at what prices.
- Uncertain current ownership: Positions may have changed substantially since the reporting date.
The source’s description of the information as “at least 45 days old” is inaccurate.
The 45-day period is the general filing deadline; earlier filings can have a shorter reporting lag.
Even if Natera represented 32% of reported holdings, that would not necessarily mean 32% of Druckenmiller’s total wealth or assets under management.
The denominator must be verified, particularly whether it represents the market value of securities reported on Form 13F.
The disappearance of a TSMC position alone does not establish that the semiconductor cycle has ended.
Potential explanations include profit-taking, valuation concerns, geopolitical risks, and more attractive alternatives.
3. Natera: Test Volumes, Reimbursement, and Clinical Evidence Matter More Than the AI Label
Natera provides genetic testing and monitoring services in precision diagnostics.
The source identifies three principal business areas.
- Prenatal screening: Maternal blood testing assesses the risk of certain fetal chromosomal abnormalities.
- Cancer monitoring: Signatera analyzes circulating tumor DNA to help assess molecular residual disease and recurrence risk.
- Transplant monitoring: Analysis of donor-derived DNA in blood helps assess the risk of transplanted-organ injury or rejection.
Prenatal screening does not identify all fetal health conditions or provide definitive diagnoses.
Cancer monitoring results alone cannot confirm or exclude every recurrence.
The investment rationale centers on recurring demand for medical services.
Post-treatment surveillance and transplant monitoring can support repeated testing, with growth dependent on physician adoption and reimbursement coverage.
The broader potential of AI in diagnostics is distinct from evidence that AI directly drives Natera’s revenue growth.
The cited 2026 Druckenmiller interview and attributed investment intentions should not be treated as established evidence without reviewing the original material.
Key Operating and Financial Metrics
- Total test volumes and the number of tests recognized as revenue.
- Realized revenue per test and reimbursement levels.
- Processing costs, gross margins, and cash burn.
- Clinical study results and inclusion in medical guidelines.
- Clinical utility relative to competing tests and adoption in medical practice.
For Natera, the conversion of clinical value into reimbursement and cash receipts matters more than classification as an AI healthcare beneficiary.
4. Seagate: Assessing the Case for Storage After GPUs
Seagate supplies data storage solutions, primarily high-capacity hard disk drives, or HDDs.
AI data centers require storage for training data, backups, and outputs, alongside computing hardware.
Not all data, however, is stored on HDDs.
SSDs are better suited to applications requiring rapid access, while HDDs remain competitive in cost-efficient, high-capacity storage.
The source emphasizes industry supply structure.
The HDD market is concentrated among a small number of suppliers, including Seagate, Western Digital, and Toshiba.
High-density recording technology, head and media manufacturing capabilities, and customer qualification processes create barriers to entry.
Technologies such as Seagate’s HAMR can improve storage density and cost per terabyte.
Market concentration does not eliminate price competition or oversupply.
Cloud customer purchasing pauses, inventory adjustments, and transitions to higher-capacity products can materially affect performance.
Toshiba’s ownership structure alone does not justify assuming limited competitive aggression.
The source’s capital expenditure comparison requires particular caution.
The cited capital expenditure-to-revenue ratios of approximately 5% for Seagate and 20% for Micron require verification of the reporting periods and calculation methods.
The reference to “Q3 2026” also requires clarification of whether it denotes a fiscal or calendar quarter.
HDD and memory semiconductor manufacturers have different production processes and capital requirements, limiting the usefulness of a simple ratio comparison.
Lower capital expenditure does not inherently reduce the impact of a 5-percentage-point decline in operating margin.
Free cash flow analysis must also account for pricing, sales volumes, costs, working capital, and interest expense.
The reported decline in NAND spot prices and strength in HDD prices also require contemporaneous pricing data.
NAND spot prices, enterprise SSD contract prices, and high-capacity HDD contract prices measure different markets.
5. Amazon: Multiple AI Revenue Channels Do Not Mean Investment Is Complete
Amazon offers several potential channels for monetizing AI.
- AWS: Provides computing infrastructure and related services for enterprise AI development and deployment.
- E-commerce: AI can improve recommendations, inventory management, and logistics efficiency.
- Advertising: Shopping data that captures purchase intent can support better advertising performance.
The proposition that greater AI usage automatically increases Amazon’s revenue is conditional.
Amazon must secure customer demand, offer competitive pricing and performance, and utilize infrastructure effectively.
The source’s claim that Amazon has largely completed its capital investment is not a reliable investment premise.
AI data centers require ongoing spending on server replacement, power supply, cooling, and network expansion.
When capital spending precedes revenue and earnings, growth can coincide with near-term cash flow pressure.
It is also excessive to assume that AI poses no competitive risk to e-commerce.
AI shopping agents could alter customer acquisition channels and advertising exposure by taking over product searches and comparisons.
Amazon may benefit from these changes, but investors should also assess disruption to established purchasing behavior.
6. Fox and Insmed: Portfolio Positions That AI Alone Does Not Explain
Fox owns differentiated content assets in live sports and news.
Content with high real-time viewing value has consumption patterns distinct from conventional on-demand video.
Rising sports rights costs and declining pay-TV subscriptions remain separate financial pressures.
The source’s claim that “Fox acquired Roku” should not be presented as fact without confirmation from official announcements.
Fox’s established streaming operations include the free, advertising-supported service Tubi.
Roku is a separate streaming platform company; acquisitions must be distinguished from partnerships and content distribution agreements.
The supplied material does not substantiate the acquisition, so it is excluded from the investment rationale.
Insmed requires a separate biotechnology investment framework.
The source identifies its portfolio ranking but provides no specific purchase rationale.
Relevant factors include clinical results, regulatory approvals, commercial sales growth, cash reserves, and potential financing requirements.
Grouping Natera and Insmed together as “AI healthcare” risks obscuring their distinct business risks.
7. Unity: Is AI Advertising Monetization More Important Than the Game Engine?
Unity is widely known for its engine for developing games and real-time 3D content.
Investment analysis should distinguish Create, focused on development tools, from Grow, focused on advertising and monetization.
- Create: Tools and services supporting game and content development.
- Grow: Advertising services supporting user acquisition and app and game monetization.
The source places greater emphasis on a recovery in advertising growth than on development tools.
Its principal focus is Vector, Unity’s AI-based advertising model.
AI advertising involves more than preference-based recommendations.
Advertising systems estimate the likelihood that users will click an advertisement, install a game, make purchases, or remain active over time.
These predictions inform ad delivery and bidding.
The objective is not necessarily the lowest acquisition cost, but an appropriate cost relative to expected user value.
Acquiring more users with a higher likelihood of making purchases at the same advertising budget can improve advertiser profitability.
Verified performance gains may encourage advertisers to increase spending, creating additional revenue opportunities for the platform.
A key advantage of advertising technology is that AI performance can be measured relatively quickly through return on advertising spend, or ROAS.
The growth rates cited in the source are not directly comparable without additional context.
Figures such as 35–43% and 52% must be identified as total revenue growth, Grow revenue growth, or growth in a particular advertising product.
Reported results must also be distinguished from management guidance.
If business reductions or changes in revenue measurement alter the comparison base, higher reported growth may not represent equivalent underlying expansion.
8. Unity’s “Proprietary Data” May Be an Asset, but Does Not Automatically Establish a Competitive Advantage
The source identifies runtime data generated through Unity’s engine as a potential source of advertising strength.
The rationale is plausible, but supplying an engine does not imply unrestricted access to, or advertising use of, all user data.
- Data collection: Identify which data is actually collected.
- Usage rights: Assess developer and user consent and contractual restrictions.
- Platform policies: Consider Apple and Google privacy and tracking requirements.
- Performance contribution: Establish how much the data improves advertising predictions.
Recommending urban-themed games to users who prefer urban environments illustrates the concept.
It does not establish that such detailed information is collected or used for advertising targeting.
The claim that “70% of mobile games use Unity” requires clarification of the survey date, sample, and whether it covers all games or leading titles.
Engine market share does not translate directly into advertising market share.
Comparisons with AppLovin require more than an assessment of data categories.
AppLovin can obtain advertising impressions, engagement, conversion data, and other signals through its advertising network and monetization platform.
The absence of a game engine does not by itself imply weaker data capabilities.
Competitive outcomes depend on advertiser performance, developer revenue, advertising supply, predictive model quality, and cost efficiency.
9. Additional Analysis: Five Factors Often Overlooked in Stock Summaries
The following factors can be more relevant to investment decisions than headline purchases and sales.
① AI-generated value and corporate profit capture are different.
Improvements in Unity’s advertising performance may primarily benefit advertisers or game developers.
Seagate’s higher storage density may transfer value to customers through lower prices.
Technological progress should therefore be assessed alongside changes in margins and cash flow.
② Seagate and Amazon occupy different sides of the same AI spending cycle.
Cloud infrastructure investment generates revenue for equipment suppliers but represents cash outflows for the investing companies.
Both may benefit from AI, yet favorable financial results may emerge at different times.
Analysis of the global economic outlook and AI capital spending should identify where profits accrue across the supply chain, rather than focus solely on aggregate investment growth.
③ Data growth does not imply proportional growth in HDD unit sales.
Higher-capacity products, compression, deduplication, and data deletion policies affect the number of drives required.
Investors should examine total capacity shipped, pricing per terabyte, and product margins alongside unit shipments.
④ Accelerating growth can reflect base effects.
Higher year-over-year growth at Unity may partly reflect weak prior-year results.
Sequential trends and growth measured on a consistent business perimeter are necessary to assess the strength of a recovery.
⑤ Improved cash flow does not necessarily mean improved shareholder value.
Stock-based compensation can support reported cash flow because it does not require an immediate cash payment.
However, an increasing share count can dilute existing shareholders.
For software companies such as Unity, analysis should include GAAP results, stock-based compensation, and diluted share counts alongside adjusted earnings.
10. Investor Checklist: What to Verify Before Focusing on Position Increases
- Verify the filing: Review the reporting entity, reporting quarter, original filing, and amendments on SEC EDGAR.
- Identify the measurement: Distinguish changes in share count, market value, and portfolio weight.
- Connect the thesis to financial results: Assess whether revenue growth, margins, capital expenditure, and free cash flow support the investment rationale.
- Evaluate expectations embedded in the share price: Strong companies can deliver weak investment returns when valuations are excessive.
- Review macroeconomic risks: Consider interest rates, credit conditions, corporate advertising budgets, and cloud investment plans.
- Assess portfolio risk: Companies in different industries may share exposure to growth expectations and interest-rate sensitivity.
Korean investors should also assess the impact of USD/KRW movements on returns measured in Korean won.
Confidence in long-term growth and the decision to buy at a specific valuation are separate judgments.
The relevant conclusion is not to abandon semiconductors and replicate the reported Unity purchase.
It is to distinguish AI opportunities across computing infrastructure, data storage, advertising monetization, and medical services, then identify which companies can generate sustainable cash flow.
< Summary >
- The reported 436% increase in Unity holdings and 32% Natera allocation require verification against the relevant Form 13F reporting period and calculation methods.
- Form 13F provides a historical quarter-end snapshot of certain reportable securities, not a complete current portfolio.
- Unity’s key drivers are AI advertising performance and profitability; Seagate’s are storage demand and supply discipline; Natera’s are test volumes and reimbursement.
- Claims that Amazon has completed its capital investment and Fox has acquired Roku should not be treated as verified facts.
- The critical investment issue is whether AI-generated value translates into corporate earnings and per-share cash flow.
[Related Articles…]
*Source: [ 내일은 투자왕 – 김단테 ]
– 드러켄밀러 반도체 다 팔고 이 AI 주식 436% 늘렸다?