● France Turmoil, Debt Crisis, Global Shock, AI Risks
France Disruption Sends a Warning to Global Economic Outlook: Why Protests, Sovereign Yields, Political Risk, and AI Investment Are Now Linked
The latest protests in France should be viewed not as a local education dispute, but as a convergence of aging demographics, welfare spending, fiscal deficits, rising sovereign yields, and political instability.
More importantly, this is not only a French issue.
The same structural pressures are emerging in the United States, Japan, Europe, and South Korea, making “tightening” a likely defining theme for the global economic outlook from next year onward.
If sovereign yields continue to rise, the impact could extend to U.S. equities, the Nasdaq, the KOSPI, foreign exchange markets, and AI infrastructure investment.
What appears to be a school protest in France is, at a deeper level, a signal that global asset markets may again face pressure from rates and fiscal constraints.
1. The Starting Point of the France Protests: A Budget Issue, Not an Education Issue
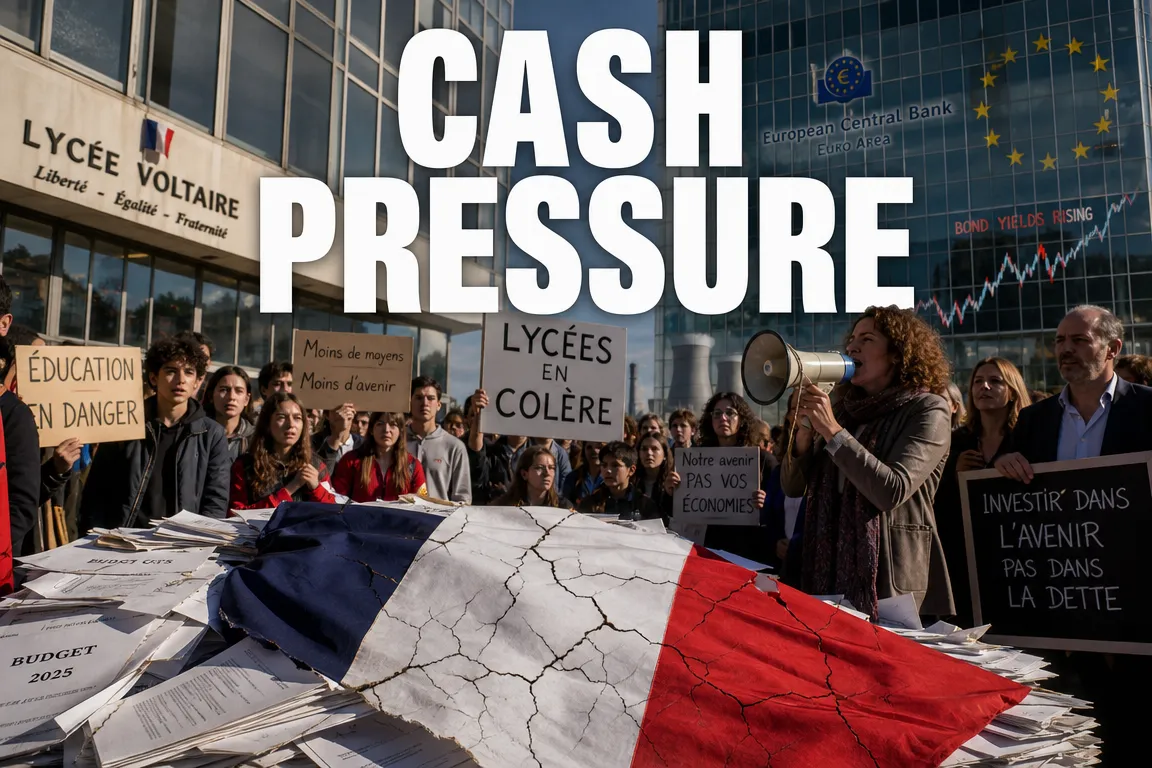
The protests began with concerns over poor conditions at a high school.
Teachers were said to be in short supply, class sizes were around 32 students, and facilities were deteriorating to the point that water supplies were unreliable.
Reports also cited rats and cockroaches in classrooms, inadequate air conditioning during heat waves, and poor sanitation including missing toilet paper.
The significance is that this occurred in France, a major developed economy and one of the largest in the European Union.
France has long been associated with the welfare-state model.
That such issues are surfacing in public education suggests that fiscal management has become increasingly constrained.
- Teacher shortages
- Overcrowded classrooms
- Neglected school facilities
- Insufficient cooling during heat waves
- Resistance to education spending cuts
- Broader participation by students, teachers, and university students
The core issue is therefore not simply school conditions, but how the state allocates its budget.
Raising education spending requires offsetting cuts elsewhere.
At the same time, France faces rising pension and social welfare burdens due to population aging.
This places the country in a zone of fiscal trade-offs, where expanding one category of spending requires reducing another.
2. Why the Protests Expanded: More Than 1,000 Schools, Arrests of Minors, and Public Backlash
According to the original report, the protests spread to more than 1,000 high schools.
Of those, 222 schools were blocked, and university students joined the demonstrations, turning them into a nationwide movement.
Arrests were reported at 687, with 86% of detainees said to be minors, intensifying public criticism.
Police response also triggered controversy, including injuries and a reported case in which a 15-year-old boy lost a hand after being struck by a police grenade.
Such incidents often convert a localized protest into broader social anger.
Concern from the United Nations further indicates that the situation has reached a level of wider social instability.
- Protests expanded to more than 1,000 high schools
- 222 schools blocked
- University student participation expanded the movement
- 687 arrests reported
- 86% of detainees reportedly minors
- Police response sparked injury-related controversy
- UN concern signaled elevated social tensions
Protests usually begin with a specific trigger.
However, their real force depends on how much underlying frustration has already accumulated in society.
In France, education, pensions, taxation, inflation, and political distrust appear to have converged, allowing the protests to escalate quickly.
3. France’s Fiscal Stress: Debt at 119% of GDP and a 5.4% Deficit
France’s public debt was reported at 119% of GDP.
It is also expected to rise above 121% next year.
The fiscal deficit stands at 5.4% of GDP, which is high by eurozone standards.
The government has proposed reducing the deficit to around 5%, but markets appear unconvinced.
The reason is straightforward: when debt is high and rates are rising, interest costs increase rapidly.
A larger deficit requires more bond issuance, and heavier issuance tends to push investors to demand higher yields.
That in turn raises interest expenses and worsens fiscal conditions.
This is the classic feedback loop of sovereign fiscal stress.
- Public debt: 119% of GDP
- Projected debt ratio next year: above 121%
- Fiscal deficit: 5.4% of GDP
- Government target: reduce deficit to 5%
- Austerity plan: 54 billion euros in savings
- Possible freezes on public sector pay and pensions, plus tax increases
France has two broad options.
First, it can pursue austerity and reduce spending.
Second, it can issue more debt to finance the deficit.
The first option is politically unpopular.
The second increases the risk of higher sovereign yields and credit-rating pressure.
Either path carries significant political and economic costs.
4. Why Political Risk Matters More: Tightening Is Needed, But Elections Make It Difficult
France was described as having lost a stable parliamentary majority after the 2024 snap election.
That makes it difficult for the government to pass a credible austerity budget.
Frequent changes in the prime minister have also added to political instability.
With presidential elections approaching, fiscal consolidation becomes even harder.
Measures such as pension freezes, public sector wage restraint, tax increases, and cuts to education spending are difficult for politicians to support.
These policies are costly in electoral terms.
Tightening may be economically necessary, but it remains politically unattractive.
As a result, markets may increasingly expect symbolic reforms rather than meaningful fiscal adjustment.
This is the key concern: France may be unable to implement the degree of consolidation that markets believe is necessary.
5. The ECB Is Drawing a Line: France Must Solve Its Own Problem
The European Central Bank’s response is another important factor.
The original report suggested that the ECB is not prepared to intervene aggressively to suppress French sovereign yields.
The underlying view is that the eurozone should not be expected to lower France’s borrowing costs if the problem originates from domestic political instability.
For markets, this is a cautious and potentially negative signal.
It reduces confidence that the ECB will automatically defend French bonds as it has done in previous stress episodes.
If there is no reliable buyer of French government debt, yields may continue to rise.
Higher yields increase interest burdens and reinforce concerns about fiscal deterioration.
6. France-Germany Spread Widening: A Market Warning Signal
The widening gap between French and German sovereign yields is another key indicator.
The original report stated that the spread had widened to around 1.5 percentage points.
A spread above 1 percentage point was described as the widest in 14 years.
German sovereign debt is generally regarded as the safest benchmark in Europe.
Rising French yields relative to Germany indicate that markets are assigning greater risk to France.
There was even mention that French yields were higher than those of Italy and Greece.
That is highly symbolic.
In the past, the center of Europe’s debt crisis was in southern Europe.
Now one of the eurozone’s core economies is being treated with similar caution by markets.
7. Similarities to the 2011 Eurozone Crisis: Equities Could Enter a Period of Pause
During the 2011 eurozone debt crisis, global equities came under severe pressure.
After the 2008 financial crisis, markets recovered strongly in 2009 and remained relatively resilient in 2010.
But the 2011 European debt crisis shifted markets into a weaker and more uncertain phase.
At that time, Europe had little choice but to move toward austerity, which reduced liquidity in the system.
Equity markets are highly sensitive to liquidity conditions.
When governments spend more and central banks lower rates, risk appetite tends to improve.
When budgets are cut and rates rise, equities face headwinds.
This is why the current French situation matters.
If Europe moves back into a tightening cycle, U.S. equities and the KOSPI are unlikely to remain unaffected.
8. How Higher Oil Prices Can Push Sovereign Yields Higher
The original report also identified rising oil prices as a key driver behind higher sovereign yields.
Supply disruptions involving Russian refining capacity, diesel, and gasoline were cited as contributing factors.
When refined product supply tightens, gasoline and diesel prices rise.
Higher energy prices feed into inflation.
When inflation rises, central banks find it harder to cut rates.
As a result, sovereign yields may remain elevated or move higher.
Europe is especially vulnerable because of its dependence on imported energy.
The report also noted a widening spread between Brent and WTI, along with news that Russian crude is trading at a premium in some markets.
Continued Chinese and Indian demand for Russian oil adds further complexity.
Additional geopolitical risk in the Strait of Hormuz could keep oil prices elevated.
A meaningful decline in oil prices would help stabilize yields, but that outcome remains uncertain.
9. Why U.S. Treasury Markets Could Also Be Affected
France’s situation matters for U.S. Treasury markets because global bond markets are interconnected.
According to the original report, major foreign buyers of U.S. Treasuries have included the United Kingdom, Belgium, Norway, and France.
China’s share of Treasury purchases has reportedly declined relative to past years.
Historically, Japanese and European investors have played a major role in supporting U.S. debt markets.
If those buyers become less active because of domestic fiscal or liquidity pressures, the market balance changes.
Some of those holders may even need to sell Treasuries to support their own currencies or domestic funding needs.
That would force the U.S. to look for new marginal buyers.
Whether China returns as a large buyer, or whether stablecoin demand can absorb sufficient issuance, remains uncertain.
In that context, continued U.S. fiscal expansion becomes more difficult to finance cheaply.
10. U.S. Tightening Pressure: A $41 Trillion Debt Ceiling and Possible 6% Ten-Year Yield
The U.S. federal debt ceiling was described as $41 trillion, with total debt already above $40 trillion.
The report also noted concerns that debt could rise by about $1 trillion every three to six months.
After the election, another increase in the debt ceiling may be required.
However, raising the ceiling means issuing more Treasury debt.
The key question is who will absorb that supply.
If demand is insufficient, yields rise.
The report stated that the U.S. 10-year yield is around 5.2%, with some market participants discussing a possible move toward 6%.
It also noted sharp recent increases in yields over one- and three-month periods.
Higher Treasury yields raise corporate borrowing costs as well.
This is particularly relevant for large technology companies financing AI data centers and cloud infrastructure through debt issuance.
11. AI Infrastructure Investment Has Two Sides: Strong Growth, Higher Rate Sensitivity
AI infrastructure remains a high-growth theme.
Data centers, semiconductors, power grids, cooling systems, cloud servers, and AI software are areas that governments and companies are likely to continue funding.
However, higher sovereign yields increase financing pressure across the sector.
Data centers require substantial upfront capital.
Land, electricity, servers, GPUs, cooling systems, and networking equipment all require large investments.
When rates are low, long-duration projects are valued more favorably.
When rates are high, the present value of future earnings declines, making long payback projects more difficult to justify.
As a result, not all AI-related stocks are likely to benefit equally.
In a high-rate environment, firms with strong cash flow, large customers, and policy support are better positioned.
Companies without profitability or operating leverage may face valuation pressure.
- More favorable areas: AI semiconductors, power infrastructure, data center operators, cloud-demand beneficiaries
- Areas to approach cautiously: unprofitable AI start-ups, highly leveraged data center developers, speculative theme stocks
- Key screening criteria: profitability, cash flow, customer base, policy support, debt ratio
For the period ahead, the relevant framework is no longer “buy AI indiscriminately,” but rather “select AI companies that can withstand higher rates.”
12. Japan Is Not Immune: Rising Yields and Potential Treasury Sales
Japan is another important variable.
It has historically been one of the largest buyers of U.S. Treasuries.
But Japan is also facing upward pressure on yields.
The original report said Japanese 10-year yields rose from around 2% a year ago to above 3% today.
From Japan’s perspective, that is a substantial increase in a short period.
If the Bank of Japan is forced to normalize policy further, Japanese investors may become less willing to absorb U.S. debt.
In some cases, they may even sell Treasuries to support domestic liquidity or defend the yen.
That would increase pressure on U.S. yields and reduce the likelihood of an easy rate-cut cycle.
13. South Korea Is Relatively Stable, But Still Exposed to Global Yield Trends
South Korea was described as having relatively manageable tax revenue conditions and some capacity to expand spending.
However, it is not insulated from global rate moves.
If U.S., European, and Japanese yields all rise, Korean bond yields are likely to be affected as well.
Even if the Bank of Korea wants to lower rates independently, exchange-rate pressure may limit its flexibility.
KRW weakness can raise import prices and renew inflationary pressure.
For Korean investors, this means global economic trends, U.S. Treasury yields, FX, and oil prices must all be monitored together.
Domestic markets can no longer be analyzed in isolation.
14. The Key Point Often Missed Elsewhere: Fiscal Conflict in the Welfare-State Model
The most important issue is not simply that protests intensified in France.
The deeper problem is that the welfare-state model is running into structural limits in a high-rate, aging environment.
Most developed countries now face the same basic constraints.
Pension and healthcare spending continue to rise with aging populations.
Defense and energy security costs are also increasing.
At the same time, AI competitiveness requires additional industrial investment.
Meanwhile, higher rates are pushing debt service costs higher.
In this environment, it is increasingly difficult to fund education, welfare, defense, industrial policy, and interest payments at the same time.
Governments therefore face unavoidable choices.
They must decide which spending categories to reduce, which taxes to raise, and which industries to support.
That process is likely to produce more political conflict and more social protests.
15. Investment Implication: The Era of Buying Anything and Profiting Easily May Be Ending
The most practical investment message from the original report is that the period of broad, easy gains may be ending.
When high rates and austerity coincide, liquidity conditions tighten.
Lower public spending and higher taxes create pressure on consumption and corporate earnings.
In that environment, broad indices may struggle while only selected sectors attract capital.
Investors should focus on areas where governments and corporations have limited room to cut spending.
- AI infrastructure
- Power grids and energy infrastructure
- Defense and security industries
- Semiconductor supply chains
- Large-cap technology firms with strong cash flow
- Financial stocks that can benefit from higher rates
- Real assets with inflation-hedging characteristics
By contrast, assets with high debt, rate sensitivity, or valuation driven mainly by expectations should be treated cautiously.
For U.S. investors, the focus should be on AI companies with credible monetization rather than the Nasdaq as a whole.
For Korean investors, sectors such as semiconductors, power equipment, defense, shipbuilding, and energy-related value chains may be more directly aligned with global fiscal, security, and AI spending trends.
16. Key Indicators to Monitor Going Forward
Whether the France situation remains a local issue or becomes a broader financial risk depends on several indicators.
- France-Germany 10-year sovereign yield spread
- France’s sovereign credit outlook
- Passage of France’s austerity budget
- ECB intervention risk
- Brent and WTI price trends
- Movement in the U.S. 10-year yield toward 6%
- Japanese bond yields and yen exchange rates
- U.S. debt ceiling negotiations
- Continuation of AI data center investment
- Relative performance of growth and value stocks
If the France-Germany spread widens further, markets may begin treating France as a broader eurozone fiscal risk.
If the U.S. 10-year yield approaches 6%, valuation pressure on growth and AI stocks could increase.
If oil prices remain elevated, expectations for rate cuts may weaken further.
17. Conclusion: France Is a Sign of Strain in the Welfare State and an Early Signal of the High-Rate Era
The protests in France are not only a domestic political event.
They reflect a structural combination of aging demographics, higher welfare costs, rising interest burdens, and renewed inflation pressure from energy prices.
Political leaders recognize the need for tightening, but electoral constraints make decisive action difficult.
Markets respond by pushing up sovereign yields and pricing in credit risk.
If these pressures spread to the wider eurozone and U.S. Treasury markets, the global economic outlook becomes considerably more complicated.
For investors, the relevant strategy is no longer to expect a broad liquidity-led rally.
Instead, attention should shift to sectors that can attract capital even in a high-rate, tighter-fiscal environment, such as AI infrastructure, power grids, semiconductors, defense, and energy security.
At the same time, AI-related equities should be evaluated carefully, since higher yields also weigh on valuation.
Going forward, markets are likely to reward not just growth, but growth with the capacity to withstand higher rates.
< Summary >
The protests in France are fundamentally about fiscal deficits and budget allocation, not education alone.
Rising welfare costs from aging are colliding with cuts to education spending, weaker public services, and broader social frustration.
France’s public debt is around 119% of GDP, and its deficit is 5.4%, both high by eurozone standards.
Political instability makes austerity difficult, while markets are pricing in higher sovereign yields and possible credit-rating pressure.
If the ECB does not intervene decisively, France’s issue could evolve into a wider eurozone debt concern.
The United States and Japan also face debt and rate pressures, which may keep global sovereign yields elevated.
Higher rates are a headwind for AI infrastructure investment, even as AI remains a structurally important spending category for governments and corporations.
For investors, the focus should shift from indiscriminate exposure to assets with strong cash flow and resilience under tighter financial conditions.
[Related Articles…]
- France Fiscal Stress and Eurozone Yield Outlook
- AI Infrastructure Investment and the Global Macro Outlook
*Source: [ Jun’s economy lab ]
– 잘 생각해보면 남의 일이 아닌 프랑스 혼란(시위, 금리, 정치)