● Bond, Boom, Stocks, Surge
Has the U.S. Treasury Yield Peaked? Post-Midterm Investment Strategy and the Potential for a Joint Rally in Stocks and Bonds
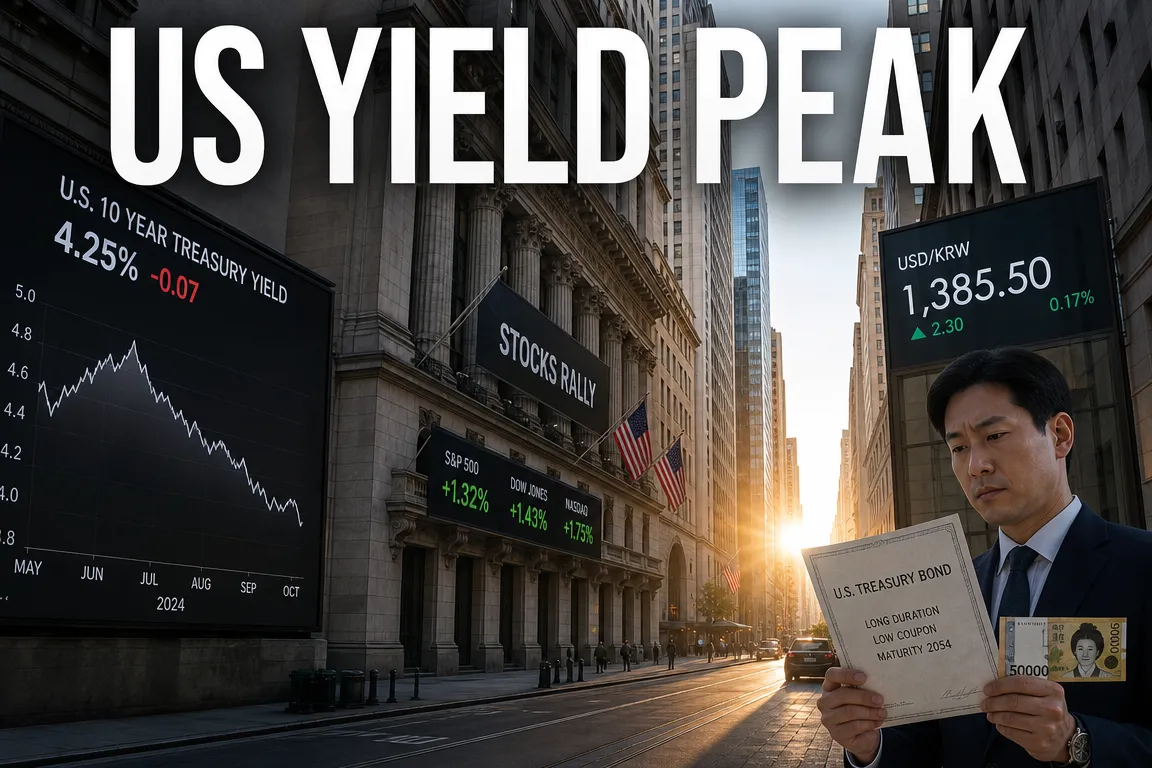
Has the 10-year U.S. Treasury yield reached its peak?
The central thesis is that Treasury yields could decline after the U.S. midterm elections, allowing stock and bond prices to rise simultaneously.
The analysis also examines historically low valuations in the Korean equity market, opportunities in semiconductors, defense, secondary batteries, and robotics, and U.S. Treasury strategies based on the USD/KRW exchange rate.
However, high Treasury yields alone do not justify an unconditional allocation to bonds.
Investors must consider the risk that U.S. fiscal policy, oil prices, inflation, geopolitical conflict, and exchange rates may diverge from expectations.
1. Key Market Issue | Is the 10-Year U.S. Treasury Yield Near Its Peak?
The central assessment is that the 10-year U.S. Treasury yield is approaching the upper end of its long-term range.
The source states that the yield rose as high as 5.3% before retreating, placing it near a 20-year high.
Because this figure depends on the publication date and market data source, investors should verify current yields through the U.S. Treasury or a major financial data provider before making investment decisions.
- When Treasury yields rise, prices of existing bonds decline.
- When Treasury yields fall, prices of previously issued higher-coupon bonds rise.
- Purchasing long-duration bonds near a yield peak may therefore provide both interest income and capital gains.
- However, further yield increases can produce significant losses in long-duration bonds.
The proposed tactical strategy is to enter when the 10-year Treasury yield is near 4.5% and realize gains if it falls toward the low-4% range.
This approach seeks to capitalize on a defined yield range, but historical upper and lower bounds may not recur.
If fiscal deficits and Treasury issuance continue to increase, long-term yields may decline more slowly than expected even if the policy rate is reduced.
2. Why the U.S. Midterm Elections Matter for the Treasury Market
The 2026 U.S. midterm elections are scheduled for November 3. All House seats and a portion of Senate seats will be contested midway through the presidential term.
For markets, the critical issue is not only the election result but whether control of the presidency and Congress becomes divided between the two major parties.
- Unified government occurs when the president’s party controls both the House and the Senate.
- Divided government occurs when the opposing party controls at least one chamber of Congress.
- Under divided government, tax cuts and large fiscal spending packages may face greater legislative resistance.
- Lower expectations for fiscal expansion could reduce concerns about Treasury issuance and inflation, creating downward pressure on long-term yields.
The source cites historical cases in which the 10-year Treasury yield declined by approximately 60 basis points, or 0.6 percentage points, during the six months following the formation of a divided government.
If the 10-year yield falls from 5.0% to 4.4%, longer-duration bonds could experience a larger price increase.
However, results vary depending on the sample period and methodology.
Midterm elections do not automatically lead to lower yields.
3. Conditions for Stocks and Bonds to Rise Together After the Election
Stocks and bonds are often viewed as inversely correlated assets.
However, both can appreciate in a soft-landing environment characterized by moderating inflation and the absence of a severe recession.
- Lower inflation reduces the need for additional monetary tightening.
- Declining market yields increase bond prices.
- Lower corporate funding costs and equity discount rates support stock valuations.
- If the economy avoids a sharp contraction, corporate earnings may remain resilient.
Growth stocks are particularly sensitive to interest rates because their valuations depend heavily on the present value of future cash flows.
Stable Treasury yields may reduce valuation pressure on technology, AI semiconductor, and robotics companies with substantial long-term growth expectations.
The outcome differs if yields decline because of a financial crisis or severe recession.
In that scenario, bonds may rise while equities decline as earnings forecasts deteriorate.
The key issue is therefore not the yield decline itself, but whether disinflation occurs alongside a moderate economic slowdown.
4. Korean Equities | Potential Reversal of Crisis-Level Undervaluation
The source assesses the KOSPI and KOSDAQ as significantly undervalued relative to major domestic and international markets.
Investor sentiment weakened following a correction after first-half gains, but the competitive position of Korean listed companies has not necessarily deteriorated to the same extent.
Memory Semiconductors
Memory semiconductors, led by Samsung Electronics and SK Hynix, remain a major earnings driver for the Korean equity market.
Expansion in AI data center investment could support demand for high-bandwidth memory and server DRAM.
Investors should assess not only the industry recovery but also supply growth, memory pricing, and changes in customer capital expenditure.
Even if earnings improve, share prices may correct if elevated expectations have already been priced in.
Defense
The defense sector could benefit from higher military spending in Europe, the Middle East, and other regions.
Korean defense companies are expanding exports through competitive pricing, short delivery schedules, local production, and technology-transfer packages.
However, contract delays, export financing, exchange rates, and local political conditions can affect the timing of revenue recognition.
Secondary Batteries
The secondary battery sector has undergone a substantial correction because of slower electric vehicle demand and elevated inventories.
The source highlights the possibility of improving earnings growth.
However, an industry-wide recovery should not be assumed solely from a rebound in electric vehicle sales.
Battery pricing, utilization rates, North American subsidy policies, and competitiveness against Chinese producers must be evaluated at the company level.
Robotics
The robotics industry has substantial long-term growth potential based on manufacturing automation and the expansion of logistics, service, and humanoid robots.
Advances in AI models may also improve robotic perception, decision-making, and control.
However, many companies remain unprofitable, and market expectations may exceed operating performance. Revenue growth and cash flow therefore require close scrutiny.
5. Why Capital May Shift from Deposits to Bonds
The source notes that funds moving from banks into securities markets during the first half later began returning to bank deposits.
It also states that brokerage account deposits declined by approximately KRW 40 trillion to KRW 50 trillion from their peak.
This may indicate that investors are reducing exposure to volatile assets and moving toward deposits and cash equivalents.
However, if interest rates are near their peak, maintaining an exclusive allocation to deposits may not always be optimal.
Deposits provide contractual interest income but do not generate capital gains when market rates decline.
Bonds can provide interest income while also benefiting from price appreciation as yields fall.
- Short-term bonds offer lower price volatility and are suitable for liquidity management.
- Intermediate-term bonds can balance interest income and potential capital gains from lower rates.
- Long-term bonds offer greater upside when yields fall but also greater downside when yields rise.
- Investors who may need to sell before maturity should avoid excessive exposure to long-duration bonds.
6. Why U.S. Treasuries May Be Preferred to European, Japanese, or Korean Government Bonds
The source also views European, Japanese, and Korean government bond yields as potentially attractive.
Global bond yields rose together amid higher oil prices and concerns about renewed inflation.
U.S. Treasuries remain a priority because of the market’s scale, liquidity, and status as a U.S. dollar asset.
Korean investors can obtain returns from three sources:
- Interest income from bond coupon payments.
- Capital gains when market yields decline and bond prices rise.
- Foreign-exchange gains when the Korean won depreciates against the U.S. dollar and the USD/KRW exchange rate rises.
Conversely, Korean won appreciation can reduce local-currency returns even if bond prices rise.
U.S. Treasury investment is therefore not solely an interest-rate strategy; it also requires an assessment of the U.S. dollar outlook.
7. The Relationship Between the USD/KRW Exchange Rate and Semiconductor Exports
The source identifies a USD/KRW exchange rate near KRW 1,320 as a potentially favorable entry range for U.S. Treasuries.
Because this level reflects conditions at the time of publication, investors should verify the current exchange rate independently.
One factor behind the currency’s decline was foreign-currency conversion demand from semiconductor exporters such as Samsung Electronics and SK Hynix.
When exporters convert U.S. dollar revenue into Korean won, the increased dollar supply can strengthen the won.
Continued strength in semiconductor exports may therefore limit a sharp rise in the USD/KRW exchange rate.
Over the medium to long term, however, the U.S.-Korea interest-rate differential, foreign capital flows, energy import costs, and geopolitical risks could weaken the won again.
This supports a phased purchasing strategy across multiple exchange-rate levels rather than a single large allocation to U.S. Treasuries.
8. Key Risks That Could Disrupt the Market Outlook
Oil Prices and Inflation
Persistently high oil prices could raise transportation and production costs, delaying disinflation.
If inflation accelerates again, central banks may postpone rate cuts and long-term Treasury yields could rise.
U.S. Fiscal Deficits and Treasury Supply
Even under divided government, previously authorized spending and interest expenses are unlikely to decline quickly.
If the U.S. government increases Treasury issuance to finance fiscal deficits, supply pressure could keep long-term yields elevated.
This factor may be more important to long-duration bond investors than the policy-rate outlook alone.
Geopolitical Conflict
Escalating military tensions in the Middle East or a deterioration in U.S.-Iran relations could affect both oil prices and demand for safe-haven assets.
U.S. Treasuries may initially strengthen as investors seek safety, but an inflationary oil-price shock could ultimately push long-term yields higher.
Geopolitical conflict does not automatically result in higher bond prices.
Excessive Expectations for Quantitative Easing
Policy-rate cuts and quantitative easing are not equivalent.
Rate cuts can occur as part of monetary policy normalization, while quantitative easing is generally used during severe recessions or periods of financial market stress.
Investors should not interpret the possibility of rate cuts as an automatic return to large-scale quantitative easing.
9. The Most Important Factor Often Overlooked in Other Market Reports
The central objective is not to identify the exact peak in Treasury yields, but to construct a portfolio supported by multiple return drivers.
U.S. Treasury returns are not determined solely by interest rates and bond prices.
For Korean investors, the USD/KRW exchange rate can materially affect total returns.
Bond-price gains may be offset by Korean won appreciation, while U.S. dollar strength may improve local-currency returns even if bond-price gains are limited.
A joint rally in stocks and bonds should not be assumed to be permanent.
Both assets may rise during a soft landing characterized by stable inflation and continued economic growth.
However, their relationship may change if the economy enters a severe recession or inflation accelerates again.
The key question for the 2027 economic outlook is not how many rate cuts will occur.
It is more important to determine whether lower rates result from disinflation, recession, or financial market stress.
10. A Practical Portfolio Framework for Individual Investors
The central asset-management principle is not the recommendation of a specific financial product.
Investors should construct portfolios based on income, asset levels, investment horizons, and cash-flow requirements.
- Living expenses and emergency reserves should be held in liquid assets such as deposits or money market instruments.
- Funds required within one to three years should be allocated primarily to deposits and short-term bonds.
- Medium- and long-term capital can include both equities and intermediate- or long-term bonds to address changing economic and interest-rate conditions.
- U.S. Treasury purchases should be diversified across maturities and exchange-rate entry points.
- Korean semiconductor, defense, secondary battery, and robotics companies should be selected based on earnings and valuations rather than treated as uniform sector exposures.
- Tax-advantaged accounts should be assessed not only for tax benefits but also for withdrawal timing and eligible investment products.
Investors with limited conviction regarding the direction of rates may consider a barbell strategy combining short- and long-term bonds.
Short-term bonds provide current income and stability, while long-term bonds offer potential capital gains if yields decline.
Equity exposure can be divided between undervalued Korean sectors and global AI growth companies to reduce concentration by country and industry.
11. Pre-Investment Checklist
- Confirm whether the 10-year U.S. Treasury yield has entered a sustained downward trend.
- Assess whether U.S. headline and core inflation are declining consistently.
- Monitor oil prices and inflation expectations for renewed increases.
- Review changes in U.S. fiscal policy and Treasury issuance plans after the midterm elections.
- Compare the maturity, duration, and currency-hedging policies of U.S. Treasury ETFs and individual bonds.
- Review product disclosures because direct investments and domestic or international ETFs may have different tax and cost structures.
- Evaluate company-level earnings forecasts, leverage, and cash flow in addition to industry growth potential.
< Summary >
If the 10-year U.S. Treasury yield is near the upper end of its long-term range, bonds may offer an attractive medium- to long-term investment opportunity.
A divided government following the U.S. midterm elections could reduce expectations for fiscal expansion and place downward pressure on Treasury yields.
Stocks and bonds could rise together if inflation moderates and the economy achieves a soft landing.
Korean equities may offer valuation-recovery opportunities in semiconductors, defense, secondary batteries, and robotics.
U.S. Treasury investors must consider interest income, bond-price movements, and foreign-exchange gains or losses.
Oil prices, inflation, U.S. fiscal deficits, Treasury supply, and geopolitical conflict remain key risks to the peak-yield thesis.
Diversifying across stocks, bonds, cash, maturities, and exchange-rate entry points is more practical than relying on a single directional forecast.
[Related Articles…]
*Source: [ 경제 읽어주는 남자(김광석TV) ]
– 국채금리 정점 찍었나…중간선거 이후 주식·채권 같이 오른다 | 경읽남과 토론합시다 | 이혜나 대표님
● China EV Crash, Battery Boom, Tesla Gamble
Can Rechargeable Batteries Become Korea’s “Second Semiconductor” Industry? China’s EV Restructuring and the Real Opportunity for Korea’s Battery Sector
This report examines the potential consolidation of China’s EV industry, Tesla’s strategy beyond price competition, the conditions required for Korea’s rechargeable battery sector to achieve semiconductor-scale growth, and underappreciated areas with significant EPS potential.
Financial distress among Chinese EV manufacturers would not automatically make Korean battery companies the primary beneficiaries.
For Korea to develop a “second semiconductor” industry, it must establish leadership across technology standards, materials supply chains, power infrastructure, and energy storage systems rather than focus solely on battery cell production capacity.
The central issue is that the industry’s profit pool could shift toward power grids and energy storage systems while the market remains focused on EV sales.
1. Summary of the Core Arguments
The source material is presented as a compilation of a three-part interview with economic commentator Yoon Seok-cheon.
The description states that filming occurred on October 20 and broadcasting took place from October 21 to 26, but it does not specify the year.
The following assessment should therefore be viewed as an interpretation of the industry’s structural outlook rather than as real-time news or confirmed industry data.
- First: Quality concerns and excessive competition could trigger substantial consolidation among Chinese EV manufacturers.
- Second: Tesla is seeking to integrate software, autonomous driving, robotics, and energy platforms rather than operate solely as an automobile manufacturer.
- Third: Strategic changes in China’s battery industry could create short-term pressure and long-term opportunities for Korean battery companies.
- Fourth: Rapid EPS growth in selected Korean industries could support the emergence of new market leaders.
- Fifth: Korea’s rechargeable battery industry could develop into a strategically important sector comparable to semiconductors.
2. Potential Consolidation of China’s EV Industry
China’s EV market expanded rapidly through government support, aggressive capital investment, and competitive pricing.
However, the number of market participants and total production capacity have grown faster than underlying demand.
Prolonged price competition can weaken operating margins and cash flow even when unit sales increase.
Sales growth and profitability improvement are separate considerations.
Four Risks Facing Chinese EV Manufacturers
- Excess production capacity: Manufacturers may need to reduce prices further to clear inventory and maintain factory utilization.
- Weak profitability: Cutting prices faster than production costs can increase market share while reducing corporate viability.
- Quality and safety concerns: Weak confidence in assembly quality or critical components could limit overseas expansion.
- Global regulation: Tariffs, subsidy restrictions, and local production requirements could reduce the overseas competitiveness of China-based production.
The source refers to incidents involving brake pedal failures and rear-axle defects.
Individual incidents are insufficient to assess the quality of China’s entire EV industry.
A comprehensive risk assessment requires data on recall volumes, defect rates, warranty provisions, insurance costs, and investigations by national safety authorities.
The principal risk is not the collapse of the entire Chinese EV sector, but the potential exit of companies with insufficient capital and technology.
3. Why China’s EV Restructuring Would Not Be an Unqualified Benefit for Korea
The failure of Chinese EV companies could appear favorable for Korean automakers and battery producers because it would reduce the number of competitors.
However, the immediate impact on the broader supply chain could be negative.
China has substantial influence across battery cells, cathode and anode materials, precursors, graphite, and lithium refining.
Production cuts or bankruptcies among Chinese companies could disrupt raw-material prices and supply contracts, resulting in inventory valuation losses and lower utilization rates for Korean companies.
Potential Short-Term Effects
- Further declines in battery and material prices.
- Additional pressure from automakers to reduce battery prices.
- Inventory valuation losses on previously acquired raw materials.
- Slower-than-expected utilization increases at new factories.
- Renegotiation of pricing and volume terms in long-term supply contracts.
Potential Long-Term Opportunities
- Greater demand for non-Chinese supply chains in the United States and Europe.
- Stronger partnerships between Korean battery suppliers and automakers prioritizing safety and quality.
- Improved bargaining power for Korean companies if policies restrict or exclude Chinese batteries.
- New markets for high-performance and energy-storage batteries.
The critical issue is not the failure of Chinese companies itself, but which suppliers secure global customers and supply-chain positions after consolidation.
4. Tesla’s Strategy Extends Beyond Vehicle Sales
The source emphasizes the Tesla Roadster and Elon Musk’s plans.
However, the available information is insufficient to confirm specific technologies or launch schedules.
From an industry perspective, the more important issue is that Tesla does not seek to justify its valuation solely through automotive manufacturing profits.
Tesla’s long-term strategy is to integrate EVs, autonomous-driving software, charging networks, robotics, artificial intelligence, and energy storage into a unified ecosystem.
Tesla’s Target Revenue Structure
- Electric vehicles: Hardware supporting the broader platform.
- Autonomous driving: Software sales and recurring subscription revenue.
- Charging infrastructure: Control of an energy network serving EV users.
- Energy storage systems: Expansion into energy supply and demand management.
- AI and robotics: Application of vehicle-generated data and computing capabilities to other industries.
Even if price competition reduces profit per vehicle, recurring revenue from software and energy services could materially change Tesla’s earnings structure.
Tesla should therefore be assessed using automotive margins, paid autonomous-driving adoption, energy-storage deployments, and service revenue in addition to vehicle deliveries.
5. Rechargeable Batteries as Korea’s Potential “Second Semiconductor” Industry
The source indicates that rechargeable batteries and the surrounding industrial ecosystem could become Korea’s next semiconductor-scale industry.
Korean battery companies have established long-term partnerships with global automakers and expanded production capacity in North America and Europe.
Quality control and large-scale manufacturing experience remain important competitive advantages.
However, production capacity alone will not enable the battery sector to sustain semiconductor-level profitability.
Conditions Required for Semiconductor-Scale Growth
- Maintain a technology advantage.
Korean companies must establish measurable leadership in energy density, charging speed, cycle life, and safety. - Reduce raw-material dependence.
High reliance on specific countries for lithium, nickel, graphite, and precursors increases supply-chain vulnerability. - Improve yields and cost competitiveness.
Revenue growth will not translate into earnings if production yields remain weak. - Protect the profitability of long-term contracts.
A large order backlog does not necessarily guarantee strong operating margins. - Establish a recycling ecosystem.
Recovering critical minerals from used batteries can reduce costs and supply-chain risk. - Develop markets beyond EVs.
Energy storage systems, ships, robotics, urban air mobility, and data centers could become significant sources of battery demand.
6. Energy Storage Systems May Be the Underappreciated Growth Driver
A key issue receiving relatively limited attention is that energy storage systems, rather than EVs, could become the battery industry’s next major growth driver.
Growth in AI data centers increases both electricity consumption and the need for supply stability.
Solar and wind generation are intermittent, requiring systems that can store electricity and release it when needed.
Energy storage systems perform this function.
Even if EV demand temporarily slows, continued investment in AI data centers, renewable energy, and power grids could redirect battery demand toward stationary storage.
How AI Expansion Could Generate Battery Demand
- Generative AI and cloud services expand.
- Data-center electricity consumption increases.
- Power-grid loads and volatility rise.
- Investment in renewable and distributed generation expands.
- Demand increases for large-scale energy storage systems that balance electricity supply and demand.
Potential beneficiaries include battery cell manufacturers as well as suppliers of power conversion systems, battery management systems, cooling equipment, fire-prevention technology, and electrical grid equipment.
Focusing AI investment analysis only on semiconductors and data-center equipment could overlook secondary opportunities in power infrastructure and energy storage.
7. Relationship Between EPS Growth and Market Leadership
The source argues that accelerating EPS growth can support substantial share-price appreciation.
EPS represents net income divided by the number of outstanding shares.
Revenue growth does not improve EPS when costs rise at a faster rate.
Conversely, EPS can increase rapidly when higher utilization reduces the fixed-cost burden as revenue expands.
Conditions That Could Accelerate Battery Company EPS
- New factories exceed their break-even utilization rates.
- Lower raw-material costs are reflected in product prices with a delay.
- The share of high-value products increases.
- Revenue grows faster than depreciation expenses.
- Tax credits and production incentives are recognized in earnings.
- New businesses such as energy storage systems enter the commercial revenue stage.
An EPS rebound from a low base does not necessarily establish a company as a long-term market leader.
Investors should distinguish improvements in operating competitiveness from one-off subsidies, foreign-exchange gains, or asset disposals.
8. Investment Metrics to Review Before Selecting Individual Stocks
The source refers to a Korean market leader with globally competitive capabilities but does not identify the company in the available excerpt.
Assessing the characteristics required for market leadership is more appropriate than speculating about an unidentified company.
- Order backlog: Review the expected timing of revenue conversion rather than the announced value alone.
- Utilization rate: Actual equipment use is more important than announced capacity expansion.
- Operating cash flow: Confirm whether accounting earnings are converting into cash.
- Inventory: Rapid increases in raw-material and finished-goods inventories can raise valuation-loss risk.
- Customer concentration: Assess whether the company is excessively dependent on a single automaker.
- Debt and financing: Evaluate increases in borrowings and interest expenses associated with major capacity investments.
- Technology: Patents, production yields, safety performance, and customer certification are more relevant than production volume alone.
9. Three Scenarios for Korea’s Battery Industry
Optimistic Scenario
Restructuring accelerates across China’s EV and battery industries while the United States and Europe strengthen policies supporting non-Chinese supply chains.
Higher utilization at Korean companies’ overseas plants could improve revenue and EPS simultaneously.
Expanding energy-storage demand could reduce dependence on EVs and support long-term industry growth.
Neutral Scenario
The EV market continues to grow, but more slowly than previously expected.
Persistent battery price competition could delay margin recovery despite revenue growth.
Companies with superior technology and stronger balance sheets would likely outperform weaker competitors.
Pessimistic Scenario
Chinese companies achieve both low costs and technological improvements while expanding localized production in global markets.
Korean companies could face prolonged margin pressure from high capital expenditure and low utilization.
Additional risks include automakers developing internal battery production or diversifying suppliers.
10. Distinguishing Facts from Interpretation
- Individual defect cases involving Chinese EVs should be evaluated against confirmed investigation results.
- Potential corporate failures do not imply the collapse of the entire industry.
- Claims of Chinese battery-sector withdrawal should be assessed to determine whether they refer to a specific company, product, or market.
- The view that rechargeable batteries could become Korea’s second semiconductor industry is a conditional outlook, not a confirmed outcome.
- High EPS growth can support share prices, but valuation and cash flow must also be considered.
- Because the filming year is unclear, current investment decisions require updated earnings, industry data, and policy information.
11. Structural Changes Affecting the Global Economic Outlook
The global outlook will not be determined solely by EV sales.
Key variables include supply-chain competition between the United States and China, European environmental regulation, interest rates, exchange rates, and critical-mineral prices.
Even as the EV market expands, high financing costs could delay consumer purchases.
By contrast, AI investment and power-infrastructure expansion could increase demand for energy storage systems and electrical grid equipment.
Semiconductors, rechargeable batteries, AI data centers, and power grids are likely to become increasingly interconnected.
12. Key Issues Receiving Limited Market Attention
First, financial pressure on Chinese companies would not guarantee an automatic advantage for Korean companies.
If consolidation produces a smaller number of stronger Chinese competitors, competitive pressure could intensify.
Second, battery-sector competitiveness will depend more on utilization and cash flow than on factory scale.
Capacity expansion supports future growth, but insufficient demand can increase depreciation and interest burdens.
Third, the battery industry’s next growth driver could emerge outside the EV market.
AI data centers and renewable energy expansion could simultaneously increase demand for energy storage, electrical equipment, cooling systems, and safety technologies.
Fourth, a “second semiconductor” industry would require an integrated ecosystem rather than a single company or product.
National competitiveness would require coordination across battery cells, materials, equipment, recycling, software, and power grids.
< Summary >
- China’s EV market faces potential consolidation due to excess capacity and prolonged price competition.
- Individual quality incidents should not be used to assess China’s entire EV industry.
- Financial pressure on Chinese companies could create both short-term challenges and long-term opportunities for Korean battery producers.
- Tesla’s strategy extends beyond EVs to autonomous driving, AI, robotics, charging infrastructure, and energy storage.
- Rechargeable batteries and power infrastructure could become Korea’s next strategically important industrial ecosystem.
- AI data centers and renewable energy investment could make energy storage systems the battery industry’s next major growth driver.
- Investment analysis should consider utilization, cash flow, inventory, debt, and customer concentration in addition to EPS.
- The filming year and company names are unclear, requiring verification through updated earnings releases and official data.
This material is based on the provided video description and excerpts and is intended for industry analysis only. It does not constitute a recommendation to buy or sell any security.
[Related Articles…]
*Source: [ 달란트투자 ]
– 한국에 제2의 반도체 탄생. 곧 어마어마한 일 벌어진다 | 윤석천 경제평론가 풀버전