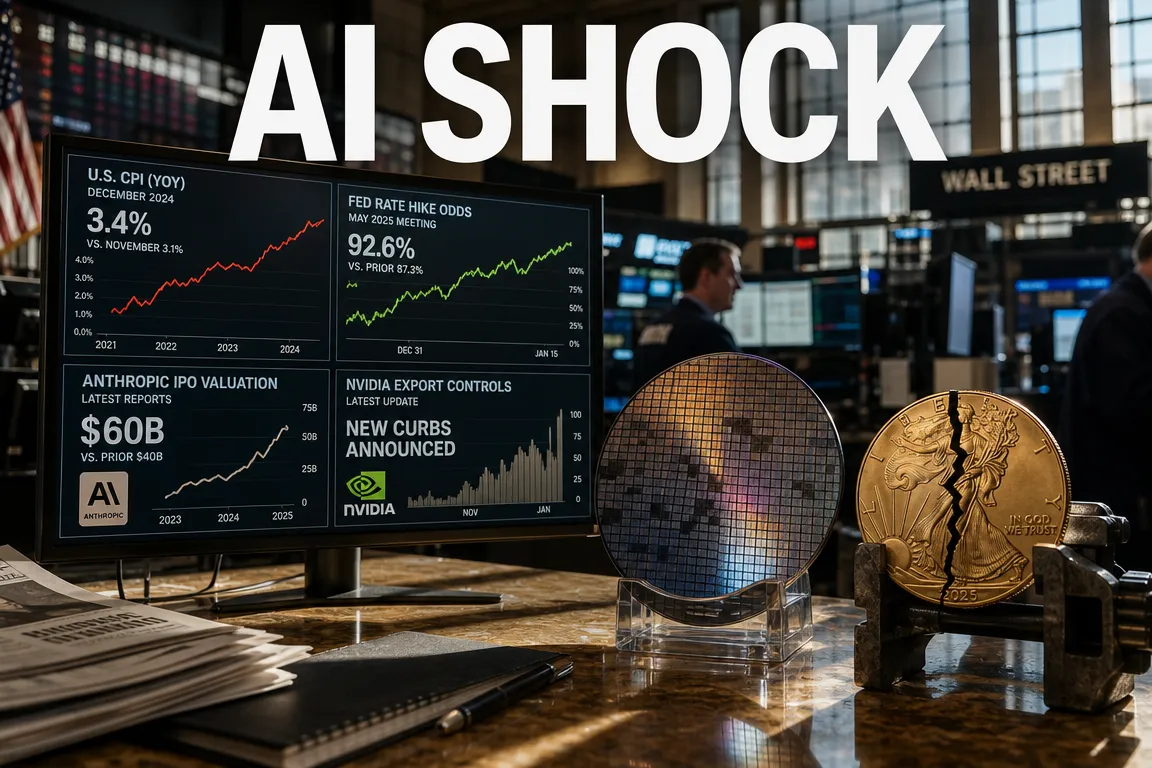
● Fed-Hawkish, AI-Shakeout, Anthropic-Alert
Key Market Variables: Potential 50bp U.S. Rate Hike and Anthropic IPO Risks
Investors should focus on three issues.
First, whether a higher-than-expected U.S. Consumer Price Index could materially increase the probability of a 50bp Federal Reserve rate hike.
Second, why AMD and Broadcom have shown relative resilience while higher rates pressure the Nasdaq and Nvidia.
Third, whether slower growth at Anthropic could affect broader data-center investment and demand for AI semiconductors.
The timing and reliability of several figures remain unclear, and some may contain decimal-point or transcription errors.
Anthropic’s reported valuation and long-term revenue forecasts should not be treated as confirmed without additional primary-source verification.
1. Higher-Than-Expected U.S. CPI Revives Rate Concerns
Headline CPI reportedly increased 0.4% month over month, exceeding the market consensus of 0.3%.
Core CPI, which excludes volatile food and energy prices, reportedly rose 0.3%, above the 0.2% forecast.
The key concern is that both headline and core inflation exceeded expectations.
Markets focus not only on the absolute inflation rate but also on the difference between reported data and consensus forecasts.
Stronger-than-expected CPI may indicate that inflation is not moderating sufficiently.
This could lead the Federal Reserve to keep rates elevated for longer or consider additional increases.
Consequently, the outlook for U.S. interest rates has again become a central equity-market variable.
2. Christopher Waller’s Comments and the Possibility of a December 50bp Hike
Federal Reserve Governor Christopher Waller reportedly made a conditional hawkish statement regarding core CPI.
He was cited as potentially supporting a 50bp increase in December if monthly core CPI exceeded 0.3%.
A 50bp move equals 0.5 percentage points and is twice the standard 25bp adjustment.
However, the reported core CPI figure was 0.3%, making it unclear whether the condition of exceeding 0.3% was met.
The distinction between 0.3% and above 0.3% is material for monetary-policy interpretation.
The exact date and wording of Waller’s comments should be verified through Federal Reserve materials or an official transcript.
Federal Reserve decisions do not depend on one monthly CPI release or a single policymaker’s remarks.
Employment data, Personal Consumption Expenditures inflation, wage growth, inflation expectations, and financial conditions are also relevant.
A December 50bp increase should therefore not be regarded as a confirmed outcome.
3. The Primary Risk Is Not a Single Rate Increase
The more significant risk is not one large increase but an extended period of restrictive interest rates.
Deutsche Bank was reportedly forecasting consecutive 25bp increases in December, January, and March, while some market participants discussed a possible 50bp move in December.
The publication dates and underlying reports were not identified, so these projections should not be treated as current official forecasts.
The broader implication is that market rate expectations have shifted higher.
A higher expected terminal rate could increase U.S. Treasury yields and corporate financing costs.
It could also delay the anticipated start of monetary easing.
Growth and technology stocks are especially vulnerable because their valuations depend heavily on the present value of future earnings.
4. Why the Nasdaq and Nvidia Are Sensitive to Interest Rates
U.S. equities reportedly extended losses following the CPI release and hawkish Federal Reserve commentary.
The Nasdaq declined approximately 1.1%, the Dow Jones Industrial Average 0.5%, the S&P 500 0.69%, and the Russell 2000 1.37%.
The trading date was not specified, so these figures should not be used as current market data.
Technology valuations are particularly sensitive to interest rates because a large share of expected profits may be generated far in the future.
Higher market rates increase the discount rate applied to those future cash flows.
Valuation multiples can therefore contract even if earnings forecasts remain unchanged.
Nvidia may be especially sensitive because its valuation reflects both substantial AI growth expectations and a premium multiple.
A short-term decline in Nvidia shares does not necessarily indicate weakening AI demand.
Higher Treasury yields, profit-taking, valuation concerns, and position adjustments can also drive near-term weakness.
5. Why AMD and Broadcom Have Been Relatively Resilient
AMD and Broadcom reportedly outperformed other large technology companies on a relative basis.
However, the two companies should not be viewed simply as direct substitutes for Nvidia.
AMD is positioned as an alternative supplier capable of competing with Nvidia in the AI accelerator market.
Efforts by cloud providers to reduce supplier concentration and diversify their supply chains could create opportunities for AMD.
Broadcom is differentiated through custom AI semiconductors and networking equipment for large technology companies rather than direct competition in general-purpose GPUs.
Expansion of proprietary AI chips by hyperscalers could support Broadcom’s ASIC design and networking businesses.
Nvidia weakness does not automatically imply gains for AMD or Broadcom.
However, expectations that AI infrastructure will expand beyond general-purpose GPUs into custom chips and diversified accelerators may provide relative support.
6. Why Defensive Sectors Outperformed
Defensive sectors such as consumer staples reportedly showed greater resilience.
When interest-rate and economic uncertainty rise, investors tend to prioritize earnings stability and cash flow over growth expectations.
Demand for essential goods is generally less sensitive to an economic slowdown.
Consumer-staples companies are therefore considered defensive because their earnings are typically less volatile than those of technology companies.
When recession and inflation concerns increase simultaneously, capital may rotate from growth stocks into defensive sectors.
7. Figures Requiring Verification in Anthropic’s IPO Outlook
Anthropic was reportedly considering an initial public offering at a valuation of approximately $1.4 trillion, compared with an earlier figure of about $2 trillion.
These figures appear highly unusual relative to Anthropic’s publicly reported financing history and market valuation.
The $1.4 trillion figure may be a transcription error for $140 billion, and the units and decimal points require verification.
It is also necessary to confirm whether Anthropic has officially announced an IPO timetable or target valuation.
Reports concerning adviser selection, confidential preparations, and an actual regulatory filing represent materially different stages of the IPO process.
Exploring a listing does not mean that an IPO has been confirmed.
8. Is a $685 Billion Revenue Forecast for 2030 Realistic?
A Goldman Sachs analyst was reportedly forecasting Anthropic revenue of $685 billion in 2030 and $52 billion in 2026.
These figures may represent transcription errors for $68.5 billion and $5.2 billion, respectively, and should be checked against the original report.
If the $685 billion estimate is accurate, it would imply revenue on a scale comparable with the world’s largest companies.
Achieving this level would require dominant market positions across enterprise AI, consumer subscriptions, APIs, AI agents, and industry-specific solutions.
Rapid company growth alone would be insufficient; the addressable market would also need to expand substantially.
A constructive outlook for the AI industry should not be interpreted as a guarantee of exceptional growth for any single company.
9. Anthropic’s Core Issue Is the Quality of Growth
Anthropic’s annualized revenue reportedly increased rapidly during the first half of the year but showed signs of stagnation after July.
The source and methodology for the underlying chart were not provided, so the claim should not be treated as confirmed financial data.
Annualized revenue for a private company may differ materially from recognized accounting revenue.
Results can vary depending on whether the calculation annualizes one month of sales or includes contracted revenue.
The broader issue nevertheless remains relevant.
Higher AI usage does not necessarily produce comparable improvements in revenue or profitability.
If free users and lower-priced plans expand or API prices decline, usage can increase while revenue per unit falls.
Investors should focus on paid-customer retention, revenue per customer, inference costs, and gross margin rather than user growth alone.
10. Why Claude Code’s Success May Not Be Sufficient
Claude Code is an AI coding tool that allows developers to use natural language to write, revise, and automate software-development tasks.
Strong product performance and favorable developer reviews do not necessarily translate into high profitability.
Coding agents can consume substantial volumes of tokens because they maintain long sessions and repeatedly read, test, and modify code.
Usage-based access to high-performance models can therefore become costly for enterprise customers.
Companies are likely to select the least expensive model that meets required performance levels rather than consistently choosing the most capable model.
Tasks such as code cleanup, test generation, documentation, and basic debugging may not require frontier-model performance.
Anthropic must therefore demonstrate competitiveness in both model quality and cost efficiency.
11. Chinese AI Models Could Accelerate Price Competition
The improving performance of Chinese AI models is an important competitive development.
If Chinese open-source and commercial models provide adequate performance in coding and general business applications, enterprise customers will have more alternatives.
Because not every task requires the highest-performing model, companies may distribute requests across lower-cost systems.
Complex tasks can be assigned to advanced models, while repetitive and less demanding work is routed to less expensive alternatives.
This approach is commonly described as model routing or a multi-model strategy.
If this structure becomes standard, leading companies such as Anthropic and OpenAI may face continued pressure to reduce token prices despite higher usage.
Competition is likely to shift from absolute model performance toward price-performance and total operating cost.
12. The Impact of Lower Token Prices on AI Companies
Lower token prices can support market expansion by making AI services accessible to more companies and increasing overall usage.
For AI providers, however, inference costs must decline faster than selling prices for profitability to improve.
If token prices fall by 50% while computing costs decline by only 20%, rising usage could increase losses.
Revenue growth alone is therefore insufficient for evaluating AI companies.
Relevant metrics include revenue per token, inference cost per token, GPU utilization, customer-acquisition costs, and contract-retention rates.
13. How Slower Anthropic Growth Could Affect Data-Center Investment
Anthropic reportedly entered into large-scale computing commitments with several major technology companies.
AI developers must secure cloud servers, accelerators, networking equipment, and power infrastructure to train and operate their models.
Cloud providers use projected demand to justify substantial investment in data centers and semiconductors.
Risk increases when an AI company’s actual revenue fails to meet those expectations.
If utilization remains low relative to contracted capacity, the AI company may face excessive fixed costs and purchase obligations.
Cloud providers may also experience lower utilization and longer capital-recovery periods.
Claims involving direct computing arrangements with Broadcom and SpaceX, in addition to Amazon and Google, require separate verification of the contractual structure and official disclosures.
14. The Most Important Underappreciated Risk
The central issue is not the CPI release or a single-day decline in Nvidia shares.
The more significant risk is a potential gap between large infrastructure commitments based on future AI demand and the actual revenue generated by AI services.
The current AI investment cycle depends on model developers, cloud providers, semiconductor companies, and data-center operators expanding simultaneously based on shared growth expectations.
Model developers secure computing capacity in anticipation of customer growth.
Cloud providers use those commitments to justify data-center expansion.
Semiconductor companies expand production and supply-chain investment based on cloud-provider orders.
If AI-service revenue at the beginning of this chain grows more slowly than expected, the investment case across the ecosystem could weaken.
Higher interest rates would amplify this risk because data centers require substantial upfront capital and have long payback periods.
Higher financing costs also reduce the present value of future cash flows.
U.S. inflation data and Anthropic’s growth outlook should therefore be viewed as connected through interest rates and AI capital expenditure rather than as separate developments.
15. New Growth Drivers Required by Anthropic
Anthropic will need revenue sources beyond general-purpose chatbots and coding tools to support a premium valuation.
The first potential area is pharmaceuticals and biotechnology.
AI systems that demonstrate measurable reductions in drug-discovery costs or clinical-development timelines could command premium pricing.
The second area is scientific research, including mathematics, physics, and materials science.
Verifiable progress on previously unresolved problems could create economic value beyond standard chatbot applications.
The third area is enterprise AI for highly regulated industries.
In finance, legal services, healthcare, and the public sector, security, accuracy, and auditability may be more important than price.
The fourth area is end-to-end AI agents.
Enterprises may pay higher fees if agents can complete workflows independently and demonstrate measurable cost savings.
16. Investor Monitoring Checklist
U.S. inflation: Monitor three- and six-month annualized trends and core services inflation rather than relying on one monthly CPI release.
Federal Reserve communication: Prioritize FOMC statements, the Summary of Economic Projections, and press conferences over conditional comments from individual officials.
Bond market: The two-year U.S. Treasury yield primarily reflects policy-rate expectations, while the ten-year yield incorporates longer-term growth and inflation expectations.
AI company performance: Paid conversion, enterprise-customer retention, and inference margins are more important than total user counts.
Data-center investment: Assess utilization and investment returns rather than capital expenditure alone.
AI semiconductor demand: Evaluate GPU orders alongside demand for custom AI chips, networking equipment, and power infrastructure.
Anthropic IPO: Base conclusions on official regulatory filings, adviser appointments, and company announcements rather than media reports alone.
17. Figures That Require Additional Verification
First, the year and month of the CPI release were not specified.
Second, the report does not consistently distinguish between core CPI of 0.3% and core CPI above 0.3%.
Third, the exact wording and official source of Christopher Waller’s comments require verification.
Fourth, the publication date of Deutsche Bank’s projected sequence of rate increases should be confirmed.
Fifth, Anthropic’s reported $1.4 trillion valuation may be a transcription error for $140 billion.
Sixth, the reported 2030 and 2026 revenue forecasts of $685 billion and $52 billion may instead be $68.5 billion and $5.2 billion.
Seventh, claims of stagnating annualized revenue require verification of the source and calculation methodology.
Corrections to these figures could materially change conclusions regarding Anthropic’s valuation and growth outlook.
< Summary >
Higher-than-expected U.S. CPI could weaken expectations for rate cuts and pressure the Nasdaq and highly valued technology stocks.
A December 50bp increase is not a confirmed scenario, and both Waller’s comments and the relevant core CPI threshold require verification.
AMD and Broadcom are better viewed as beneficiaries of AI semiconductor diversification and custom-chip adoption than as simple substitutes for Nvidia.
Anthropic could face profitability pressure if token-price reductions exceed improvements in inference efficiency.
The principal systemic risk is that actual AI revenue may not support the scale of computing commitments and data-center investment already planned.
Anthropic’s reported valuation and long-term revenue forecasts may contain transcription errors and require confirmation through primary sources.
[Related Articles…]
Federal Reserve Policy and the Outlook for Technology Stocks
Anthropic Growth, AI Infrastructure Spending, and Valuation Risks
*Source: [ 내일은 투자왕 – 김단테 ]
– 12월에 미국 기준금리가 0.5%p 한방에 상승?
● CPI Shock, Jensen Huang Scandal, Nvidia Selloff
U.S. CPI Shock and Jensen Huang Allegations | Implications for Federal Reserve Policy, Nvidia, Samsung Electronics, and SK Hynix
Three points require particular attention.
First, the figures presented as October U.S. CPI data in the original broadcast were actually September data.
Second, allegations concerning Nvidia CEO Jensen Huang’s private life, potential links to Chinese intelligence, and indirect GPU exports were claims raised in the source material, not facts established by an official investigation.
Third, the more consequential market issue is whether U.S. restrictions on AI semiconductor access by China will expand to cloud computing services and data centers in third countries.
Investors should not infer an inflation shock from misidentified CPI data or assume a leadership vacuum at Nvidia based on unverified allegations.
However, tighter U.S. export controls could affect Nvidia’s valuation, the broader AI semiconductor market, data-center investment, and HBM demand at Samsung Electronics and SK Hynix.
1. Key Correction | Why the “October CPI Shock” Interpretation Was Flawed
The original broadcast interpreted figures displayed on screen as October U.S. CPI data and immediately assessed their market implications.
Later in the broadcast, it acknowledged that the figures referred to September rather than October.
Accordingly, the headline CPI figure of 3.7% and core CPI figure of 2.6% cited earlier should not be treated as new October inflation data.
If official data for a given month were unavailable because of a government shutdown or disruption to statistical collection, market forecasts and unofficial estimates should not be presented as official statistics.
- Verify the reference month before interpreting any release.
- Distinguish between month-over-month and year-over-year figures.
- Label market forecasts, preliminary estimates, and official releases separately.
- Disclose the methodology when averages or estimates are used to fill gaps in official data.
The principal lesson is that confirming the reference period and official status of a figure is more important than the figure’s direction alone.
2. How to Interpret U.S. CPI
U.S. CPI should be assessed across headline and core measures, as well as month-over-month and year-over-year changes.
Headline CPI includes food and energy, while core CPI excludes these volatile categories to provide a clearer view of underlying inflation pressure.
Month-over-Month CPI | The Figure That Often Drives the Immediate Market Reaction
When month-over-month CPI exceeds expectations, bond markets tend to price in a tighter Federal Reserve policy path.
This can raise U.S. Treasury yields, strengthen the dollar, and create near-term pressure on growth-oriented equities such as the Nasdaq.
High-valuation technology stocks are particularly sensitive to rising rates because their valuations depend heavily on the discounted present value of future earnings.
Year-over-Year CPI | A Measure of the Medium-Term Inflation Trend
Year-over-year CPI is useful for assessing the broader direction of inflation.
However, the reading can be distorted when the comparison period was unusually high or low.
If the prior-year figure is unavailable or unreliable, the year-over-year growth rate also becomes less informative.
Core CPI and Services Inflation | Why the Federal Reserve May Remain Cautious
If headline CPI rises primarily because of higher oil prices, the increase may represent a temporary supply shock.
If housing, wages, healthcare, transportation, and other service costs also accelerate, inflation may be spreading more broadly across the economy.
The inflation outlook should therefore consider housing costs, wage growth, and the persistence of services inflation rather than oil prices alone.
3. Does Higher Oil Always Lead to Higher CPI?
Oil prices materially affect inflation but are not the sole determinant of CPI.
Even after a sharp increase in energy costs, broader inflation may remain contained if companies cannot pass those costs on to consumers.
Conversely, lower oil prices may not substantially reduce core inflation when wages, housing, insurance, and healthcare costs continue to rise.
Investors should assess whether energy inflation is spreading into food, goods, housing, and services.
Contribution analysis identifies how much each category adds to the overall CPI rate.
If energy accounts for most of the increase while other components remain stable, the data may indicate a temporary energy shock rather than broad-based inflation.
4. Federal Reserve Outlook | One CPI Release Does Not Determine the Rate Path
The original source stated that the probability of a rate increase effectively exceeded 100%, implying that markets had begun pricing in a larger rate move.
However, indicators such as CME FedWatch allocate probabilities across separate target-rate ranges. These probabilities should not be added together and described as a “120% probability of a rate increase.”
Each target-rate range and its change from the previous trading session should be evaluated separately.
The Federal Reserve does not base its policy decisions on CPI alone.
It also considers the Personal Consumption Expenditures price index, employment data, wages, consumption, inflation expectations, and financial conditions.
Even if CPI exceeds expectations, a rapid deterioration in employment and consumption could alter the policy outlook.
Conversely, persistent services inflation and wage growth could delay rate cuts even as headline CPI moderates.
A practical sequence for evaluating the market response is as follows:
- Confirm the official CPI reference month and reported figures.
- Distinguish between headline and core CPI.
- Separate month-over-month and year-over-year results.
- Review movements in the 2-year and 10-year U.S. Treasury yields and the U.S. Dollar Index.
- Assess changes in the policy path implied by federal funds futures.
5. Jensen Huang Allegations | Separate Verified Facts from Source Claims
The original source presented allegations about Jensen Huang’s private life, possible links to Chinese intelligence, and indirect GPU access as components of a single case.
It also referred to specific individuals and companies, alleged U.S. intelligence surveillance, a report to President Trump, a classified memorandum, and possible congressional and FBI investigations.
However, it did not provide supporting official documents, law-enforcement statements, Nvidia disclosures, or links to reporting from established news organizations.
These claims should therefore not be characterized as a confirmed scandal or espionage case.
The following distinctions are necessary at this stage:
- Any claim that Jensen Huang admitted to an extramarital relationship requires separate verification through an Nvidia statement or credible reporting.
- Claims that a specific individual is a Chinese intelligence operative should not be treated as factual without confirmation from judicial or law-enforcement authorities.
- Allegations that Nvidia intentionally provided GPUs or computing services indirectly to Chinese companies require formal investigation.
- The claim that President Trump knew of and tolerated such conduct is a political inference in the source material, not an established fact.
- Impeachment or Jensen Huang’s immediate resignation represents an extreme scenario dependent on multiple unverified assumptions.
Investors assessing Nvidia should prioritize SEC filings, Nvidia board statements, and official materials from the U.S. Department of Commerce and Department of Justice over social-media speculation or sensational claims.
6. Material Issue 1 | Was Computing Capacity Exported Instead of Physical GPUs?
The first structural issue is whether Chinese companies accessed high-performance GPU computing capacity remotely through data centers in third countries.
Even when the United States restricts exports of advanced GPUs to China, Chinese companies may obtain comparable computing resources by connecting to data centers in Singapore, Malaysia, Indonesia, or other jurisdictions.
This could weaken the policy objective of export controls even if physical GPUs never enter China.
Future U.S. restrictions may extend beyond the final destination of the chips.
Regulators could require verification of cloud customers’ beneficial owners, end users, access locations, and model-training purposes.
Such measures would create additional compliance obligations for Nvidia, Amazon Web Services, Microsoft Azure, Google Cloud, and global data-center operators.
7. Material Issue 2 | Indirect GPU Exports Through Third Countries
The second issue is whether advanced GPUs were re-exported to China through third-country entities or data centers.
Confirmed physical diversion or false end-user declarations could constitute violations of U.S. Export Administration Regulations.
However, a company’s purchase of a large number of GPUs does not by itself establish illegal re-export activity.
Purchase agreements, customs records, final installation locations, and actual users would all require verification.
Extending U.S. controls to third countries could affect the growth of the Southeast Asian data-center industry.
Legitimate cloud operators could face additional customer due-diligence and equipment-use reporting requirements.
8. Material Issue 3 | Product Roadmaps and Supply-Chain Information
The source raised the possibility that next-generation GPU designs, launch schedules, and supply-chain strategies were disclosed externally.
Core design information is typically restricted to selected research and development personnel and protected by internal security systems. A personal relationship alone is insufficient evidence of large-scale technology leakage.
However, management information such as product launch timing, customer allocations, advanced-packaging capacity, and supply-chain bottlenecks can have substantial strategic value to competitors and governments.
Any formal investigation could therefore examine the disclosure of nonpublic commercial information as well as technical files.
9. Potential Risks if Misconduct by Jensen Huang Is Confirmed
The following are conditional scenarios that would apply only if an official investigation established legal or regulatory violations.
Key-Person Risk
Nvidia is highly dependent on Jensen Huang’s technical vision and leadership.
Without a clearly disclosed succession plan, an abrupt leadership gap could affect the product roadmap, customer relationships, and investor confidence.
Legal and Regulatory Risk
Confirmed export-control violations could result in fines, transaction restrictions, or limitations on participation in government programs.
If material violations were knowingly withheld from investors, Nvidia could also face disclosure-related shareholder litigation.
Board and Governance Risk
Nvidia’s board could consider an independent investigation, an internal-control review, compensation clawbacks, or restrictions on executive duties.
A private-life controversy would not automatically require resignation. The central issue would be whether the conduct affected company operations or violated applicable laws and policies.
Political Risk
If evidence showed that U.S. administration officials knowingly relaxed restrictions despite potential violations, the matter could expand into a political investigation.
However, the original source does not provide sufficient evidence to support claims of presidential impeachment or coordinated tolerance of misconduct.
10. Implications of Nvidia Restrictions for Samsung Electronics and SK Hynix
GPUs and HBM are essential AI-server components, and their demand is closely linked.
A decline in high-performance GPU shipments could reduce demand for the HBM integrated into those products.
Prolonged restrictions on Nvidia’s production or sales could therefore create near-term pressure on Samsung Electronics and SK Hynix.
However, GPU supply disruption would not necessarily cause a collapse in the memory semiconductor cycle.
HBM demand could shift to AMD products, proprietary AI accelerators, Google TPUs, Amazon Trainium, Microsoft Maia, and other alternatives.
Earnings at Samsung Electronics and SK Hynix will depend not only on aggregate HBM shipments but also on customer diversification, product qualification, yields, and average selling prices.
Key indicators include:
- Nvidia’s quarterly data-center revenue and shipment guidance
- Production plans for AMD products and proprietary accelerators developed by major technology companies
- HBM qualification and mass-production schedules at Samsung Electronics and SK Hynix
- Advanced-packaging capacity and production bottlenecks
- The scope of U.S. semiconductor export controls targeting China
- AI data-center investment plans among global technology companies
11. When Could AI Data-Center Investment Slow?
The original source projected that data-center capital expenditure could increase from 2025 through 2027 before aggregate investment begins to moderate in 2028.
It also suggested that the growth rate could slow in 2027 even if absolute spending continued to rise.
Equity markets often price in decelerating growth before investment declines in absolute terms.
Even if technology companies continue to increase capital expenditure, lower year-over-year growth could compress valuation multiples for AI semiconductor companies.
Conversely, delays caused by power shortages, permitting issues, or grid constraints may shift demand into future periods rather than eliminate it.
Data-center investment should be evaluated through the following factors:
- Announced investment plans versus actual expenditure
- Server orders and data-center completion schedules
- Power procurement and grid-connection timelines
- GPU supply and actual utilization rates
- AI service revenue and returns on investment
12. Could Other Countries Benefit from Delays in U.S. Data-Center Investment?
Slower or delayed U.S. data-center investment could ease supply constraints for GPUs, memory, and server equipment.
More stable equipment prices and shorter delivery times could encourage data-center operators in the Middle East, Asia, and Europe to accelerate investment.
Construction and equipment companies previously focused on the U.S. market could also pursue more overseas projects.
However, overseas data centers would not necessarily benefit if U.S. restrictions expanded to third-country cloud services.
Operators with significant exposure to Chinese customers could face higher compliance and customer-verification costs.
The benefits of improved equipment availability must therefore be assessed alongside the regulatory costs of expanded U.S. export controls.
13. Why China’s AI Industry Should Not Be Underestimated
The source noted that most Chinese AI token usage originates in the domestic market.
However, a large domestic market can enable Chinese companies to achieve scale and develop cost advantages.
In steel, shipbuilding, batteries, and electric vehicles, Chinese companies first expanded in the domestic market, reduced production costs, and then entered overseas markets.
A similar pattern could emerge in AI.
Higher domestic token usage does not by itself establish global AI leadership, but it can support model improvement, service commercialization, and demand for domestically produced AI chips.
Tighter U.S. export controls could also accelerate the development of a domestic semiconductor ecosystem led by Huawei and other Chinese companies.
14. The Most Consequential Underreported Issue
The central issue is not Jensen Huang’s private life but the potential shift in U.S. export controls from physical semiconductor chips to AI computing capacity.
Restrictions focused exclusively on physical chip movements can potentially be circumvented through overseas data centers and remote cloud access.
To address this issue, U.S. authorities may require global cloud providers to verify customer identities and final-use purposes.
AI semiconductor regulation could consequently evolve from a manufacturing-control regime into a digital computing-traceability framework comparable to customer due-diligence requirements in financial services.
This shift could have three major implications:
- Data centers in Southeast Asia and the Middle East could face greater obligations to verify China-related end users.
- Regulatory risk could affect not only Nvidia’s China revenue but also global cloud demand.
- China could accelerate the development of domestic AI chips and software optimization.
Restrictions on Nvidia would not necessarily benefit only AMD.
Greater regulatory and supply uncertainty could encourage major technology companies to reduce dependence on a single GPU supplier by accelerating proprietary accelerator development.
Over the longer term, competition between general-purpose GPUs and customized ASICs may become more important than competition between Nvidia and AMD alone.
15. Scenarios for the South Korean Equity Market and KOSPI Investors
Positive Scenario
If U.S. CPI resumes moderating and concerns about Federal Reserve tightening diminish, Treasury yields and the dollar could stabilize.
If the allegations involving Jensen Huang prove unfounded or remain unrelated to Nvidia’s operations, Nvidia’s share price and AI-sector sentiment could recover.
Sustained global data-center investment and expanding HBM demand would support Samsung Electronics and SK Hynix.
Neutral Scenario
If investigations continue but Nvidia’s shipments and customer orders remain unchanged, the primary effect may be higher share-price volatility.
If AI capital-expenditure growth slows while total spending continues to increase, semiconductor earnings could expand even as valuation upside becomes more limited.
Negative Scenario
If authorities confirm export-control violations and intentional misconduct by senior management, Nvidia could face fines, sales restrictions, and leadership disruption.
If lower GPU shipments reduce HBM orders, earnings estimates for South Korean semiconductor companies could face downward revisions.
If this coincides with higher U.S. CPI and renewed Federal Reserve tightening concerns, both the KOSPI and Nasdaq could face pressure from higher rates and weaker earnings expectations.
< Summary >
The figures initially analyzed as October CPI data were actually September data and should not be used to establish an October inflation shock.
CPI analysis must distinguish the official reference month, month-over-month and year-over-year changes, and headline and core inflation.
Claims concerning Jensen Huang’s private life, alleged links to Chinese intelligence, and indirect GPU exports remain unverified and should not be presented as established facts.
The more material market variable is whether the United States expands restrictions from physical GPU exports to overseas cloud computing services.
Tighter restrictions could affect Nvidia, global data centers, AMD, proprietary accelerators, and HBM demand at Samsung Electronics and SK Hynix.
Investment decisions should prioritize official CPI releases, U.S. government announcements, Nvidia disclosures, data-center capital expenditure, and actual semiconductor orders over sensational allegations.
[Related Articles…]
*Source: [ 경제 읽어주는 남자(김광석TV) ]
– [생방송] (1)CPI 물가쇼크 오는가? (2)젠슨황 스캔들과 그 파장 [즉시분석]