● Starship Reuse Shock, Tesla Profit Mirage
SpaceX Starship Reusability and the Tenfold Launch-Cost Gap: Key Variables for Tesla Investors
The critical question is not whether a launch tower can catch a rocket, but how cheaply and quickly that rocket can fly again.
Starship reusability could affect Starlink profitability, but claims of a tenfold launch-cost reduction require qualification. Any implications for Tesla’s equity value also depend on a demonstrable economic connection.
Factual verification is essential.
The source material combines established historical records, recent claims requiring verification, and inconsistent figures and timelines.
This report does not incorporate real-time filings or launch records. Claims concerning an upper-stage Starship catch, a SpaceX listing, or Tesla’s ownership of SpaceX are therefore treated as unverified.
1. Fact Check: A Booster Catch and an Upper-Stage Catch Are Different Events
- Super Heavy booster: The lower, first-stage rocket that provides thrust during the initial phase of launch.
- Starship upper stage: The spacecraft responsible for orbital insertion and payload delivery, which must withstand intense heating during reentry.
- Full reusability: Recovery of both vehicles followed by inspection, maintenance, and demonstrated repeated operation.
A documented milestone is the first launch-tower catch of a Super Heavy booster during Starship’s fifth test flight on October 13, 2024.
This event should not be described as the first upper-stage catch or proof of full-system reusability.
References to Flight 15, a return after 22 hours, deployment of 26 Starlink V3 satellites, and an upper-stage catch require verification against SpaceX’s official mission records.
Even if an upper-stage catch is confirmed, losing the booster on the same mission would distinguish progress in upper-stage recovery from full-system reusability.
2. What a Tenfold Difference in Starship Launch Costs Actually Means
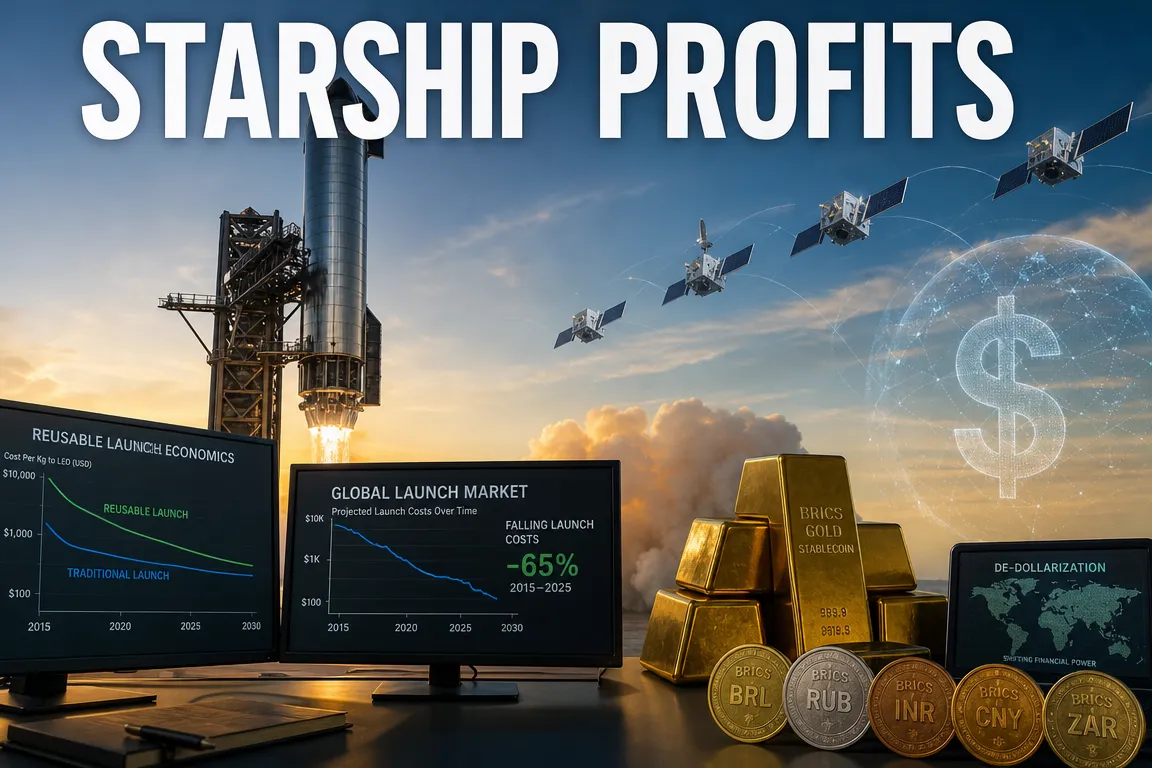
The source cites approximately $100 million per launch for largely expendable operations and a long-term target of approximately $10 million for fully reusable operations.
Although the figures differ by a factor of 10, they compare an external estimate with a corporate long-term target, not two verified operating costs.
① Expendable operations require recurring vehicle production.
Replacing the booster or upper stage after each launch creates recurring expenditure on engines, tanks, structures, and electronics.
High payload capacity alone cannot eliminate the cost of discarding launch hardware.
② Reusability spreads manufacturing costs across multiple flights.
Repeated use can reduce the manufacturing cost allocated to each launch.
However, recovery, transportation, inspection, heat-shield replacement, engine maintenance, insurance, and launch-site operations add costs.
A successful recovery therefore does not establish a 90% reduction in launch costs.
③ Launch cost and customer pricing are distinct.
Marginal operating cost, average cost including development and infrastructure, and the price charged to external customers are different measures.
Even if costs decline, competitive conditions and demand may allow SpaceX to reduce prices more gradually and retain the difference as profit.
④ Cost per kilogram depends on actual payload utilization.
Dividing launch cost by maximum design payload produces a different measure from the cost per kilogram achieved on an actual mission.
The cited combination of $100 million per launch and $1,000 per kilogram implies a payload of approximately 100 metric tons.
Target orbit, recovery requirements, and actual payload mass can materially change launch economics.
3. The Economic Value of Tower Catches Lies in Turnaround Time
Recovering a vehicle from the ocean requires vessels and personnel, with schedules exposed to weather and sea conditions.
Seawater exposure may also increase inspection and corrosion-management requirements.
Recovery near the launch site could reduce transportation and repositioning requirements.
The economic objective is to shorten the interval between launches and increase the number of missions supported by the same assets.
- Reflight interval: Time between recovery and the next launch.
- Maintenance requirements: The extent of component replacement, including heat-shield tiles and engine parts.
- Reuse count: The number of economically viable flights per vehicle.
- Launch-site throughput: Whether towers and ground infrastructure can support the next mission when the vehicle is ready.
- Recovery failure rate: Whether average costs decline after accounting for vehicle losses and operational interruptions.
Falcon 9 achieved its first first-stage landing on land in December 2015 and its first flight using a recovered first stage in March 2017.
The first successfully landed booster was not the booster used for the first reflight.
This illustrates that recovery demonstrations and commercially viable repeated use require separate validation.
4. Starlink Is the Most Direct Potential Beneficiary
A sustained reduction in Starship launch costs would directly benefit Starlink’s large-scale satellite network.
For a constellation requiring continuous expansion and replacement, launch expenditure is recurring capital investment rather than a one-time expense.
① Network expansion could require less capital.
Deploying more communications capacity per launch at a lower launch cost could reduce the investment required for a given level of network capacity.
The cited V3 capacity multiples and maximum satellite counts require official confirmation of specifications, comparison benchmarks, and actual launch configurations.
② Capacity growth does not imply proportional revenue growth.
Higher satellite throughput generates revenue only if supported by subscriber demand, ground-network connectivity, national authorizations, and service pricing.
Geographic mismatches between available capacity and concentrated demand mean that aggregate capacity growth will not necessarily eliminate congestion.
③ Free cash flow matters alongside operating profit.
Starlink could report operating profits while retaining limited cash after satellite manufacturing, launches, and ground-infrastructure investment.
Investors should assess revenue growth alongside constellation maintenance, replacement expenditure, and cash generation after investment.
The claim that Starlink contributes 36% of SpaceX revenue and 85% of operating profit should not support investment decisions without verifiable primary documentation.
5. Direct-to-Cell Services and Orbital Data Centers Have Different Timelines
Direct-to-cell connectivity: Spectrum access and carrier partnerships matter alongside launch costs.
Direct connections between ordinary mobile phones and satellites could reduce coverage gaps in areas with limited terrestrial infrastructure.
Cheaper and more frequent launches could support broader coverage and higher capacity.
Commercial deployment also requires national spectrum approvals, mobile-carrier agreements, handset compatibility, and sufficient capacity for each service.
Text messaging, voice, and broadband data have different capacity requirements and technical challenges and should not be evaluated as a single market.
Lower launch costs would not necessarily translate into an immediate, proportional reduction in service prices.
Orbital data centers: AI infrastructure potential must be distinguished from commercial validation.
Space-based AI computing may attract interest as launch costs decline and orbital power generation develops.
However, the low ambient temperature of space does not make server cooling inherently easy.
A vacuum prevents convective heat transfer, making thermal-radiation systems essential for rejecting computing equipment’s waste heat.
- Power: Solar generation, storage, and continuity of supply must be secured.
- Heat rejection: Systems must dissipate the waste heat produced by large-scale computing.
- Durability: Radiation and other environmental effects on semiconductors and equipment life must be managed.
- Communications: Ground-to-orbit bandwidth and data-transfer costs must be assessed.
- Maintenance: Equipment repair and replacement are more difficult than on Earth.
The proposed deployment of orbital data-center satellites from 2028 and references to listing documents require verification against original documentation.
For valuation purposes, these concepts are better treated as long-term opportunities contingent on technical and demand validation, rather than as established earnings streams.
6. The Central Question for Tesla Shareholders: Who Receives SpaceX’s Profits?
SpaceX’s success does not automatically create an economic entitlement for Tesla shareholders.
Elon Musk’s involvement in both companies does not give their shareholders identical economic rights.
The source assumes Tesla owns SpaceX shares and discusses a potential merger without providing supporting official disclosures or transaction documents.
The cited shareholdings, valuations, and potential receipt of shares through a merger should therefore not be treated as established facts.
- If equity ownership is officially confirmed: The impact on Tesla’s value can be assessed using the ownership stake, acquisition cost, valuation methodology, and accounting treatment.
- If commercial contracts are confirmed: Transaction size, profitability, and contractual terms determine the economic connection.
- If a merger or share exchange is officially announced: Exchange ratios, valuations, debt, dilution, and approval requirements become central.
- If no direct connection is established: Any effect reflects technological expectations or investor sentiment, not a demonstrated increase in Tesla’s earnings.
The $390 figure referenced in the source headline is not clearly identified as a current market price or an investor’s purchase price.
Even for an investor who bought at $390, the relevant comparison is between expectations embedded in the current valuation and prospective cash flows, rather than the historical purchase price.
7. Tesla Robotaxis: Paid Utilization Matters More Than 24-Hour Availability
The source discusses round-the-clock robotaxi operations across all cities and the number of Cybercabs in service.
These claims require confirmation of official service areas, operating conditions, vehicle definitions, and measurement dates.
Vehicle counts from independent tracking websites may differ from company-disclosed commercial fleet figures.
The underlying economics are straightforward.
Longer operating hours increase the opportunity to generate revenue from each vehicle.
However, 24-hour service availability does not mean a vehicle carries paying passengers for 24 hours.
- Paid utilization: The share of total operating time and distance that generates revenue.
- Empty mileage: Time and costs incurred while traveling without passengers.
- Operating expenses: Charging, cleaning, maintenance, insurance, and customer support.
- Safety operations: Resources required for remote assistance and on-site response.
- Local profitability: Economics shaped by demand density, fares, and regulatory conditions.
Starship and robotaxis share a dependence on the utilization of reusable assets.
However, rockets require demonstrated safe reflights and launch demand, while robotaxis require demonstrated safe autonomous driving and paying-passenger demand.
8. Global Economic Outlook: Interest Rates and the AI Investment Cycle
Assets whose valuations depend heavily on distant earnings, including Tesla and space-industry businesses, can be sensitive to interest rates.
Higher U.S. Treasury yields can increase the discount rate applied to future cash flows and pressure growth-stock valuations.
Market responses nevertheless depend on whether yields are rising because of stronger growth, inflation concerns, or increased Treasury issuance.
U.S. equity analysis should therefore consider corporate earnings and financing conditions alongside the direction of interest rates.
Nvidia’s earnings and major technology companies’ AI investment plans can inform assessments of AI infrastructure demand, but cannot be translated directly into Tesla autonomous-driving profits or orbital data-center revenue.
The source’s Treasury-yield and inflation figures, Federal Reserve personnel and scheduling claims, statements concerning Nvidia executives, and Anthropic listing timeline should not be repeated as current news without verification.
Market-sensitive claims, particularly management changes or allegations of misconduct, require official statements and reliable original reporting.
9. Beyond the Catch: Where Costs Shift
Four issues warrant particular attention in investment analysis.
① Lower internal launch costs are not equivalent to higher external revenue.
When SpaceX launches its own satellites on its own rockets, changes in internal transfer pricing do not increase consolidated external revenue.
Economic value arises when external cash expenditure on constellation deployment falls or the same investment supports more communications-service sales.
Some savings may be reflected in asset costs and subsequent depreciation, creating a timing difference between lower cash expenditure and improved accounting earnings.
② Lower launch costs expose other bottlenecks.
As launch costs decline, satellite production capacity, satellite life, ground networks, spectrum access, and customer acquisition costs may become more significant.
Resolving launch constraints does not automatically establish the profitability of the entire communications business.
③ Reusability includes failure costs and infrastructure-concentration risk.
Counting only maintenance expenditure after successful flights can overstate economic benefits.
Vehicle losses, tower damage, and investigation-related suspensions must be included in long-run average costs.
Tower recovery can simplify logistics, but damage to critical infrastructure could delay multiple missions.
④ Strong technology does not necessarily make an attractive investment.
Rapid technological progress may deliver disappointing investment returns if success is already reflected in a high valuation.
Conversely, slower-than-expected growth may produce a different outcome if the risk is adequately reflected in the purchase price.
The central variables are the scale and timing of cash flows and the price paid for the rights to those cash flows.
10. Monitoring Checklist and Tax Issues for Overseas Equities
- Launch records: Verify upper-stage and booster recovery outcomes separately in official mission reports.
- Actual reflights: Confirm reuse of recovered vehicles, maintenance scope, and reflight intervals.
- Repeated operations: Assess whether performance is sustained across multiple missions.
- Economics: Distinguish launch costs, customer pricing, payload utilization, and vehicle-loss costs.
- Starlink: Monitor paying demand and constellation maintenance investment alongside capacity growth.
- Tesla: Verify equity ownership and commercial relationships through official disclosures.
- Robotaxis: Focus on paid utilization and per-vehicle profitability rather than operating hours alone.
The source’s discussion of a petition concerning taxation of overseas-equity mergers and share exchanges requires separate verification.
The central concern is potential liquidity pressure when investors receive only replacement shares but incur a tax liability without receiving cash.
Actual tax treatment and timing depend on transaction structure and applicable law and require case-specific assessment.
The statement that 4,335 participants represent 81% of a 50,000-person target is mathematically incorrect. The correct figure is approximately 8.7%.
Participation figures and deadlines require confirmation on the official petition page. Meeting participation requirements does not automatically result in legislative change.
< Summary >
- The first documented catch in October 2024 involved a Super Heavy booster. The source’s more recent upper-stage catch claims require separate verification.
- The tenfold launch-cost gap compares an estimate with a long-term target, not an achieved reduction.
- Starship’s economics depend on reflight intervals, maintenance costs, and reuse counts rather than recovery alone.
- Starlink could directly benefit from lower launch costs, but demand and constellation investment remain important.
- Direct-to-cell services and orbital data centers face different regulatory, technical, and commercialization timelines.
- A verified economic connection is necessary for SpaceX’s success to translate into financial benefits for Tesla shareholders.
- The gap between valuation expectations and realized cash flows matters more than the $390 reference price.
[Related Articles…]
*Source: [ 오늘의 테슬라 뉴스 ]
– 스페이스X 우주선 첫 발사탑 포획, 같은 로켓인데 값이 10배 차이 — $390 테슬라 주주는?
● Dollar Empire Cracks, BRICS Gold and Stablecoin Shock
Is Dollar Dominance Eroding? BRICS, the Digital Yuan, Gold, and Bitcoin in the Evolving Monetary Order
A decline in the influence of dollar payment networks is fundamentally different from the dollar losing its reserve-currency status.
Confusing these developments can lead investors to overpay for gold, misclassify Bitcoin as a safe-haven asset, or reduce dollar exposure prematurely.
The key issues are the practical scope of BRICS de-dollarization, the limitations of the digital yuan, the potential for stablecoins to reinforce dollar dominance, and portfolio diversification strategies.
Claims that BRICS has secured 90% of global gold production, that a petrodollar agreement has expired, or that Bitcoin transactions are untraceable require verification.
1. Core Assessment: Functional Diversification Rather Than an Immediate Dollar Collapse
The central issue is not the imminent disappearance of the dollar, but the potential diversification of monetary functions.
Reserve-currency strength depends on more than the volume of cross-border payments processed.
- Pricing: The currency used to price oil, commodities, and goods.
- Trade settlement: The currency used to pay for imports and exports.
- Financing: The currency in which companies and governments borrow.
- Reserve assets: The assets central banks hold for contingencies.
- Collateral and safe-haven assets: The assets financial institutions use to secure funding and manage risk.
Even if yuan settlement expands in certain trade flows, the dollar retains core functions when companies borrow in dollars and central banks hold U.S. Treasuries.
Diversification of settlement currencies does not necessarily imply replacement of the dominant reserve currency.
A more reliable assessment of the global outlook examines changes in individual monetary functions rather than assuming a single outcome of dollar decline.
2. Why Dollar Dominance Is Difficult to Displace
① Network Effects Reinforce Established Usage
Exporters, banks, and commodity traders already structure contracts and risk management around the dollar.
Changing transaction currencies requires adjustments to accounting, trade finance, currency hedging, contractual practices, and settlement accounts.
Marginally lower transfer fees in another currency are unlikely to transform this infrastructure rapidly.
② The Scale and Liquidity of the U.S. Treasury Market
Central banks and large financial institutions need markets that can absorb substantial capital and support relatively rapid asset sales.
U.S. Treasuries serve both as foreign-exchange reserve investments and as core collateral in international financial markets.
A potential dollar alternative requires not only efficient payment technology but also a deep market for investable assets denominated in that currency.
③ Financial Openness and Crisis-Response Capacity
Investors value the ability to withdraw capital as much as the ability to invest it.
Legal protections, capital mobility, foreign-exchange liquidity, and central-bank crisis-response mechanisms collectively support confidence.
Demand for dollar funding can surge even when a crisis originates in the United States. U.S. economic stress therefore does not automatically imply dollar depreciation.
④ Dollars Are Also Created and Circulated Outside the United States
U.S. trade deficits are an important channel through which dollars reach overseas markets.
However, dollar lending and deposits at banks outside the United States, together with international capital transactions, also contribute to dollar liquidity.
Claims that a trade-surplus country cannot issue a reserve currency, or that yuan cannot be supplied outside China, are therefore overly simplistic.
China can supply yuan through overseas lending, investment, and currency swaps. Financial openness and institutional credibility remain critical constraints.
3. BRICS De-Dollarization: Reducing Sanctions Exposure Rather Than Replacing the Dollar
A major objective of non-dollar settlement among BRICS members is to reduce dependence on specific currencies and financial networks.
Greater exposure to financial sanctions or reserve-asset freezes encourages governments to develop alternative settlement channels and diversify reserve holdings.
① Expanding Local-Currency Settlement
Trading partners can reduce some conversion and intermediation requirements by settling transactions in their own currencies rather than dollars.
Persistent trade imbalances, however, can leave exporters accumulating the importing country’s currency.
If that currency offers limited purchasing or investment opportunities, exporters may demand a more widely usable currency or another settlement mechanism.
A currency accepted for payment is not necessarily a currency investors want to hold.
② Developing Alternative Financial Networks
China’s CIPS supports cross-border yuan clearing and settlement.
Direct comparisons with SWIFT can be misleading because the systems perform different functions.
SWIFT primarily transmits financial messages, while CIPS provides yuan clearing and settlement functions and also has connections with SWIFT.
CIPS expansion therefore does not constitute a complete replacement of SWIFT.
③ BRICS Expansion and Monetary Integration Are Separate Issues
A larger membership and partner network can expand trade links.
However, differences in U.S. relations, exchange-rate policies, capital controls, and inflation create divergent incentives regarding a common currency.
Claims that BRICS exceeds the G7 in economic size require clarification of purchasing-power-parity versus nominal-dollar measures and the membership included.
Economic scale alone does not establish international financial credibility or market liquidity.
4. The Digital Yuan, CBDCs, and mBridge: Technology Competition Is Not Currency Competition
① The Digital Yuan Is a Digital Form of China’s Currency
The digital yuan is a central bank digital currency, or CBDC.
Its issuer and legal status differ from payment services such as Alipay and WeChat Pay.
Adoption nevertheless requires sufficient benefits for users who already have convenient payment options.
The interview states that China decided to pay interest on digital yuan held in personal wallets.
Earlier designs emphasized its role as non-interest-bearing digital cash. Any change in 2026 requires confirmation through official People’s Bank of China announcements and the applicable scope.
Specific trials or incentives offered by operating institutions should not be interpreted as system-wide policy changes.
② Cross-Border CBDCs Could Reduce Settlement Steps
Connecting multiple central bank digital currencies could reduce intermediation and shorten settlement times.
mBridge has tested this model for cross-border payments.
However, technical settlement within seconds differs from the total time needed for currency conversion, compliance checks, and withdrawal.
Actual costs depend on transaction size, foreign-exchange spreads, liquidity, and regulatory compliance.
Attributing the Bank for International Settlements’ departure from the project solely to concerns that it favored the yuan requires a distinction between verified facts and interpretation.
③ Quantum Cryptography Does Not Guarantee Absolute Security
Technologies such as quantum key distribution can strengthen security on specific communication links.
They do not eliminate vulnerabilities in user devices, wallets, authentication systems, administrator privileges, or software.
Claims that all international digital-yuan transactions use quantum-secured networks also require independent verification.
Advanced security technology does not make an entire financial system immune to attack.
5. The BRICS Unit and Gold Purchases: Distinguishing Formal Arrangements from Proposals
① Has a 40% Gold, 60% Currency-Basket Structure Been Adopted as an Official Common Currency?
The interview describes a BRICS Unit combining gold and a basket of BRICS currencies.
Such proposals or reported trials should not be equated with a currency jointly approved by all BRICS members and issued by their central banks.
Assessing operational status requires verification of the following:
- Are the issuer and legal responsibilities clearly defined?
- Are member governments and central banks officially participating?
- Where is the gold held, and is it independently audited?
- Do holders have enforceable rights to redeem for gold or other currencies?
- Are issuance volumes and currency-basket valuation methods disclosed?
Commemorative banknotes or currency models displayed at conferences do not establish the issuance of legal tender or the formal adoption of a settlement unit.
Monetary expansion by a country represented in the basket would not automatically increase the supply of the common unit.
That would depend on separate issuance rules and collateral requirements.
② Why Central Banks Purchase Gold
Gold is not a liability of a sovereign issuer or financial institution.
Physical gold held domestically has a different sanctions and custody risk profile from assets held in overseas financial accounts.
Risk reduction and portfolio diversification therefore contribute to central-bank gold purchases.
Not every purchase signals an abandonment of the dollar or a return to the gold standard.
③ Claims That BRICS Has Secured More Than 90% of Global Gold Production Require Caution
Gold demand includes jewelry, private investment, and industrial use as well as central-bank purchases.
Interpreting total national gold demand as central-bank reserve accumulation can materially overstate official purchases.
New mine production and recycled gold supply are also separate categories.
The interview’s figures of 29,000 tonnes and 90% should not inform investment decisions without verification of the period, countries covered, inclusion of private demand, and whether the figures represent net purchases.
④ Higher Gold Holdings by Value Do Not Necessarily Indicate Additional Purchases
The value of central-bank gold holdings can rise through price appreciation alone.
Claims that gold holdings have exceeded U.S. Treasury holdings require clarification of the institutions covered, valuation methodology, and contribution from higher gold prices.
6. Statistical and Terminological Claims Requiring Correction
| Claim or Expression | Appropriate Interpretation |
|---|---|
| U.S. Treasuries account for 56% of global foreign-exchange reserves. | The dollar-denominated share of foreign-exchange reserves differs from the share invested in U.S. Treasuries.Dollar reserve assets can include deposits and various securities. |
| Dollar M2 or total issuance is approximately $7 trillion. | M2, currency in circulation, the monetary base, and offshore dollar credit are distinct measures.The definition and reference date require verification. |
| Yuan transactions have overtaken dollar transactions on CIPS. | CIPS is a yuan settlement infrastructure.The cited share must first be identified as a measure of China’s cross-border receipts and payments or of global payments. |
| China purchases all its oil in yuan. | Growth in yuan-settled transactions does not establish that all oil imports are settled in yuan.Evidence covering the total import share is required. |
| A 50-year petrodollar agreement has expired. | The claim that a 50-year agreement requiring Saudi Arabia to sell all oil exclusively in dollars has expired lacks substantiated evidence.U.S.-Saudi cooperation must be distinguished from dollar-based oil-market practices. |
| Russia’s foreign-exchange reserves were confiscated. | Asset freezes, confiscation of principal, and the use of income generated by frozen assets are legally distinct.Treating them as interchangeable is inaccurate. |
| The United States cannot trace Bitcoin transactions. | Bitcoin transactions are recorded on a public ledger.Address analysis and exchange records can support tracing; sanctions evasion is not guaranteed. |
| Approximately 10% of South Korean exports are settled in stablecoins. | This estimate lacks verified official support.Changing the payment method does not eliminate export declarations or customs and foreign-exchange obligations. |
Russia’s authorization of crypto mining and international crypto payments also requires distinctions by date and scope.
Relevant legislation progressed before the 2024 Kazan summit. Describing it as a sudden authorization of all transactions following a summit agreement is inaccurate.
7. A Critical Counterpoint: Stablecoins Could Reinforce Dollar Dominance
Bypassing banks does not necessarily mean bypassing the dollar.
This distinction is central to the de-dollarization debate.
When users replace bank transfers with dollar-linked stablecoins, the payment channel changes, but the unit of value remains the dollar.
① Moving Outside Banking Networks Is Not the Same as Moving Away from the Dollar
Adoption of dollar stablecoins in economies with unstable domestic currencies could expand digital dollar usage.
Banks may lose remittance income or deposits, while the dollar’s role as a unit of account strengthens.
② Reserve Management Can Support Demand for U.S. Treasury Bills
Where issuers hold U.S. Treasury bills as reserves, stablecoin growth can support demand for those securities.
However, reallocations from existing dollar products must be distinguished from genuinely incremental demand.
Stablecoin growth would not automatically resolve U.S. fiscal challenges.
③ Yield-Bearing Products Require Analysis of the Underlying Risk
Interest on stablecoin holdings, exchange rewards, lending income, and returns from tokenized Treasury funds are different sources of yield.
Regulatory rules and legislative scope vary across jurisdictions. Broad claims that the United States and Europe prohibit interest while other regions permit it are insufficiently precise.
Depending on their legal structure, tokenized Treasury products may constitute fund shares or securities rather than cash equivalents.
Redemption schedules, investor eligibility, fees, and liquidity restrictions can prevent immediate conversion into cash at par.
8. U.S. Fiscal Risk: Indicators Beyond Treasury Issuance Shares
Rising U.S. fiscal deficits and interest costs are important risks for the dollar and bond markets.
However, the claim that short-term securities account for 70% of issuance does not by itself establish an inability to obtain long-term funding.
① Gross Issuance and Outstanding Debt Are Different Measures
Short-term securities can refinance the same principal several times in one year, increasing their share of gross issuance.
A high share of gross issuance therefore does not necessarily mean an equally high share of outstanding debt.
② Gross and Net Interest Costs Also Differ
Annual interest comparisons must distinguish gross interest costs from net interest outlays, which reflect adjustments including transactions within government.
Fiscal-year definitions and forecast dates can also change figures such as projections for 2030.
③ Indicators to Monitor
- The short-term share of outstanding Treasury debt and average maturity.
- Net interest outlays relative to government revenue.
- Treasury auction demand and auction yields.
- The term premium embedded in long-term yields.
- Inflation expectations and inflation-adjusted real yields.
Higher Treasury yields do not invariably weaken the dollar.
Rising yields can attract dollar demand, while increases driven by deteriorating fiscal confidence may produce a different response.
Exchange-rate analysis must consider why interest rates move, not only their direction.
9. Gold, Bitcoin, and Dollar Assets: Portfolio Implications
The debasement trade describes demand for scarce assets driven by concerns about declining currency purchasing power and deteriorating fiscal credibility.
Gold and Bitcoin nevertheless have different investment characteristics.
| Asset | Potential Portfolio Role | Principal Risks |
|---|---|---|
| Gold | Diversification against weakening monetary confidence and geopolitical risk. | No interest or dividends; exposure to price corrections, currency movements, and storage costs. |
| Bitcoin | Selective exposure to a digital asset with predefined supply rules. | High volatility and potential declines alongside equities during risk-off periods. |
| Dollar Cash and Cash Equivalents | Funding dollar expenses and maintaining liquidity during crises. | Currency losses when the Korean won strengthens, with credit and redemption risks varying by product. |
| Long-Term U.S. Treasuries | Potential protection during economic slowdowns and falling interest rates. | Material price sensitivity to inflation and rising long-term yields. |
| Global Equities | Participation in corporate earnings growth and productivity gains. | Exposure to economic cycles, valuations, sector concentration, and exchange rates. |
| Stablecoins and Tokenized Products | Digital payments and access to selected financial products. | Issuer, reserve-asset, custody, depegging, cybersecurity, and legal-rights risks. |
For individual investors, assigning distinct roles to assets is more practical than concentrating on a dollar-collapse scenario.
- Secure liquidity for living costs and planned expenses first.Hold won liquidity for won-denominated spending and separately address overseas tuition or other dollar obligations.
- Define gold’s diversification role before investing.Assess its portfolio function and tolerable price volatility rather than buying solely in response to rising prices.
- Manage Bitcoin separately from gold as a high-risk asset.Limit exposure to a level at which a sharp decline would not impair living standards or long-term plans.
- Diversify assets and entry points.Staged purchases and periodic rebalancing can reduce dependence on a single forecast.
- Exercise particular caution with leverage.Interim volatility can force losses even when the longer-term directional view proves correct.
Appropriate allocations depend on investment horizon, debt, income stability, and loss tolerance. No single allocation is universally suitable.
10. AI and Real-World Asset Tokenization: Better Access Does Not Eliminate Risk
① Tokenization Digitally Represents Assets and Enables Their Transfer
Real-world asset tokenization represents rights to assets such as bonds, funds, and real estate through blockchain-based tokens.
It can expand fractional investment and automate settlement, although fractional ownership does not inherently require blockchain.
The ability to transfer tokens around the clock does not guarantee continuous trading or redemption of the underlying assets at fair value.
Liquidity depends on investor participation, market makers, redemption terms, and the operating hours of the underlying markets.
② AI Can Reduce Complexity in Currency Selection and Treasury Management
AI agents can compare payment costs and exchange rates, forecast corporate cross-border cash flows, and assist with capital allocation within predefined rules.
These are potential applications, not evidence that unrestricted automated trading across all currencies is already universally available.
③ Permissions and Accountability Remain Essential
Greater automation increases the importance of controls against incorrect transfers, compromised wallet permissions, and repeated transactions based on faulty decisions.
Investors and companies should assess transaction limits, approval procedures, audit trails, and responsibility for losses alongside new functionality.
11. Structural Implication: Monetary Competition May Have Multiple Winners
Several structural distinctions are particularly important.
First, the leading payment network and the leading currency may differ.
A new blockchain payment network can expand while dollar stablecoins remain its most widely used assets.
Second, weaker bank competitiveness does not necessarily imply weaker U.S. monetary influence.
Greater dollar use outside banks can extend the currency’s reach even as financial intermediation changes.
Third, redemption rights matter more than a gold-backed label.
Safety depends on verified gold holdings, audits, ownership rights, and redemption procedures, not branding alone.
Fourth, national rules continue to constrain individual currency choices.
Tax-payment requirements, capital controls, foreign-exchange reporting, and legal-tender frameworks prevent monetary outcomes from being determined solely by consumer preferences.
Fifth, a declining dollar market share can coexist with rising dollar usage.
If global financial activity grows faster, the dollar’s share can fall while its absolute transaction volume increases.
Market share alone is therefore insufficient evidence of a collapse in dollar dominance.
12. Indicators and Official Sources to Monitor
Consistent monitoring of comparable indicators provides a stronger basis for evaluating change than headline-driven forecasts.
- Reserve-currency composition: Track dollar and yuan shares in IMF COFER data while accounting for exchange-rate valuation effects.
- International currency usage: Treat BIS foreign-exchange statistics, SWIFT data, and China’s cross-border payment statistics as distinct measures.
- Gold demand: Separate central-bank net purchases, private investment, and jewelry demand in World Gold Council data.
- U.S. public finances: Review debt maturity structure, net interest outlays, and fiscal projections from the U.S. Treasury and Congressional Budget Office.
- Digital currencies: Distinguish trials, limited operations, and nationwide implementation in official central-bank announcements.
- BRICS arrangements: Differentiate proposals and requests for further study from formal agreements and operational implementation in summit declarations.
- Stablecoins: Examine reserve composition, the scope of independent verification, redemption terms, and regulatory coverage.
The priority is a portfolio capable of withstanding different economic conditions, rather than correctly identifying the next dominant reserve currency.
A balanced approach recognizes the dollar’s strengths, evaluates gold and non-dollar assets as diversifiers, and weighs digital finance’s efficiency gains against its additional risks.
< Summary >
- De-dollarization may advance, but diversified trade settlement does not imply an immediate loss of the dollar’s reserve-currency status.
- BRICS initiatives and the digital yuan depend on financial openness, credibility, investable assets, and redeemability as well as technology.
- Claims concerning the BRICS Unit, gold purchases, the petrodollar agreement, and crypto traceability require verification.
- Dollar stablecoins can bypass traditional banking networks while expanding dollar usage.
- Gold and Bitcoin have different risk profiles. Diversification and liquidity management take priority over concentrated exposure to a single forecast.
- AI and tokenization can improve financial access but do not eliminate legal, redemption, cybersecurity, or liquidity risks.
[Related Articles…]
*Source: [ Jun’s economy lab ]
– 미국 달러 ���권이 무너지고 있습니다. 이 자산을 준비하세요(ft.홍익희 작가 1부)