● Dollar Power Grab, AI Money Shift, Stablecoin Shock
The Real Reason the U.S. Is Pushing Stablecoins: AI Agents, RWA Tokenization, Dollar Dominance, and FX Dynamics Will Change at Once
The core issue is not simply that the United States “likes crypto.”
The U.S. is seeking to extend dollar dominance into the digital economy through stablecoins, while using RWA tokenization to bring capital markets such as equities, bonds, and money market funds on-chain.
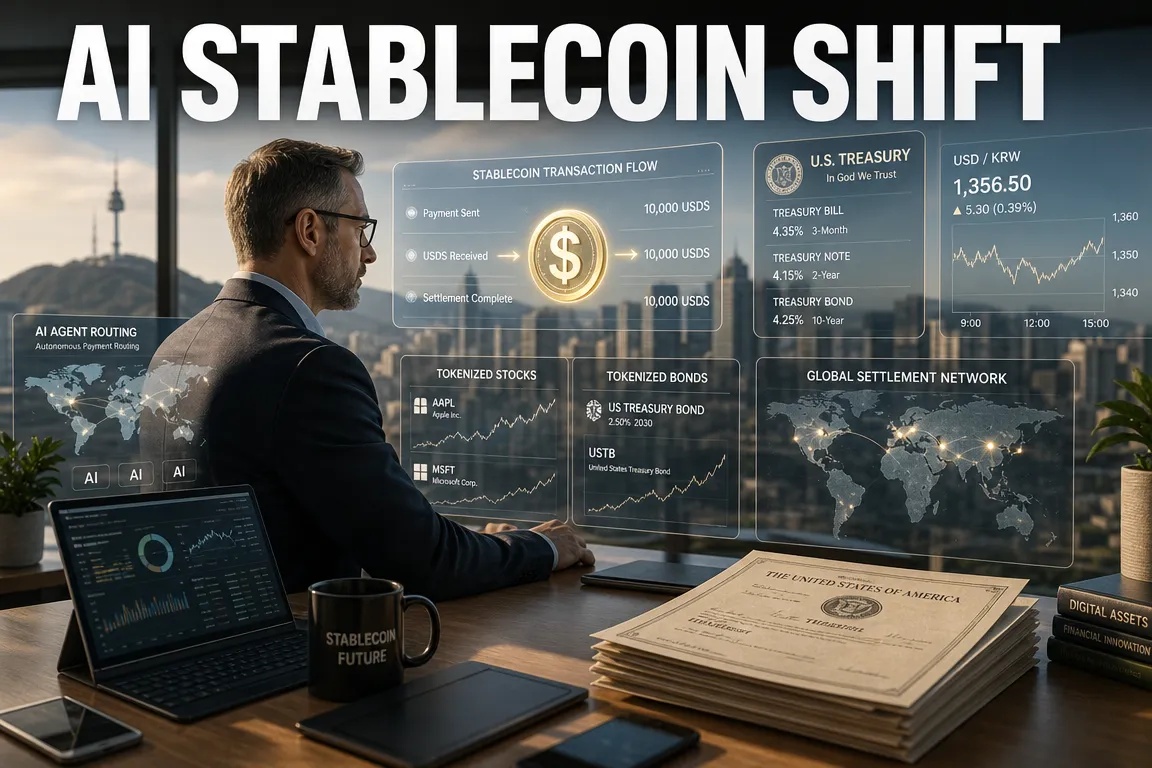
If AI agents begin to make payments and investments on behalf of users, stablecoins may expand beyond human payments into machine-to-machine money.
For South Korea, this could translate into Korean won weakness, stronger dollar preference, and a changed outlook for exchange rates.
This report examines why the U.S. is promoting stablecoins despite internal resistance, why the SEC is signaling regulatory easing, how AI agents are linked to digital assets, and what risks this creates for the Korean economy and the won.
1. The U.S. Stablecoin Strategy Is About Expanding the Dollar System, Not Just Supporting Crypto
The U.S. is advancing stablecoins under the banner of digital asset industry development.
At a deeper level, the objective is to make the dollar the default settlement unit of the digital economy.
Stablecoins are typically pegged 1:1 to the U.S. dollar.
As global users adopt dollar stablecoins, dollar usage increases within digital environments.
For the U.S., this creates several advantages.
Stablecoin growth can increase demand for dollars, encourage issuers to hold U.S. Treasuries as reserve assets, and reinforce the influence of U.S. financial markets.
This is why U.S. policymakers are seeking to bring the market into the regulated system despite internal opposition.
2. Genius Act, Clarity Act, and the SEC’s Preemptive Moves
The original text notes that the Trump administration moved quickly to pass the Genius Act to support stablecoin growth.
By contrast, the Clarity Act did not advance as smoothly, and the SEC later appeared to signal support through measures resembling innovation exemptions.
The key interpretation is that the SEC has already taken much of the action it can take on its own.
The SEC is traditionally strict on market manipulation, volatility, and investor protection.
The United States has one of the strongest regulatory frameworks for equities markets.
Against that backdrop, the SEC’s apparent openness to digital assets, on-chain finance, and RWA tokenization suggests more than simple deregulation.
It may reflect a view that the existing capital market structure alone may not be sufficient to preserve U.S. financial leadership.
The original text also places the relevant legislation in a political context.
If the Trump administration and Republicans lose momentum after the November 2026 midterm elections, SEC policy support could weaken.
This may explain why the SEC appears to be moving quickly on innovation-related measures now.
3. The Current Limitation of Stablecoins: Spendable Use Cases Remain Narrow
Stablecoins are already the most widely used settlement instrument in the crypto market.
However, most current use cases remain concentrated in crypto trading.
The original text suggests that more than 90% of stablecoin usage still relates to cryptocurrency transactions.
There are cases of use in payments and remittances in certain regions, including parts of Latin America, but these remain limited relative to the overall financial system.
The key question is what stablecoins must be able to buy for the market to expand further.
The answer is financial assets.
Equities, bonds, money market funds, tokenized real estate interests, private funds, commodities, and other real-world assets must move on-chain.
This is the core of RWA tokenization.
Stablecoins today are primarily a means to trade crypto assets. In the future, they could serve as the base currency of an on-chain capital market.
If this shift materializes, stablecoins could extend beyond crypto trading into U.S. equities, bond markets, and global asset management.
4. If RWA Tokenization Expands, Capital Markets Move from Exchange-Centric to On-Chain-Centric
RWA refers to Real World Assets.
RWA tokenization means converting real assets such as equities, bonds, real estate, and money market funds into tokens that can be traded on blockchain networks.
This matters because it can change the structure of capital markets.
In the traditional system, investors need brokerage accounts, exchanges, clearing, and settlement infrastructure.
In on-chain finance, assets and settlement can move simultaneously.
Trading can become 24/7, and cross-border capital movement can become significantly faster.
For the U.S., this would make it easier for global investors to purchase U.S. assets with dollar stablecoins.
If U.S. equities, U.S. Treasuries, and U.S. money market funds are tokenized and distributed globally, the U.S. can absorb even larger volumes of global capital.
This is a major reason the U.S. is pushing stablecoins and RWA tokenization together.
5. In the AI Agent Era, Stablecoins Could Become Machine Money
The most important point in the original text is the connection between AI agents and stablecoins.
Until now, stablecoins have been viewed as money used by people for payments and investing.
Going forward, AI agents may increasingly manage money, execute payments, and invest on behalf of users.
For example, a user might instruct an AI agent to manage 10 million won according to a specific risk profile.
The AI agent could analyze market data, trade assets, monitor returns, and reallocate capital as needed.
Under current financial infrastructure, such automated machine-to-machine transactions remain highly constrained.
Bank accounts, brokerage accounts, identity checks, operating hours, and cross-border transfer rules all create friction.
Stablecoins, by contrast, are programmable money.
AI agents can be designed to make payments or investments automatically when predefined conditions are met.
For this reason, stablecoins are increasingly viewed as a suitable monetary instrument for the AI era.
The transaction volume generated by machines could be far larger than that generated by humans.
If AI agents begin reallocating assets, making payments, and purchasing services at machine speed, stablecoin demand could rise materially.
6. The Next Stage of Robo-Advisory Is a Personalized AI Investment Agent
Robo-advisory services are already commercially available.
Many investors already receive automated portfolio management based on their risk profile.
However, current robo-advisory systems usually operate within frameworks designed by financial institutions.
In the next stage, individuals may directly configure AI investment agents that allocate capital using on-chain financial products.
This requires programmable money.
If AI is to move freely among equity tokens, bond tokens, money market fund tokens, digital assets, and cash equivalents, the payment rail must also be digitally native.
Bank transfers and card payments are unlikely to match this speed.
As AI-driven investment grows, the integration of stablecoins and tokenized assets is likely to become more natural.
7. Why Central Banks Are Uncomfortable with Stablecoins
Stablecoins are not necessarily welcome from a central bank perspective.
The reason is straightforward.
They function like money outside traditional control channels.
Central banks conduct monetary policy through interest rates, reserve requirements, and open market operations.
If privately issued stablecoins become widely used, parts of the money flow may move beyond direct central bank control.
This can weaken the transmission of monetary policy.
The Federal Reserve may also find it difficult to fully embrace stablecoins in principle.
Even so, the U.S. appears to believe that the national benefits outweigh the control risks.
The calculation is that regulatory oversight can manage reserve risks and issuance quality while still capturing the benefits of dollar expansion.
8. If the Payments Market Changes, the Impact Will Be Broader Than in Capital Markets
Capital market changes are likely to be felt first by equity investors and financial professionals.
Payments market changes, by contrast, affect nearly everyone.
Consumption accounts for roughly 70% of U.S. GDP.
Consumption is also a major component of the Korean economy.
A change in payment rails does not simply mean replacing cards with crypto.
It also affects spending data, exchange-rate conversion, cross-border transaction costs, platform fees, and household financial behavior.
For example, when buying goods on overseas platforms today, consumers face a mix of won-denominated card payments, dollar conversion, card fees, and exchange-rate volatility.
If dollar stablecoin payments become common, consumers may increasingly think in dollar terms.
If the won is perceived as structurally weakening over time, consumers may prefer dollar-based assets over the won.
This is not only a payments shift. It is a shift in currency preference.
9. For South Korea, Exchange Rates Are the Most Sensitive Issue
The original text places particular emphasis on the effect of dollar stablecoins on the Korean won.
One might assume South Korea can simply issue won stablecoins in response.
In practice, the situation is not that simple.
The dollar has a decisive advantage in global liquidity, trust, use cases, and access to financial products.
Corporate behavior matters as well.
Companies such as Samsung Electronics and SK Hynix receive export proceeds in dollars.
If firms expect the won to weaken further, they may delay converting dollars into won.
That behavior is rational at the corporate level.
At the economy-wide level, however, it can reduce demand for the won and reinforce dollar preference.
Households may behave similarly.
If dollar stablecoins are more convenient and better for preserving value, the share of won usage may decline.
As a result, exchange-rate analysis in the stablecoin era becomes more complex than simple interest rate or trade balance models.
Digital dollar usage, on-chain capital movement, and AI-driven payment demand must also be considered.
10. The More Important Question Than a “Won Stablecoin” Is How to Preserve Won Usage
For South Korea, the issue is no longer whether to adopt stablecoins.
The global trend is already moving toward dollar stablecoins.
The more practical question is how to reduce the tilt toward dollar stablecoins and expand the use of digital won.
This is where won stablecoins, deposit tokens, central bank digital currency, and bank-led payment infrastructure all become relevant.
The Bank of Korea’s deposit token initiative should be viewed in this context.
If a won-based digital payment instrument is not sufficiently convenient, secure, and broadly usable, the market may naturally move toward the dollar.
This becomes even more important when AI agents and on-chain finance are combined.
If won-based digital money cannot match the speed of that environment, dollar-based digital finance may expand even within Korea.
11. The Core Point Missing from Most Coverage: The U.S. Is Preparing for Machine Finance, Not Just Human Finance
Many reports frame stablecoins only as payment tools or crypto trading instruments.
The deeper issue is that AI agents may become economic actors.
Humans may make a few payments or investment decisions per day.
AI agents can make thousands of incremental decisions automatically.
For example, they can charge devices during low-cost electricity periods, move cash into short-duration MMF tokens with higher yields, execute cross-border payments when exchange rates are favorable, and rebalance budgets based on spending patterns.
All of this requires a payment instrument that is fast, borderless, and programmable.
At present, dollar stablecoins are the leading candidate.
For this reason, the U.S. stablecoin strategy is not only about expanding the current crypto market.
It may also be an attempt to make the dollar the operating language of future AI-driven commerce.
12. Why the Stablecoin Market Has Stalled and What Needs to Change for the Next Phase of Growth
The original text notes that stablecoin market capitalization has grown rapidly and then plateaued.
The text refers to 300 million, but in market context this appears to mean roughly $300 billion.
The key question is why the market has not expanded further.
The answer is straightforward.
There are still too few goods, services, and financial assets that can be purchased with stablecoins.
Today, they are mainly used to buy crypto assets.
But if tokenized equities, tokenized bonds, on-chain money market funds, AI asset management services, automated subscription payments, and global remittance services expand, the picture changes.
As stablecoin use cases widen, market capitalization is likely to grow accordingly.
In other words, the next phase of stablecoin growth will not depend only on regulatory approval.
The real driver will be how quickly financial products and services usable with stablecoins are introduced.
13. Key Items Investors Should Monitor
-
First, the direction of SEC digital asset policy.
Innovation exemptions, small-scale licensing, and on-chain finance experiments will shape the pace of adoption.
-
Second, the progress of U.S. legislation.
Genius Act, Clarity Act-related bills, and post-midterm political conditions could determine how quickly stablecoin policy advances.
-
Third, the speed of RWA tokenized product launches.
Stablecoin demand will only scale materially if major financial products such as equities, bonds, and money market funds move on-chain.
-
Fourth, the commercialization of AI agent financial services.
Personalized AI investment bots and automated payment agents could increase demand for programmable money.
-
Fifth, the trend in the won-dollar exchange rate and dollar preference.
As dollar stablecoin usage increases, structural pressure on the Korean won may intensify.
14. The Message for the Korean Economy
South Korea should not treat stablecoin policy as a narrow virtual asset regulation issue.
The topic is linked to capital market competitiveness, confidence in the won, exchange-rate stability, and AI financial infrastructure.
The U.S. is attempting to establish dollar stablecoins as the standard infrastructure for global digital finance.
If Korea fails to respond, part of domestic consumption, investment, and corporate settlement activity could migrate to dollar-based digital rails.
That would reduce the use cases for the won and increase dependence on the dollar.
Accordingly, South Korea should view won stablecoins and deposit tokens not as experiments, but as issues of monetary sovereignty in the digital era.
As AI agents automate payments and investment, money’s convenience, speed, and programmability may become sources of national competitiveness.
15. Conclusion: The U.S. Stablecoin Strategy Is the Next Version of Financial Dominance
The U.S. is pushing stablecoins for a clear reason.
It wants to extend dollar dominance from offline finance to online finance, and then to a machine economy driven by AI agents.
RWA tokenization may become the infrastructure that makes U.S. capital markets easier to access globally.
AI agents may become a major source of stablecoin demand.
Dollar stablecoins could become the settlement layer for all of these developments.
For South Korea, the result may be weaker demand for the won, higher exchange-rate volatility, and stronger dollar preference.
Future macro analysis will need to go beyond interest rates, inflation, and employment data.
Stablecoins, RWA tokenization, AI agents, digital asset regulation, and exchange rates must be assessed as one connected framework.
< Summary >
The U.S. is promoting stablecoins not simply to support the crypto industry, but to extend dollar dominance into the digital economy.
Stablecoins are now mainly used for crypto trading, but RWA tokenization could expand their role into equities, bonds, and money market funds.
If AI agents begin to make payments and investments on behalf of users, stablecoins could evolve into programmable money used by machines.
For South Korea, broader adoption of dollar stablecoins could reduce won usage and add upward pressure to exchange rates.
The key question is no longer whether to block dollar stablecoins, but how quickly digital won usage can be built.
[Related Articles…]
- Stablecoin Market Structure and the Next Phase of Digital Finance
- AI Agents and the Future of Automated Finance
*Source: [ 경제 읽어주는 남자(김광석TV) ]
– 미국이 스테이블코인을 밀어붙이는 이유…자본시장까지 통째로 바뀐다 | 경읽남과 토론합시다 | 3자토론 정구태x김동환x김광석 [2편]
● China EV Meltdown, Korea Battery Surge
China EV Quality Risks and the Opportunity for Korea’s Battery Leaders: What the Market Is Overlooking
The key issue is not simply that “Chinese EVs are breaking down.”
It is necessary to view this through the lens of intensifying competition in China’s EV market, quality control failures, battery industry restructuring, and the potential emergence of new leading candidates in the Korean equity market.
In particular, the cases cited in the video, such as brake pedal failures and rear axle separation, symbolize the limits of an industry that cannot sustain growth through price competition alone.
When this is connected to the investment logic that shares can rise sharply when EPS growth accelerates, the perspective on the global economic outlook and the EV value chain changes materially.
1. China’s EV breakdown controversy: not a simple accident, but an industrial structure issue
The video first highlighted quality risks among Chinese EV manufacturers.
It cited cases involving repeated brake pedal failures and a rear axle detachment incident in Malaysia.
These issues extend beyond individual vehicle defects and affect confidence in the EV market as a whole.
- Brake pedal failure is a critical safety defect.
- Rear axle detachment raises concerns over vehicle design, component quality, and assembly processes.
- Although EVs have fewer parts than internal combustion vehicles, the quality of batteries, motors, and vehicle control systems is far more important.
- As firms under price pressure focus on cost reduction, quality risks may increase.
China’s EV industry has grown rapidly on the back of government subsidies, a large domestic market, and aggressive price cuts.
However, the speed of expansion has outpaced technology validation and quality control at many companies.
The view that weaker Chinese EV makers will ultimately be forced out reflects this structural issue.
2. Why the risk of Chinese EV company failures is rising
The number of companies in China’s EV market is excessive.
EV demand continues to rise, but the market cannot support all players.
As the industry matures, firms lacking brand trust, battery stability, software quality, and global certification capabilities may be eliminated quickly.
- First, intense price competition is eroding profitability.
- Second, repeated quality incidents are undermining brand trust.
- Third, overseas expansion may encounter safety regulations and certification barriers.
- Fourth, companies with weak battery supply chains and limited access to core components face rising cost pressure.
- Fifth, higher interest rates and slower growth may force weaker firms out first.
The view that Chinese EV companies may fail in large numbers is not merely pessimistic.
It reflects the normal transition into a restructuring phase after an early growth cycle.
The smartphone market followed a similar pattern, with many brands disappearing before the industry consolidated around a few leaders.
The EV industry is likely to undergo a similar process.
3. The real focus in the EV market is not sales volume, but survival potential
Many investors focus only on EV sales volume.
However, a more important metric is now emerging.
That metric is survival potential.
- Even high unit sales cannot offset sustained losses.
- Battery defects and safety incidents can generate costs greater than sales growth.
- Companies lacking software updates, autonomous driving features, and vehicle data management capabilities will lose competitiveness over time.
- Recalls in global markets can rapidly weaken corporate balance sheets.
EVs are not simply a manufacturing business.
They are a complex industry combining batteries, semiconductors, AI software, autonomous driving, and energy storage systems.
Accordingly, automaker competitiveness cannot be judged on vehicle price alone.
Quality control, supply chain stability, and data-driven vehicle control technology must also be considered.
4. What this means for Korea’s battery and 2nd battery industries
Quality issues among Chinese EV makers may have both negative and positive implications for Korea’s battery sector.
In the short term, concerns over weaker Chinese EV demand could weigh on sentiment.
However, over the medium to long term, the value of battery companies with proven quality and safety may become more visible.
- If Chinese firms lose pricing power, Korean battery companies may regain bargaining leverage.
- In North American and European markets, where safety and certification are critical, Korean firms may retain a premium position.
- After industry restructuring, surviving automakers are likely to place greater value on stable battery suppliers.
- Selective opportunities may also emerge for materials companies, including cathodes, anodes, electrolytes, and separators.
The key point is that this is not a broad-based rally for all battery-related companies.
The market is likely to reward only firms with confirmed earnings, strong customers, and technological competitiveness.
In other words, the investment case for batteries is shifting from theme-driven speculation to earnings-based selection.
5. Why shares can surge when EPS growth accelerates
The latter part of the video offered an important investment clue.
It noted that share prices can rise sharply when EPS growth accelerates.
EPS stands for earnings per share.
In simple terms, it shows how much profit a company generates per share outstanding.
- Rising EPS indicates stronger earnings power.
- When EPS growth accelerates, the market tends to re-rate the company as a growth stock.
- Upward revisions to earnings estimates often attract institutional and foreign capital.
- Share price gains then reflect earnings improvement rather than pure expectation.
This is how leading stocks typically emerge.
At first, the market does not fully recognize them.
But once quarterly results improve, forward guidance strengthens, and analyst estimates are revised upward, shares begin to move decisively.
At that stage, EPS growth becomes the key signal.
6. What it means for a Korea-based global leader to emerge
The original discussion referred to the emergence of a “world-class leading stock” in Korea.
However, since no specific company was clearly identified, it is more appropriate to focus on the conditions required for leadership rather than naming a stock.
- The company should be rapidly gaining global market share.
- EPS growth should be structurally improving.
- The company should be aligned with an industry, not just a temporary theme.
- It should be linked to long-term growth sectors such as AI, EVs, batteries, semiconductors, or power infrastructure.
- It should combine export competitiveness with technological barriers to entry.
In the Korean equity market, leading stocks typically emerge in line with global industry cycles.
Examples include the semiconductor supercycle, the battery rally, the shipbuilding recovery, and the expansion in defense exports.
Going forward, even in periods of slower global growth, companies with rising earnings are likely to attract market attention.
7. Key indicators investors should monitor now
From an investment perspective, the China EV issue should not be viewed simply as bad news about Chinese firms.
The more important question is which industries and companies may benefit from the disruption.
- First, confirm whether EPS growth is actually improving.
- Second, look at operating margin improvement, not just revenue growth.
- Third, check whether the customer base includes global tier-one companies.
- Fourth, assess whether the company has sufficient technology to withstand Chinese price competition.
- Fifth, review debt levels and cash flow stability.
In a high-rate environment, growth stocks without earnings remain vulnerable.
By contrast, companies with rapidly improving earnings can still be favored by the market.
At this stage, “good numbers” matter more than “good industries.”
8. The core point other reports often miss
The most important point in this issue is not the breakdown itself.
The real issue is that the basis of competition in the EV industry is changing.
- Previously, the standard was who could manufacture at the lowest cost.
- Now, the standard is who can deliver safe and durable vehicles.
- Going forward, the key may be who can integrate batteries, software, and AI-based control systems most effectively.
EVs are becoming more like smartphones in their reliance on software updates.
Autonomous driving, battery management systems, and driver-assistance systems are all tied to AI technology.
Accordingly, future competitiveness in EVs will not be determined by body manufacturing alone.
Companies that integrate AI semiconductors, automotive software, battery data analytics, and energy efficiency management are likely to gain strength.
From this perspective, the Chinese EV breakdown controversy is not simply a negative headline.
It signals that the global EV industry is moving from low-price competition to quality competition, and then toward AI-based platform competition.
9. How Chinese EV restructuring could affect the global economic outlook
If China’s EV makers undergo a large-scale restructuring, the global supply chain will also change.
A reduction in excess production capacity in China may affect battery materials prices, vehicle pricing, and parts supply.
- If weak EV firms exit the market, downward pricing pressure may ease.
- Surviving Chinese leaders may become even stronger.
- Korean, Japanese, and European firms may gain opportunities in the premium segment by emphasizing quality and reliability.
- Tighter U.S. and European restrictions on Chinese EVs could increase the value of Korean supply chains.
That said, it would be excessive to conclude that China’s EV industry is collapsing.
China remains the world’s largest EV market and still has major players such as CATL and BYD.
The more realistic scenario is not the disappearance of the sector, but the exit of weaker players and consolidation around stronger ones.
10. Investment strategy: earnings over themes, EPS over expectations
The investment takeaway is clear.
The EV and battery sectors remain growth industries.
However, not every company will capture the benefits of that growth.
- Companies reliant only on price competition should be avoided.
- Companies with recurring quality issues are not suitable for long-term investment.
- Investors should focus on firms with clear EPS improvement.
- Companies with global customers and long-term supply contracts have an advantage.
- Firms with both AI capability and software competitiveness may receive higher valuation premiums.
In equity markets, major opportunities often emerge amid industry disruption.
The quality controversy and restructuring of Chinese EV makers may be short-term uncertainty, but they could create long-term opportunities for Korean companies.
In particular, battery manufacturers, battery material suppliers, automotive semiconductors, AI-based electronic components, and power infrastructure companies warrant continued attention.
< Summary >
The controversy over repeated failures in Chinese EVs should be viewed as a signal of restructuring in the EV industry, not as a simple accident issue.
Cases such as brake pedal failure and rear axle detachment highlight the limits of low-price competition.
Over time, weaker Chinese EV makers are likely to be displaced, while stronger firms consolidate their positions.
Korea’s battery and 2nd battery industries may face near-term volatility, but companies with quality and reliability advantages could benefit.
From an investment standpoint, EPS growth, operating margins, global customers, and technological barriers matter more than vehicle sales volume.
The next true leading stock is likely to emerge from companies that can prove their earnings, not from those that merely benefit from a theme.
[Related Articles…]
- Korea Battery Industry Outlook and Investment Priorities
- Semiconductor Cycle Reacceleration and the Next Growth Leaders
*Source: [ 달란트투자 ]
– “중국 전기차 줄줄이 고장” 사상 최악의 대참사 터졌다 | 윤석천 경제평론가 2부